


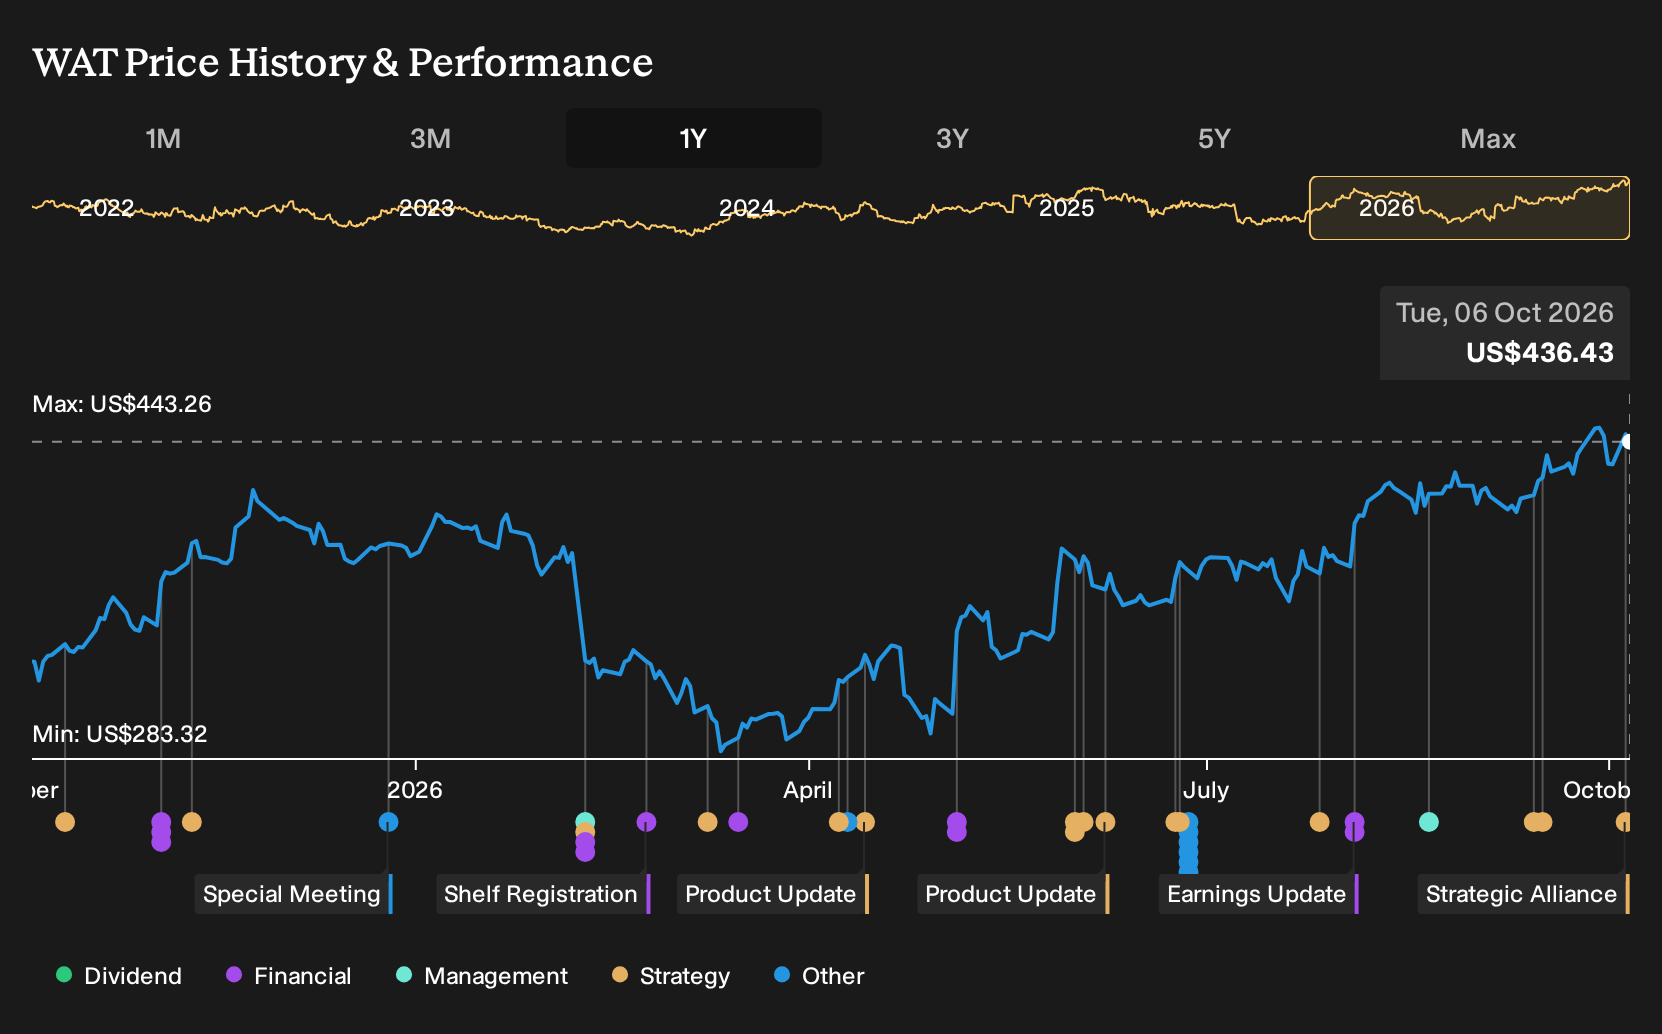
- CellCarta announced a partnership with Waters Corporation to jointly pursue companion diagnostic and next generation flow cytometry programs for pharma and biotech sponsors, combining Waters' instruments, reagents, assays and software with CellCarta's biomarker, clinical trial and commercialization capabilities across a global CDx lab network.
- The collaboration gives Waters a clearer route into end to end precision medicine workflows, where standardized, globally scalable flow cytometry and CDx solutions can deepen ties to drug developers and embed its technology in long running clinical and commercial testing programs.
- We will now look at how Waters' companion diagnostic focused alliance with CellCarta could influence the firm's broader investment narrative.
Scan beyond Waters and this CellCarta alliance by reviewing a curated group of precision medicine and high quality lab technology players in our 19 high quality undiscovered gems that are poised for bigger clinical roles.
Waters Investment Narrative Recap
To own Waters, you need to believe the business can turn a strong lab instrument and software footprint into higher quality earnings as the BD Biosciences and Diagnostic Solutions acquisition settles. The CellCarta partnership fits that story by pulling Waters technology deeper into companion diagnostics workflows, although the near term financial impact looks modest versus the scale of the core chromatography and mass spec franchises.
The most important near term swing factor remains clean execution on BD integration and margin repair after one off items and a drop in profit margins to 3.6%. China weakness and shareholder dilution are still key risks. The CellCarta deal adds another proof point on the precision medicine angle, but it does not change those central issues.
The new CellCarta agreement ties directly into Waters efforts to build recurring, application specific revenue around its installed base. By offering pharma sponsors a coordinated path from biomarker strategy through commercialization, the company is trying to make its instruments, reagents and software harder to displace and more embedded in long running testing programs.
For investors watching catalysts, this matters most if it feeds higher usage of consumables and software over time, in addition to the ongoing replacement cycle in LC and LC MS. Execution risk stays front and center. Integrating BD, managing China exposure and keeping Empower deeply integrated in digital and AI enabled workflows are still the big operational levers to track.
On current analyst assumptions, Waters' narrative projects US$7.9b revenue and US$1.4b earnings by 2029. This implies 19.3% yearly revenue growth and an earnings increase of about US$1.23b from US$166.6m today.
Discover why Waters' fair value appears to be largely consistent with its current market price.
Exploring Other Perspectives
One alternate view focuses less on BD integration risk and more on Waters' exposure to older chromatography and mass spectrometry platforms. Bullish analysts still pencilled in US$8.7b revenue and US$1.6b earnings by 2029 before this CellCarta news. You can see how such dependency concerns or optimism might shift as this partnership is gradually digested.
Explore 3 other Waters fair value estimates, including one that suggests up to 18% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Waters research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Waters. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Waters' overall financial health at a glance.
Looking for more investment ideas beyond Waters?
If this Waters and CellCarta story has sharpened your focus on precision medicine and high quality lab platforms, you can use that momentum to refresh your broader watchlist with a few focused screens.
- For readers who care most about valuation support and balance sheet strength, start with companies flagged as 27 high quality undervalued stocks that may offer a wider margin of safety.
- If income is a priority and you want payouts backed by substance, scan a curated set of 8 dividend fortresses that combine yield with robust fundamentals.
- When capital preservation matters as much as upside, widen your research to a 31 resilient stocks with low risk scores that filters for sturdier financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com