


Black Stone Minerals (BSM) is back on investors’ radar after a recent move in the unit price, prompting fresh questions about how its royalty-focused oil and gas model fits into income portfolios.
Recent trading has been quietly positive for Black Stone Minerals, with an 8.66% year to date share price return contributing to a 12.14% three year and 98.15% five year total shareholder return. This may indicate momentum that long term income focused holders will likely pay attention to.
Scan how Black Stone Minerals compares with other income focused energy plays by reviewing our curated list of 8 dividend fortresses in a similar yield and cash flow bracket.
For Black Stone Minerals, that recent unit move can signal either a quiet recognition of its royalty cash engine or just a mood shift in yield hunting. The valuation work now needs to show which story fits better.
Most Popular Narrative: 8% Undervalued
Black Stone Minerals is currently trading at $14.68 against a widely followed fair value estimate of $16.00. This suggests the royalty partnership is priced a touch below what its long term cash profile might support if the thesis plays out.
The expansion of the Shelby Trough and new development agreements, now covering about 500,000 gross acres with minimum drilling obligations ramping to 50 gross wells per year by 2031, continue to tie Black Stone Minerals to Gulf Coast natural gas demand and could support higher royalty revenue and distributable cash flow.
Continued mineral and royalty acquisitions around the Haynesville and Shelby Trough areas, with cumulative spending approaching US$300 million by mid 2026 and additional quarterly deployment, are expected to build scale and production volumes that influence future revenue and EBITDA.
See why 18 investors see Black Stone Minerals as 8% undervalued.
Result: Fair Value of $16.00 (UNDERVALUED)
Still, the story around Black Stone Minerals can change quickly if drilling setbacks persist or if heavy Haynesville and Shelby Trough spending fails to lift royalty cash flow.
Find out about the key risks to this Black Stone Minerals narrative.
Another View On Black Stone Minerals Valuation
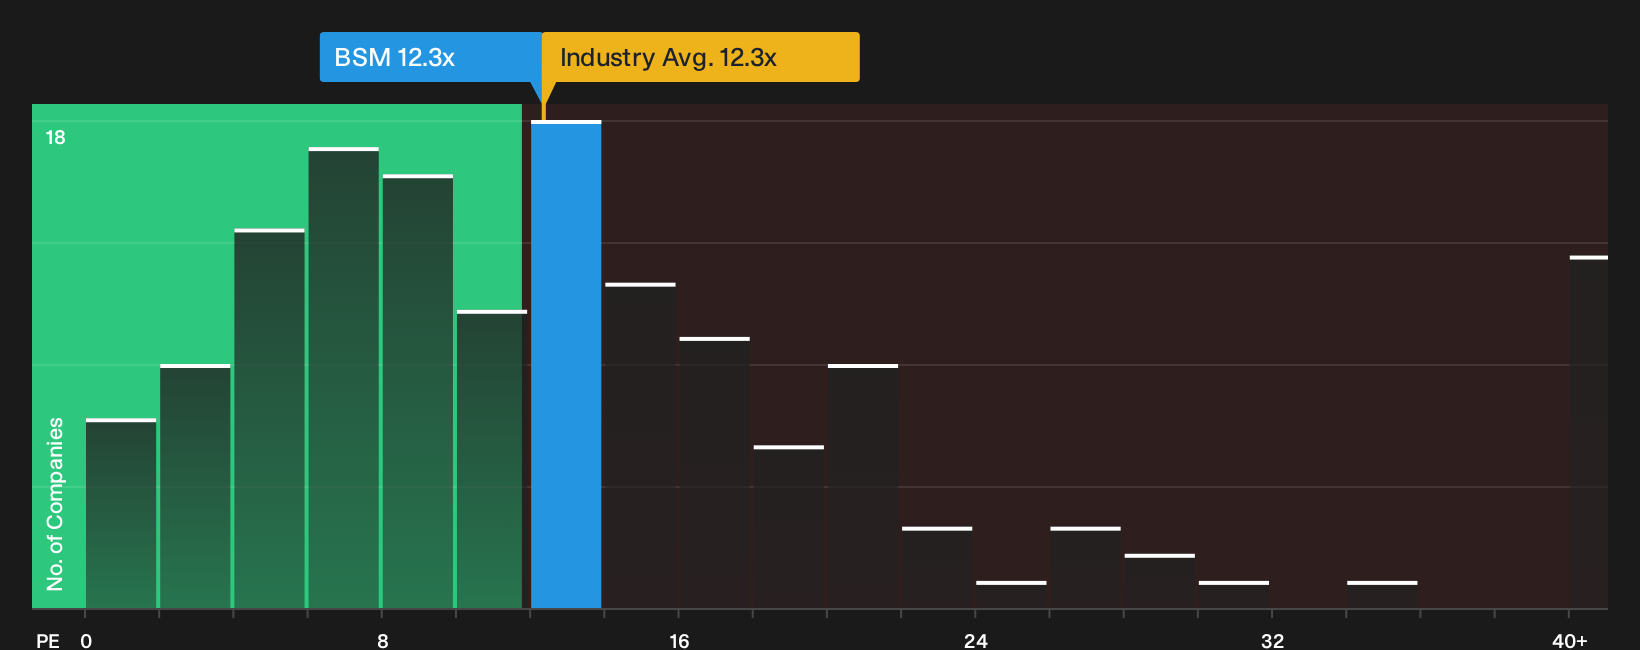
There is a twist once price ratios are brought in. Black Stone Minerals trades on a P/E of 12.3x, which is higher than the 10.3x peer average yet slightly below the US Oil and Gas industry at 12.4x and under the fair ratio of 14.6x that the market could move towards. That mix of premium to peers but discount to fair ratio raises a simple question: Is the risk here that expectations are already full, or that investors are still underpaying for the cash flows?
For a closer look at what this gap between current P/E, peers and the fair ratio might mean in practical terms for valuation risk, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Black Stone Minerals can feel messy, so move fast, review the numbers carefully, and stress test both sides using the 2 key rewards and 2 important warning signs.
Looking for more ideas beyond Black Stone Minerals?
Do not stop at Black Stone Minerals. Apply a few more quality filters and you could surface opportunities that better match your risk and income targets.
- Target resilient cash generators by scanning a list of solid balance sheet and fundamentals (25 results) that can help anchor your portfolio when conditions get choppy.
- Hunt for mispriced quality by reviewing a curated pool of 27 high quality undervalued stocks that pair sturdy finances with attractive valuations.
- Build your watchlist with income candidates by using a focused 8 dividend fortresses centered on higher yielding stocks and consistent payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com