


EVERTEC (EVTC) has drawn fresh attention after its latest share price moves, with the stock closing at US$29.05. Recent returns show a mixed pattern across the past week, month, past 3 months, and year.
Recent trading suggests that momentum in EVERTEC is trying to rebuild, with a 7.43% 7-day share price return offsetting a 4.28% decline over 30 days and set against a 1-year total shareholder return that is down 8.81%.
Spot potential rebounds and compare EVERTEC with a hand picked group of payment and fintech peers using the 27 high quality undervalued stocks.EVERTEC has bounced over the past week but still shows declines over the past year and longer. Is most of the easy upside already spent, or do the current valuation signals suggest more room to run?
Most Popular Narrative: 18% Undervalued
The most followed thesis on EVERTEC pegs fair value at $35.60, which sits above the latest close at $29.05 and presents the recent rebound as only part of the story.
Ongoing Latin America expansion through acquisitions such as Sinqia, Dimensa, Tecnobank and BBChain, combined with large processing contracts including Transbank in Chile and Clip in Mexico, is expected to shift more of EVERTEC’s revenue mix toward higher growth markets and support earnings over the next several years.
Growth in Puerto Rico Merchant Acquiring and Payment Services, with recent single digit to low double digit increases in revenue supported by higher sales volumes, transaction growth and pricing initiatives, provides a recurring cash flow base that can help fund investment while supporting overall EBITDA and free cash flow.
See why 2 investors see EVERTEC as 18% undervalued.
Result: Fair Value of $35.60 (UNDERVALUED)
Still, the EVERTEC story can be knocked off course if revenue softness in Business Solutions persists or if another cybersecurity issue undermines client confidence and contracts.
Find out about the key risks to this EVERTEC narrative.
Another View on EVERTEC’s Valuation
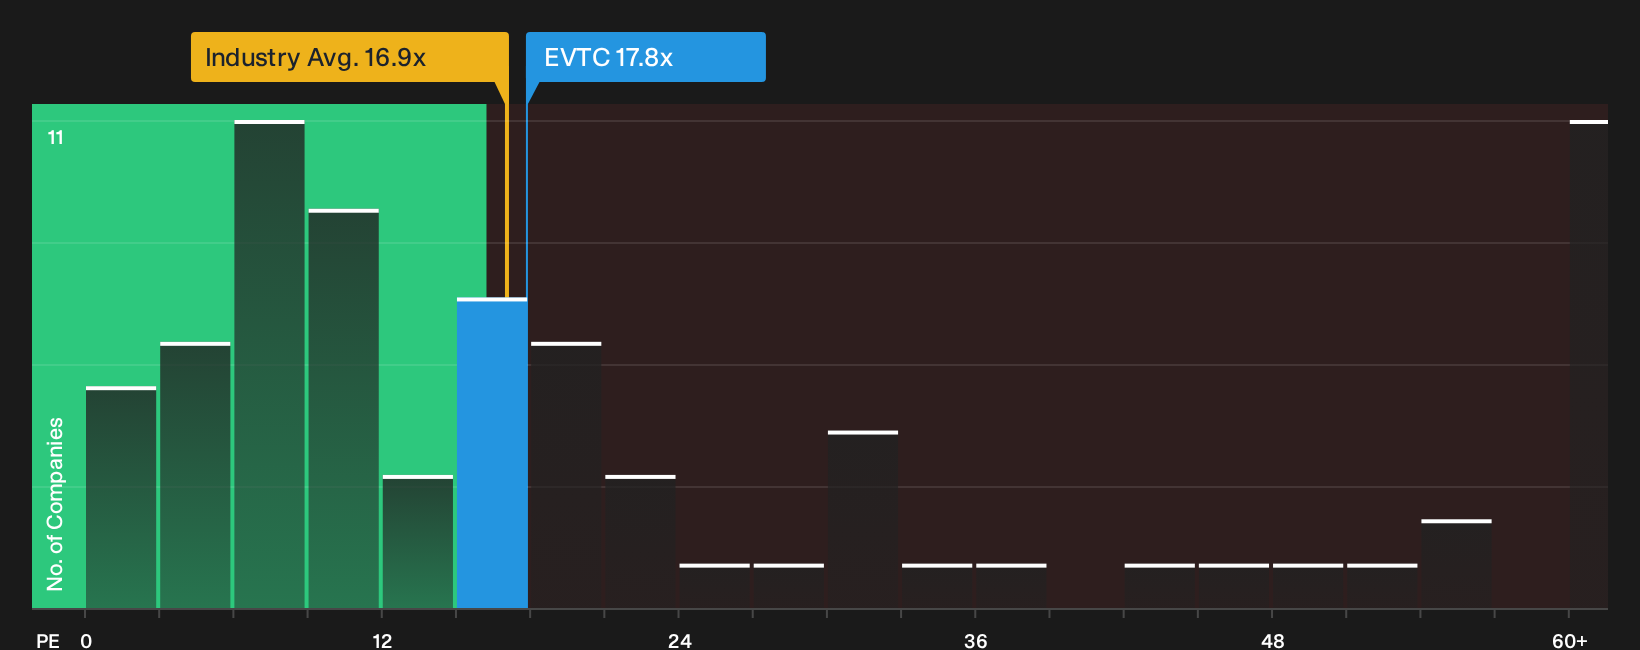
The first take paints EVERTEC as 18% undervalued on analyst fair value. A second lens tells a cooler story. At a P/E of 17.8x, the stock trades a bit richer than the US Diversified Financial industry on 17x and above its own fair ratio of 15.3x. That premium suggests investors need to be comfortable paying a higher price for the growth case, or decide the gap is valuation risk rather than opportunity.
To see how that premium could matter for your thesis, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around EVERTEC do not need to leave you on the fence. You can pressure test the data, weigh both sides, and then review the 3 key rewards and 3 important warning signs
Looking for more EVERTEC-sized investment ideas?
If you want to pressure test your read on EVERTEC and widen your opportunity set, jump into fresh stock ideas now instead of reacting after the next move.
- Target potential mispricings by scanning a focused group of quality candidates using the 27 high quality undervalued stocks.
- Prioritize resilience and sleep-at-night holdings with the help of our 31 resilient stocks with low risk scores.
- Unearth underfollowed opportunities with strong fundamentals through the 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com