


Albemarle (ALB) has caught fresh attention after a recent 1.9% daily gain left the stock ahead of the S&P 500, just weeks before its 4 November 2026 earnings release.
That single session move comes after a tougher stretch for Albemarle, with the 30 day share price return down 15.8% and the year to date share price return down 26.1%. At the same time, the 1 year total shareholder return of 18.8% shows a very different long run picture as investors weigh upcoming earnings, balance sheet debt reduction and a forward P/E that sits below the industry average.
Compare Albemarle's setup ahead of earnings with other materials and energy transition players using the curated list of 33 best rare earth metal stocks.
The latest bounce in Albemarle leaves a wide gap between the current US$106 share price and a range of fair value estimates that point much higher. Is that discount justified by risk, or does it reflect a mispricing of earnings power?
Most Popular Narrative: 53% Undervalued
Albemarle's most followed narrative pegs fair value at $225 per share, roughly double the recent $106 close. This view places significant emphasis on future lithium demand and potential margin recovery.
Analysts broadly agree that Albemarle's cost and productivity initiatives may help offset lower lithium prices. With the company reaching the high end of its $400 million target six months early, some see material upside for net margin expansion if the full benefits extend into 2026 and additional cost reduction opportunities are realized.
See why 16 investors see Albemarle as 53% undervalued.
Result: Fair Value of $225 (UNDERVALUED)
Still, prolonged lithium price weakness and potential policy shifts in key regions like Chile or Australia could quickly challenge Albemarle's margin story and fair value case.
Find out about the key risks to this Albemarle narrative.
Another View on Albemarle’s Valuation
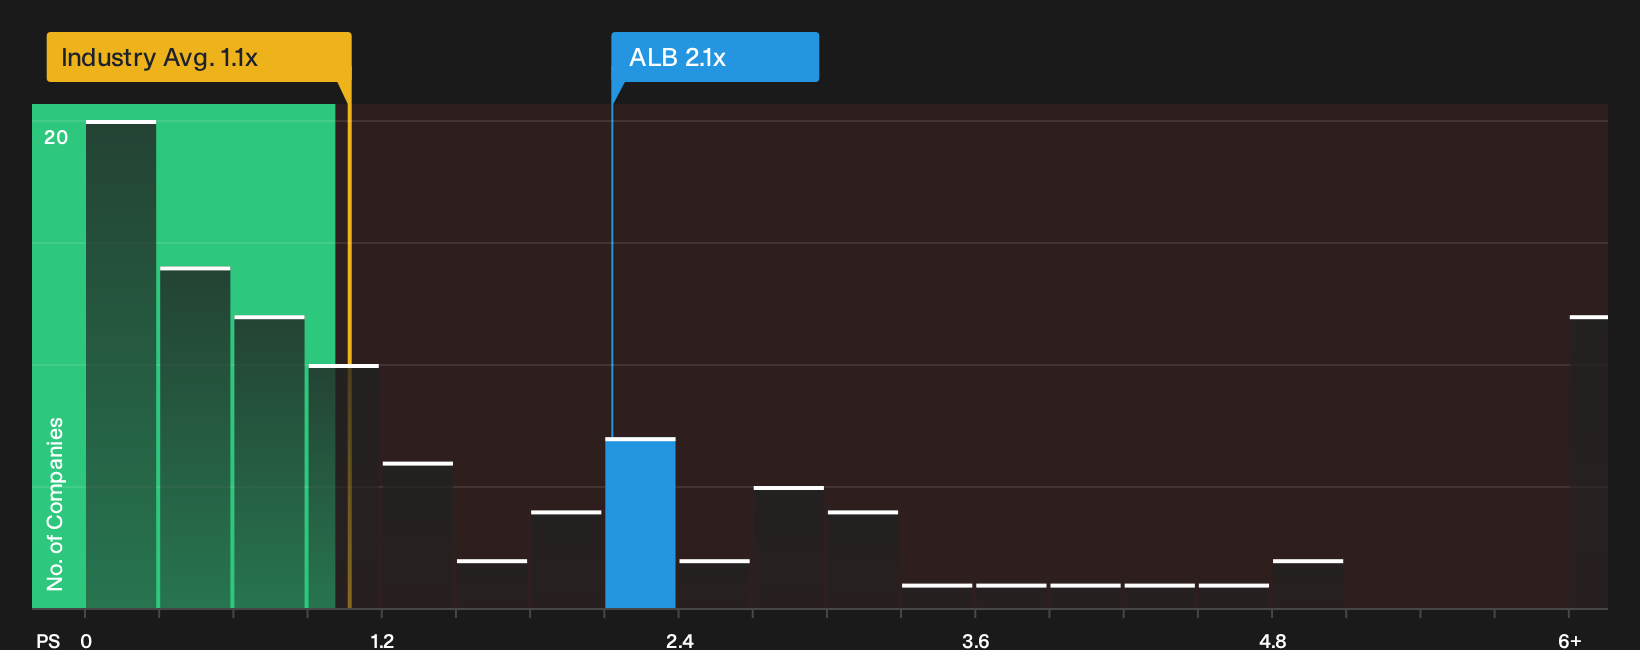
There is a catch. Albemarle screens as good value versus its own fair ratio, with a P/S of 2.1x compared with an estimated fair ratio of 1.6x, yet it also trades richer than the US Chemicals group on 1.1x. That mix of apparent discount and premium raises a simple question for investors: Which crowd is wrong about the risk in this story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Albemarle's value and risk profile only matter if you use them. Act while sentiment is divided and weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Albemarle?
If Albemarle has your attention, do not stop there. Use fresh data, clear filters and your own judgment to spot the next opportunity before the crowd.
- Target quality at a discount by scanning a curated set of 27 high quality undervalued stocks that pair solid fundamentals with prices many investors may be overlooking.
- Strengthen your downside protection by reviewing a list of solid balance sheet and fundamentals (25 results) that helps you focus on robust finances instead of fragile stories.
- Get ahead of the crowd by checking a 19 high quality undiscovered gems that surfaces lesser known businesses with numbers that still demand attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com