


- Eli Lilly received an expanded FDA approval for Jaypirca, allowing first-line use in adults with previously untreated CLL or SLL without a known 17p deletion, based on the Phase 3 BRUIN CLL-313 trial.
- The broader Jaypirca label adds another potential growth driver in Eli Lilly’s oncology portfolio. This sits alongside its large incretin and diabetes franchises and helps diversify the future revenue mix.
- We will now look at how Eli Lilly's wider first-line Jaypirca approval could reshape the broader investment narrative around oncology.
Compare Eli Lilly's oncology momentum with a curated group of potential peers by reviewing the 34 healthcare AI stocks that are advancing tech-enabled drug development.
Eli Lilly Investment Narrative Recap
Owning Eli Lilly today means buying into a thesis that incretin obesity and diabetes drugs continue to anchor the story, while oncology, immunology and neuroscience slowly carry more weight. The Jaypirca first line approval fits that idea by giving the oncology unit another approved use alongside existing cancer products, but it does not change the fact that Zepbound, Mounjaro and Foundayo still drive most expectations.
In the near term, the key swing factor remains how well Eli Lilly converts strong GLP 1 demand into durable access and margins as U.S. pricing pressure and GLP 1 litigation play out. The Jaypirca update modestly supports the argument that diversification is progressing, while the biggest immediate business risk still sits in obesity and diabetes pricing and legal outcomes rather than oncology.
The expanded collaboration with Gate Bioscience on molecular gate therapeutics is the clearest echo of the Jaypirca story. Both developments point to Eli Lilly leaning into targeted therapies and external partners to deepen its oncology and protein degradation toolkit, which can matter over time if incretin pricing becomes tougher or certain internal cancer assets stall.
For investors watching catalysts, the Gate deal is less about near term revenue and more about optionality. Successful execution would give Eli Lilly another source of high value specialty drugs that could gradually rebalance earnings away from a handful of obesity and diabetes brands, while missteps or failed programs would reinforce the risk that oncology diversification remains slower than hoped.
Eli Lilly's current analyst narrative points to revenues of US$118.9b and earnings of US$50.1b by 2029, based on an assumed 14.3% yearly revenue growth rate and an increase in earnings of about US$23.4b from US$26.7b today.
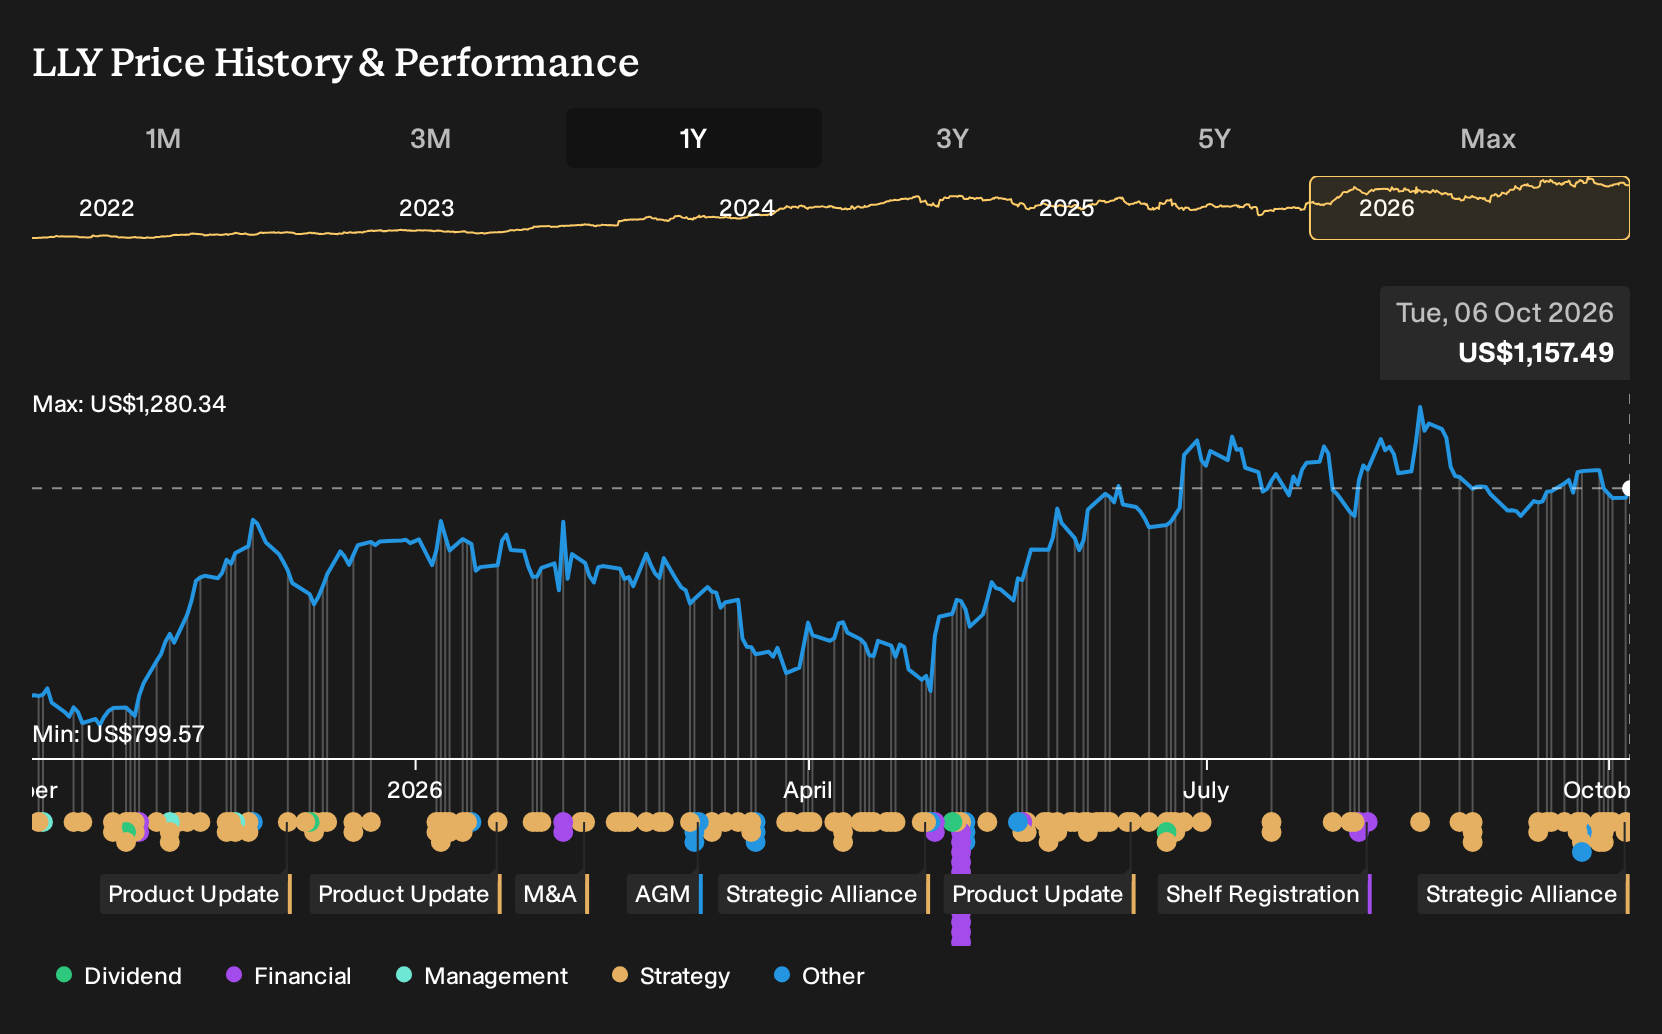
Uncover why Eli Lilly's fair value indicates a 15% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the lowest Eli Lilly analysts focus on legal and safety overhangs around GLP 1 drugs rather than oncology upside from Jaypirca or the Gate Bioscience deal. Before this news, they were working off 2029 earnings of about US$44.7b versus the consensus US$50.1b. That gap shows how far opinions can spread. You may see these oncology updates push both narratives to evolve, which is why it helps to explore a range of forecasts before deciding how Eli Lilly fits your own portfolio.
Explore 11 other Eli Lilly fair value estimates, including one that suggests it could be worth just $1,189.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Eli Lilly research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Eli Lilly. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate Eli Lilly's overall financial profile at a glance.
Looking For More Investment Ideas Beyond Eli Lilly?
If Eli Lilly's evolving oncology story has sharpened your thinking, it can help to line it up against other opportunities that match your risk tolerance, income needs, or preference for balance sheet strength. The Simply Wall St Screener lets you quickly filter for businesses that fit those preferences instead of scrolling through tickers at random.
- If you want potential upside while still focusing on fundamentals, start with a curated 19 high quality undiscovered gems that already score well on quality metrics.
- If resilience matters more to you than headline growth, you can filter for companies with sturdier finances by reviewing a list of solid balance sheet and fundamentals (25 results).
- If you are building an income focused portfolio, you can hunt for yield and stability by scanning a targeted 8 dividend fortresses that screens for stronger payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com