


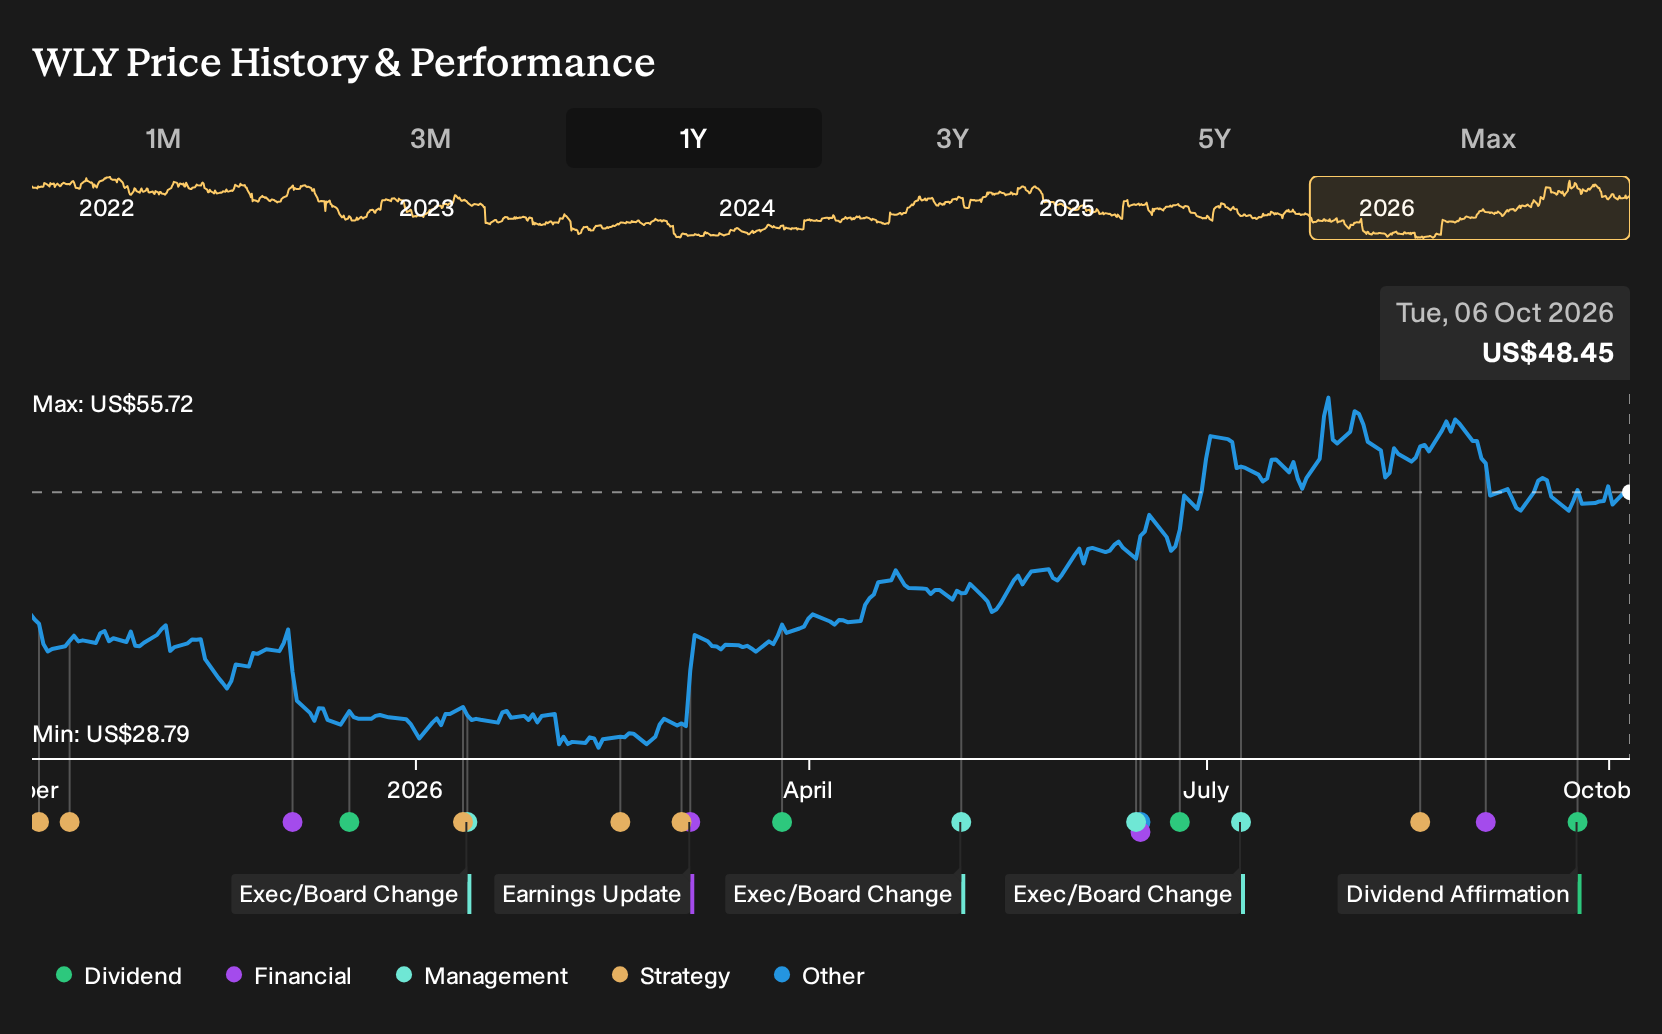
- John Wiley & Sons declared a quarterly cash dividend of $0.3575 per share on its Class A and Class B stock, payable on October 22, 2026, with an annualized rate of $1.43 per share, above the $1.42 level reported for Fiscal 2026.
- The higher regular payout indicates that John Wiley & Sons management continues to prioritize predictable cash returns. This is relevant for investors assessing how its research and learning model converts recurring revenue into steady shareholder distributions.
- Next, we consider how this higher regular dividend shapes John Wiley & Sons' investment narrative, which is built around recurring digital cash flows.
Compare John Wiley & Sons' dividend story with other income ideas by scanning our hand picked 8 dividend fortresses that focus on consistency and balance sheet strength.
John Wiley & Sons Investment Narrative Recap
To own John Wiley & Sons, you need to believe its research journals, Open Access titles, AI licensing and digital courseware can keep generating recurring cash flows even as print and legacy channels face pressure. The slightly higher dividend reflects management's confidence in current cash generation, but it does not change the key near term swing factors around AI and Open Access demand.
The main potential upside catalyst is execution on digital research and learning platforms, along with further uptake of AI and data partnerships. The biggest risk is that AI content licensing proves lumpy or that pricing pressure from Open Access and alternative models compresses margins. The dividend move appears incremental rather than a material shift in that risk reward profile.
The most relevant update is the Board's decision to declare a US$0.3575 quarterly dividend, equivalent to US$1.43 on an annual basis, slightly above Fiscal 2026's US$1.42. That sits alongside a profile where earnings are forecast to grow 4.99% a year and the stock trades on a P/E of 12.4x, below both peer averages and some fair value estimates.
For an income focused holder, the key question is whether John Wiley & Sons can keep covering that payout while managing high debt and exposure to academic funding cycles. Execution on restructuring, digital subscriptions and AI licensing will likely matter more to the medium term story than this US$0.01 annual dividend uplift, but the reaffirmed payout helps frame expectations around cash returns.
John Wiley & Sons' current analyst story points to revenues of US$1.9b and earnings of US$224.2m by 2029, which lines up with an assumed 4.7% yearly increase in revenue and an earnings move of about US$2.6m from US$221.6m today to that 2029 consensus figure.
Uncover why John Wiley & Sons' fair value indicates a 40% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The Simply Wall St Community currently shows 2 retail fair value views for John Wiley & Sons, ranging from US$68 to about US$81.32 per share. Those opinions sit alongside meaningful AI licensing uncertainty and pressure on traditional publishing. Use that spread to stress test your own thesis and compare multiple viewpoints before acting.
Explore another John Wiley & Sons fair value estimate, including one that suggests there could be as much as 68% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your John Wiley & Sons research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for John Wiley & Sons. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate John Wiley & Sons' overall financial health at a glance.
Looking For More Investment Ideas Beyond John Wiley & Sons?
If the John Wiley & Sons story has you rethinking where dependable cash flows and sensible balance sheets might come from next, use this moment to widen your search with a few focused stock lists built around specific income and quality angles.
- For investors who want potential mispricing backed by strong fundamentals, review a curated 27 high quality undervalued stocks that may merit a closer look.
- If capital preservation sits near the top of your checklist, start with a 31 resilient stocks with low risk scores that screens for resilience before anything else.
- When the goal is durable payout capacity, scan a list of solid balance sheet and fundamentals (25 results) that aims to pair income potential with financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com