


USA Rare Earth has seen its share price fall sharply over the past year, even as it has secured sizeable funding and completed a leadership transition. That mix of market pressure and fresh capital raises a simple question for investors who care about balance sheet strength: Is the current price still in line with what the company’s book value can support?
- Over the past 12 months the stock has declined 51.4%, which puts the focus squarely on whether the recent slide has already reset expectations around the value of the business on paper.
- The combined US$3.1b of government and private funding can reshape the firm’s asset base and future capital needs, which may change how you think about the relationship between its share price and stated equity value.
- Your read on USA Rare Earth is one view; the desks covering it have another. See what analysts think USA Rare Earth's shares could be worth.
For investors, the debate is whether USA Rare Earth’s current share price is adequately supported by the book value backing each share.
If you want a broader starting point alongside USA Rare Earth while you think about book value support, it can help to scan 33 best rare earth metal stocks.
Is USA Rare Earth Still Cheap on Book Value?
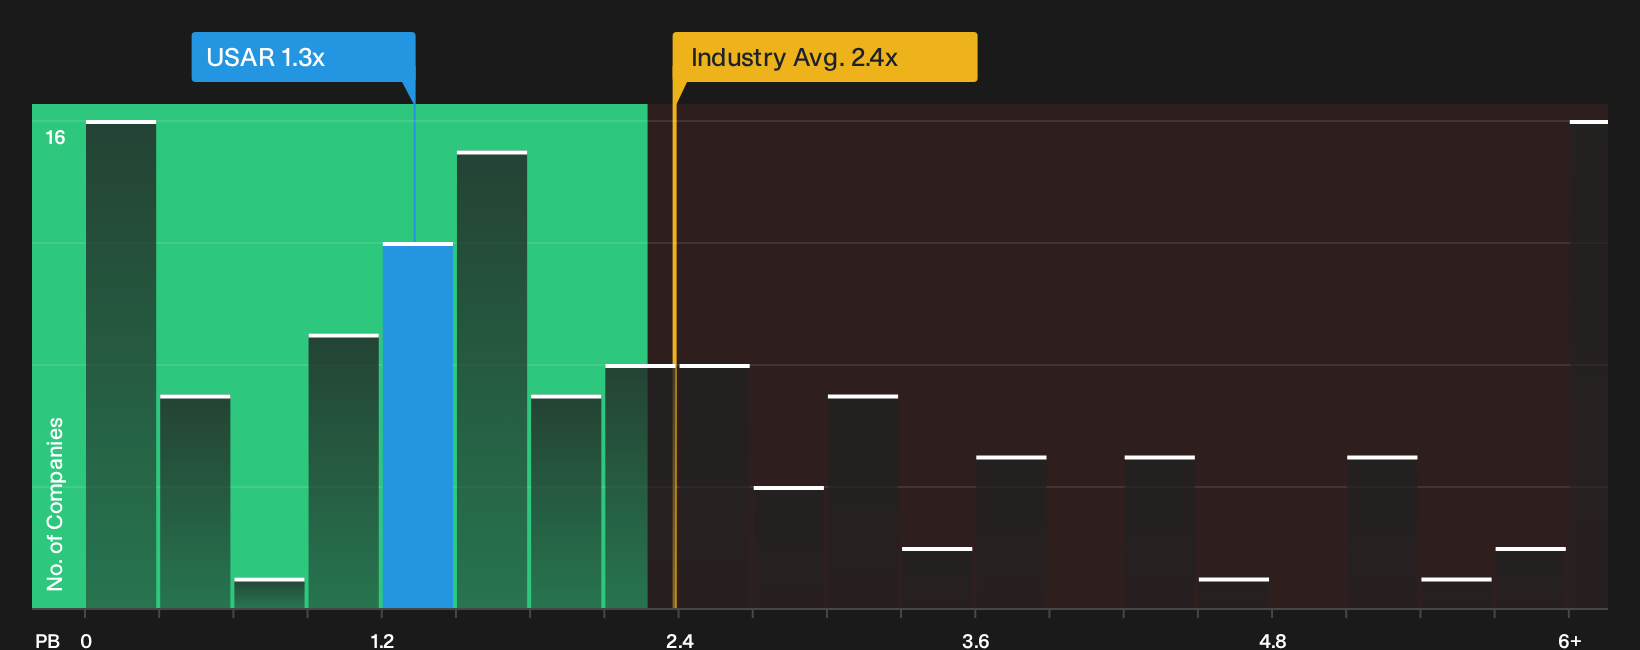
P/B fits USA Rare Earth because book value still does most of the heavy lifting in how investors frame a pre production mining project. On this lens, the shares trade around 1.3x P/B, which is well below the Metals and Mining industry average of roughly 2.4x and also under the peer group near 6.6x. That gap suggests the market is pricing the equity at a discount to the sector’s typical valuation of net assets.
Despite the fresh US$3.1b funding package raising attention around USA Rare Earth, the current P/B multiple still values the balance sheet more conservatively than many peers. You would need to weigh that discount against the execution risks around bringing Round Top into meaningful production, plus questions raised about ore quality and processing, to judge whether the lower multiple simply reflects those uncertainties or leaves room for a re rating. Explore the numbers behind USA Rare Earth's P/B valuation.
The USA Rare Earth Narrative: What Would Justify Today's Price?
Narratives for USA Rare Earth pick up where the valuation puzzle leaves off. They spell out which paths for production, margins and earnings would need to unfold for the stock to be worth meaningfully more or less than today's price. They sit on Simply Wall St's Community page so you can see the story behind the ratios. Where a single multiple or model gives one figure, these narratives describe the future that number leans on so you can watch how it plays out.
The USA Rare Earth community splits between those who see deep value in the integrated mine to magnet build out and others who think the recent funding news already prices in too much optimism.
Bull case: 61% undervalued
"A strong cash position above US$400 million, planned additional cash from warrant exercises of US$123 million and no significant debt give the company room to invest around US$100 million into Stillwater upgrades, Line 1b and human capital…"
Discover why this Narrative puts USA Rare Earth at 61% undervalued.
Bear case: 4064% overvalued
"CEO Barbara Humpton described the DOE selection as “an important validation of our team’s cutting edge work to build a resilient rare earth value chain,” reinforcing the company’s strategy to establish a vertically integrated mine to magnet capability…"
Explore why this Narrative puts USA Rare Earth at 4064% overvalued.
One more USA Rare Earth check that sits beyond the share price math
Price ratios only tell part of the story, because the real drivers are the people steering USA Rare Earth and the way their pay is structured against your interests. See who runs USA Rare Earth and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com