


Life Time Group Holdings (LTH) is expanding its footprint in Greater Boston, with plans for a roughly 45,000-square-foot athletic club at Commonwealth Pier in the Seaport District scheduled for late 2027.
Against that expansion backdrop, Life Time Group Holdings has seen mixed short term trading, with the 30 day share price return down 6.6% and the 90 day share price return down 2.7%. However, momentum over a longer stretch remains strong, given the 51.3% year to date share price return and a 1 year total shareholder return of 55.0%.
Scan for other fitness and consumer services players showing similar expansion stories and price momentum by reviewing our hand picked list of 19 high quality undiscovered gems.
Life Time Group Holdings has already rewarded anyone who benefited from the recent climb, even as the last month cooled off. The next decision is whether to establish a position at the current price or wait for a lower entry point, which comes down to valuation.
Most Popular Narrative: 28% Undervalued
Life Time Group Holdings last closed at $40.38, while the most followed narrative pegs fair value at $56.07. The debate centers on whether premium clubs and wellness services can support that gap over time under a 9.54% discount rate.
The expanding pipeline of new and larger Life Time Group Holdings club openings in affluent and high-density markets is now supported by guidance for 14 openings in 2026 and 12 to 14 in 2027, with management describing several recent locations reaching contribution-margin positive within a few months and reporting cash-on-cash returns above 30%, which points to further membership and revenue growth as the footprint increases.
See why 10 investors see Life Time Group Holdings as 28% undervalued.
Result: Fair Value of $56.07 (UNDERVALUED)
Still, the Life Time Group Holdings story can change quickly if heavy 2026 capital spending squeezes cash flow or if premium pricing begins to face resistance.
Find out about the key risks to this Life Time Group Holdings narrative.
Another View On Life Time Group Holdings
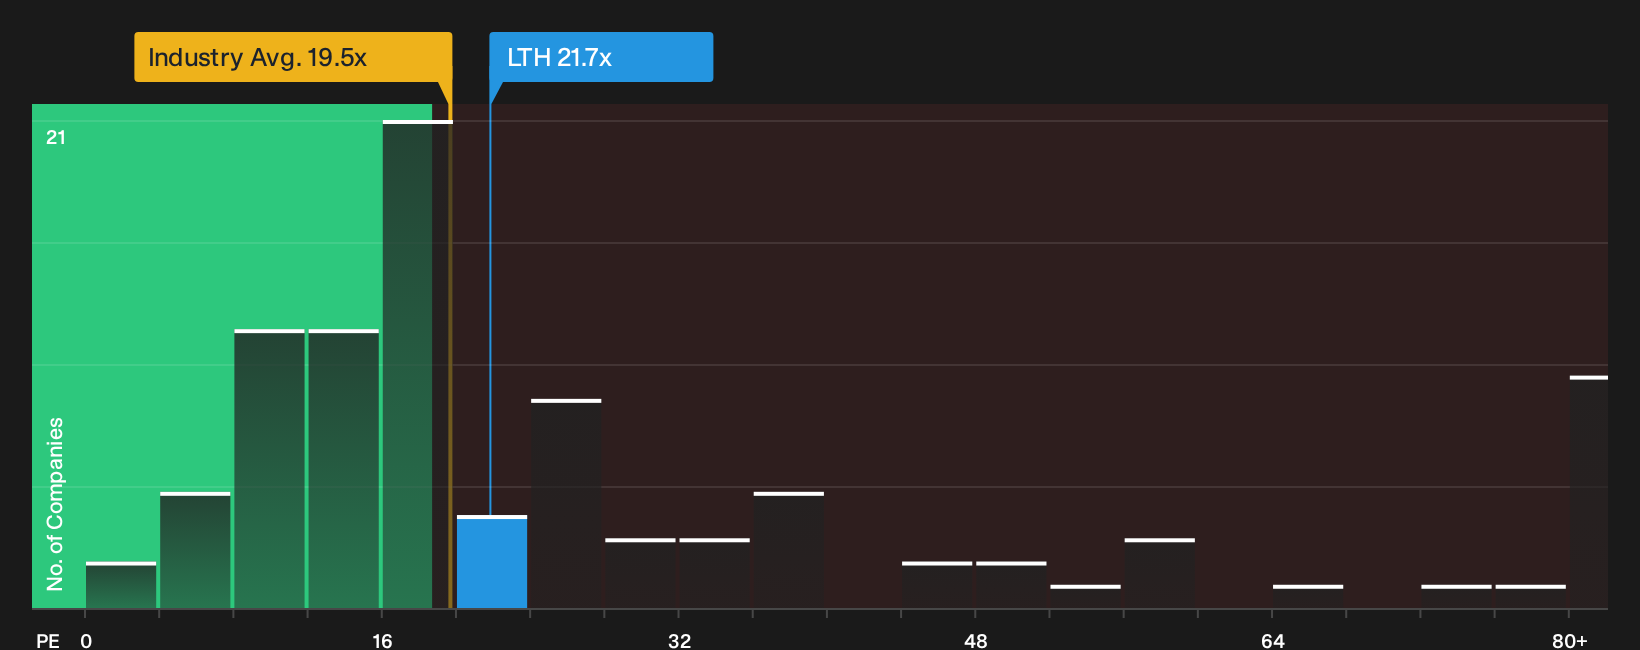
The first narrative framed Life Time Group Holdings as undervalued at $40.38 against a $56.07 fair value. A different lens tells a cooler story. At a P/E of 21.7x, the stock trades above the US Hospitality average of 19x and above its own fair ratio of 20x. That gap points to less obvious upside and more re rating risk if expectations ease, so which signal matters more to you?
To see how that P/E premium stacks up against peers and the fair ratio in more detail, See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Life Time Group Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views on Life Time Group Holdings are clear already, with both risks and bright spots emerging from the same set of numbers. Act quickly to review the evidence for yourself, and then weigh the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Life Time Group Holdings?
If Life Time Group Holdings has your attention, do not stop here. Fresh opportunities appear when you compare different business models, risk levels, and income profiles side by side.
Use the Simply Wall Street Screener to find ideas that match your approach before they move without you.
- Target value opportunities with strong fundamentals by reviewing our hand picked list of 27 high quality undervalued stocks.
- Build a more resilient core in your portfolio by focusing on companies with robust finances in the list of solid balance sheet and fundamentals (25 results).
- Strengthen your income stream by checking out companies offering higher yields in the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com