


- ConocoPhillips has signed a 20 year agreement to buy 1 million tons of LNG a year from Venture Global starting in 2030, supporting its goal to build a 10 to 15 million ton portfolio while it reviews potential divestitures in the North Sea.
- The LNG offtake deal gives ConocoPhillips more contracted gas volumes at the same time as it reshapes its asset base toward lower cost, higher efficiency projects, which directly affects future cash flow quality and project execution risk.
- We will now look at how ConocoPhillips' expanding long term LNG commitments reshape the investment narrative investors are using today.
ConocoPhillips Investment Narrative Recap
To own ConocoPhillips, you need to be comfortable with a business that leans heavily on large, long life oil and LNG projects and accepts the execution risk that comes with them. The latest LNG offtake deal fits that script but does not change the near term story, which centers on delivering Willow, Port Arthur, Qatar LNG trains and keeping Permian reinvestment in check.
The most important short term swing factor remains project timing and capital discipline, because delays or higher spending can pressure free cash flow and slow any improvement in margins. The biggest risk is still disruption or cost creep across capital intensive projects and geopolitically exposed regions such as Iraq, Syria and Libya, rather than this new contract.
The new 20 year Venture Global LNG agreement is the announcement that matters most here because it directly adds long term marketed gas volumes to ConocoPhillips' planned 10 to 15 million ton LNG portfolio. It builds on the previously secured 12 MTPA of LNG offtake and reinforces the idea that LNG marketing could become a larger earnings contributor over time.
For investors watching catalysts, this contract sits alongside Port Arthur and Qatar LNG milestones as part of a broader LNG build out that could support the targeted US$7b free cash flow uplift by 2029 if execution stays on track. The operational risk is clear, however. Larger LNG exposure raises sensitivity to project delays, regional conflict and supply chain issues that could limit the benefit from these commitments.
ConocoPhillips' current narrative assumes revenue grows at 1.8% a year, taking overall income to a forecast US$68.0b with earnings of US$11.4b by 2029. This implies an earnings increase of about US$2.1b from the US$9.3b reported today.
Uncover why ConocoPhillips' fair value indicates a 13% potential upside to its current price, before the discount starts to close.
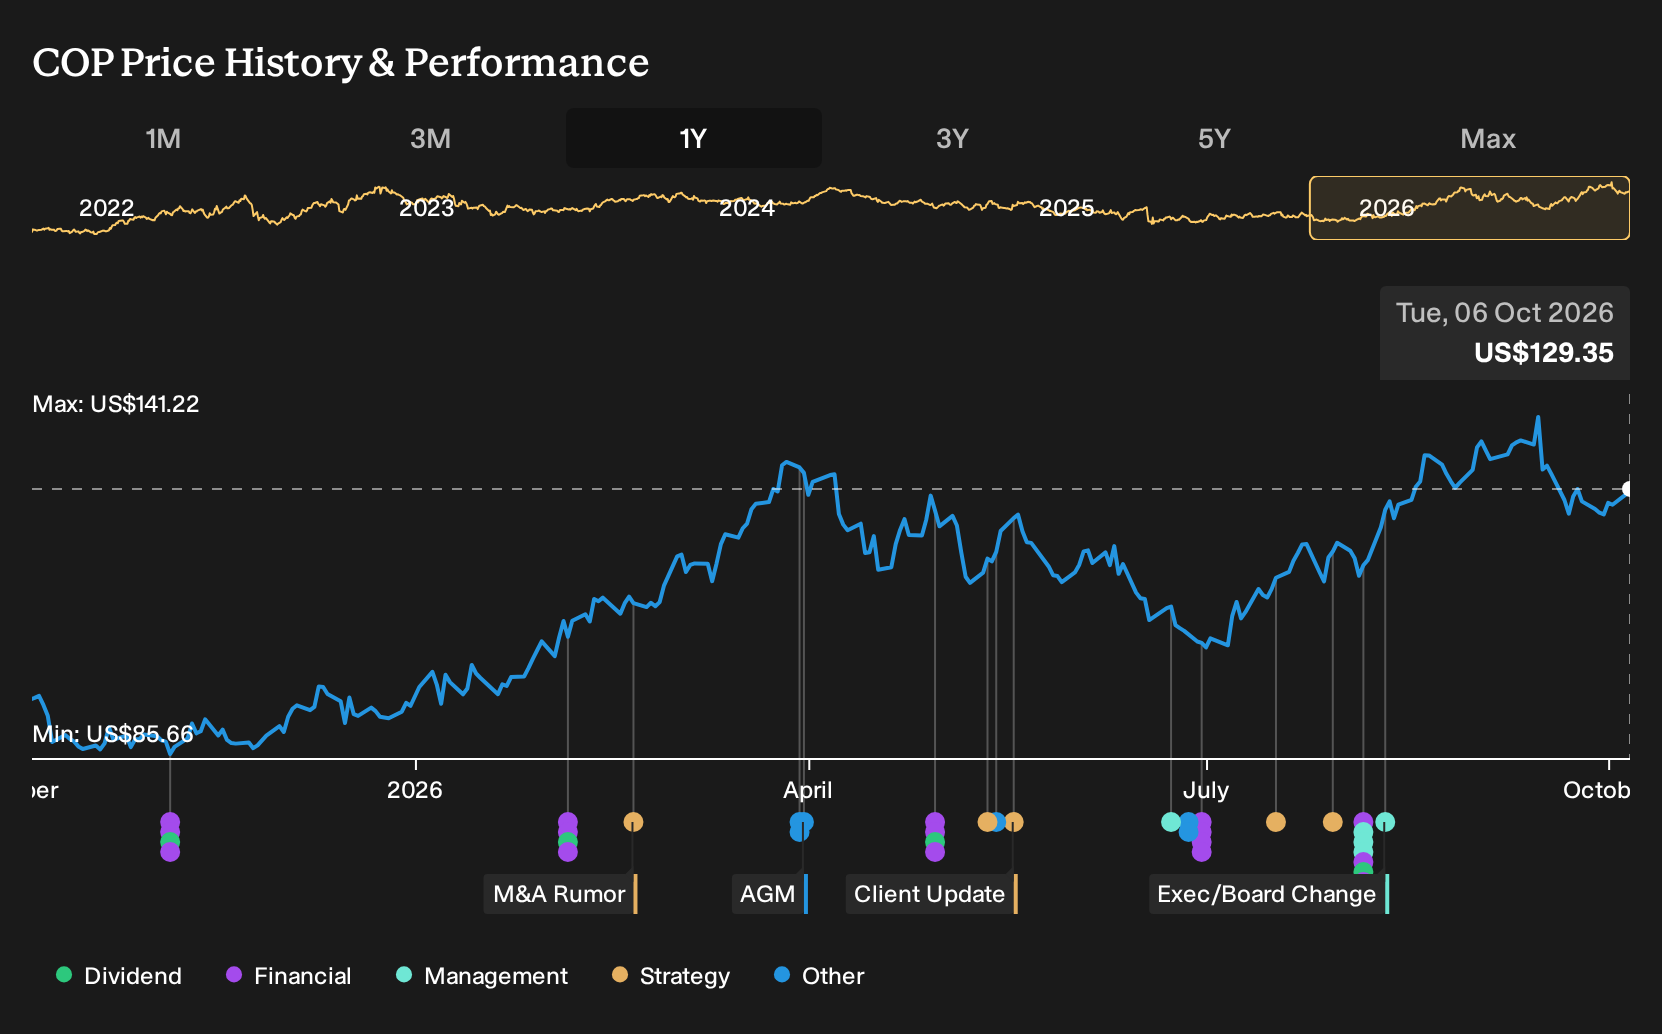
Exploring Other Perspectives
Some of the most optimistic analysts already pencilled in revenue of US$70.3b and earnings of US$11.9b by 2029 for ConocoPhillips, banking on LNG expansion as a key driver. You might see this new 20 year LNG deal as strengthening that view, or you might question it. Either way, it is worth comparing several narratives before deciding what makes sense to you.
Explore 3 other ConocoPhillips fair value estimates, including one that suggests up to 167% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ConocoPhillips research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ConocoPhillips. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ConocoPhillips' overall financial health at a glance.
Looking For More Ideas Beyond ConocoPhillips?
If you want to pressure test your view on ConocoPhillips, compare it with other companies that match your risk profile and income goals. The Simply Wall St Screener can surface targeted shortlists so you spend time assessing businesses, not trawling through tickers.
- If capital preservation comes first for you, start with a group of 31 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- Income focused investors can scan a curated set of 8 dividend fortresses that pair higher yields with fundamental checks on earnings and cash coverage.
- For those hunting for mispriced opportunities, work through a hand picked pool of 19 high quality undiscovered gems that combine quality metrics with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com