


Jefferies recently highlighted Tokyo Seimitsu (TSE:7729) as a leading pick in Japan’s semiconductor equipment sector following increased AI and high performance computing demand, first quarter sales and profit growth, and upgraded multi year sales guidance.
Tokyo Seimitsu’s recognition by Jefferies comes after a powerful run in the stock. The share price is up 16.45% over the past 30 days and 77.68% year to date. In addition, the 1 year total shareholder return of 96.10% and 5 year total shareholder return of 472.55% point to momentum that has been building over a longer stretch rather than appearing overnight.
Capture the AI-driven momentum behind Tokyo Seimitsu, and then scan a curated set of peers powered by similar demand trends with the 91 AI infrastructure stocks.The question now is simple. After Tokyo Seimitsu’s sharp AI fueled rerating and a share price just shy of Jefferies’ target, does it make more sense to pay up today or wait for a softer entry as expectations reset?
Preferred P/E of 31.8x for Tokyo Seimitsu: Is it justified?
Tokyo Seimitsu is trading on a P/E of 31.8x, which prices in a lot of optimism given the recent share price run and the proximity to the ¥20,837.5 analyst target from a last close of ¥20,495.
The P/E ratio compares the current share price to earnings per share. For a semiconductor equipment manufacturer like Tokyo Seimitsu, it effectively tells you how much investors are willing to pay today for each unit of current profit while they look ahead to expected demand from AI and high performance computing. With earnings forecast to grow 16.3% per year and revenue projected to expand 11.2% per year, the valuation reflects expectations that this growth profile continues.
The current tag is not cheap relative to peers or to a fair value benchmark. The stock trades at a premium to both the peer average P/E of 28.4x and the Japan semiconductor industry average of 23.2x, and it also sits well above the estimated fair P/E of 22.9x, which is a level the market could move towards if enthusiasm fades.
Explore the SWS fair ratio for Tokyo Seimitsu.
Result: Price-to-earnings of 31.8x (OVERVALUED)
Still, the Tokyo Seimitsu story can be knocked off course if AI hardware spending slows or if competition squeezes pricing on key semiconductor tools.
Find out about the key risks to this Tokyo Seimitsu narrative.
Another view on Tokyo Seimitsu’s value
Tokyo Seimitsu looks expensive on a 31.8x P/E, yet the SWS DCF model points the other way. On that framework, the shares trade above an estimated future cash flow value of ¥13,053.12, which implies the recent AI premium could be front loading a lot of tomorrow’s optimism into today’s price.
Look into how the SWS DCF model arrives at its fair value.
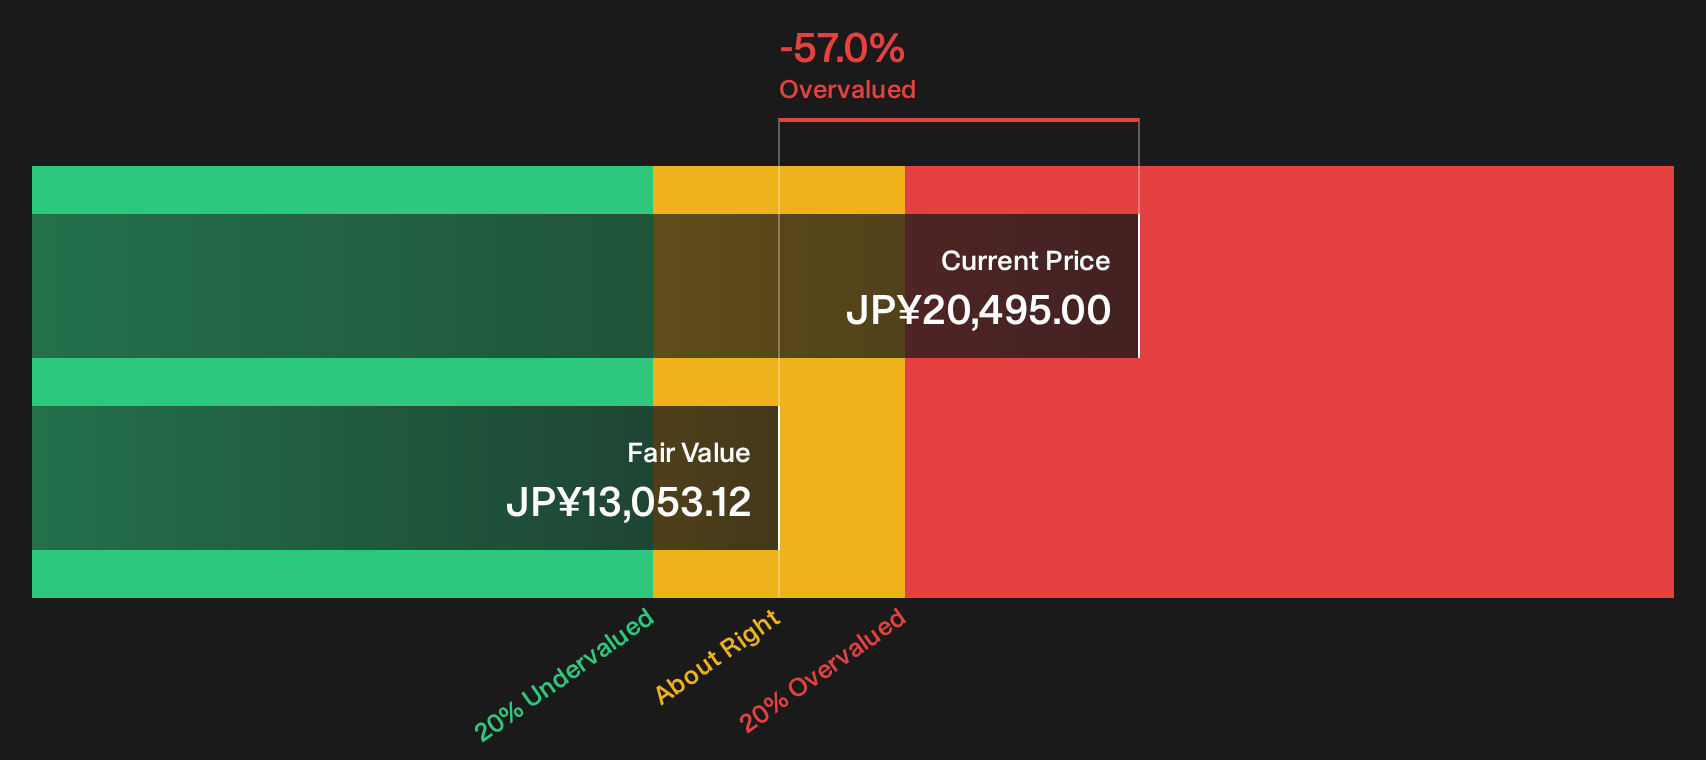
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tokyo Seimitsu for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
AI enthusiasm around Tokyo Seimitsu is clear, but your verdict should be grounded in your own work and risk tolerance, so weigh the upside against the red flags and positives in the 2 key rewards and 1 important warning sign
Looking for more ideas beyond Tokyo Seimitsu?
If Tokyo Seimitsu has sharpened your interest in AI linked opportunities, you can broaden your watchlist using focused screens that surface companies with very different risk and return profiles.
- Explore potential bargains before the crowd by running a focused search on 14 high quality undervalued stocks.
- Strengthen the core of your portfolio by scanning a list of solid balance sheet and fundamentals (23 results) that may be better able to handle tougher conditions.
- Search for underfollowed candidates by reviewing 75 high quality undiscovered gems before they attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com