


Toho Bank (TSE:8346) has raised its profit forecasts for the current half year and full fiscal year, while also lifting dividend guidance, after expecting stronger interest income on loans and securities.
Despite a small pullback in the last day with a 1-day share price return that declined 2.34%, Toho Bank’s recent guidance upgrade comes after a strong run, with a 30-day share price return of 12.49% and a 90-day gain of 36.32% that may indicate building momentum as investors react to higher profit and dividend expectations. Over a longer horizon, the picture is even stronger, with year-to-date share price growth of 105.47% contributing to a very large 1-year total shareholder return of 164.61% and a 5-year total shareholder return of more than 5x. This indicates that the market has already been reassessing the bank’s prospects and payout profile over time.
Spot similar momentum shifts by scanning our handpicked 75 high quality undiscovered gems, which, like Toho Bank, are updating guidance and reshaping their shareholder return story.After that kind of rerating in Toho Bank, the real question is where fair value now sits in relation to the spread between its share price and updated earnings and dividend estimates.
Price-to-Earnings of 19.9x: Is it justified?
Valuation has shifted sharply for Toho Bank, with the stock now trading on a P/E of 19.9x that sits above both peers and the wider Japanese banks industry at the last close of ¥1,126.
The P/E ratio compares the share price with earnings per share and acts as a shorthand for how much investors are willing to pay for each unit of profit. For a regional lender like Toho Bank, that figure often reflects views on the stability of interest income, credit quality, and how repeatable current earnings really are.
Here, the recent track record is strong. Management has taken the business from loss making to profitable over the past five years, with earnings growing by 36.2% per year on average and by 70.5% in the most recent year. Net profit margins also widened from 12.5% to 17.5%, and that profit expansion outpaced the Japanese banks sector, where earnings grew 41.5% over the same period. Those trends go a long way toward explaining why the market might be comfortable paying more for each yen of profit.
The current valuation still looks punchy when set directly against peers though. The stock trades at a P/E of 19.9x compared with a peer average of 16.7x and a broader JP Banks industry average of 16.5x. That gap suggests investors are already pricing in better profitability or resilience than the typical bank and leaves less margin for error if earnings momentum or margin strength slows from here.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 19.9x (OVERVALUED).
Still, the story can break if loan demand softens in Toho Bank’s home market, or if credit costs rise and squeeze those recently improved margins.
Find out about the key risks to this Toho Bank narrative.
Another View: Toho Bank Versus Our DCF Value
The P/E points to an expensive Toho Bank, yet the SWS DCF model goes even further. On that cash flow view, the shares around ¥1,126 trade well above an estimated value of about ¥360. This frames the recent rerating as a rich one and raises a simple question: How much optimism are you really paying for?
Look into how the SWS DCF model arrives at its fair value.
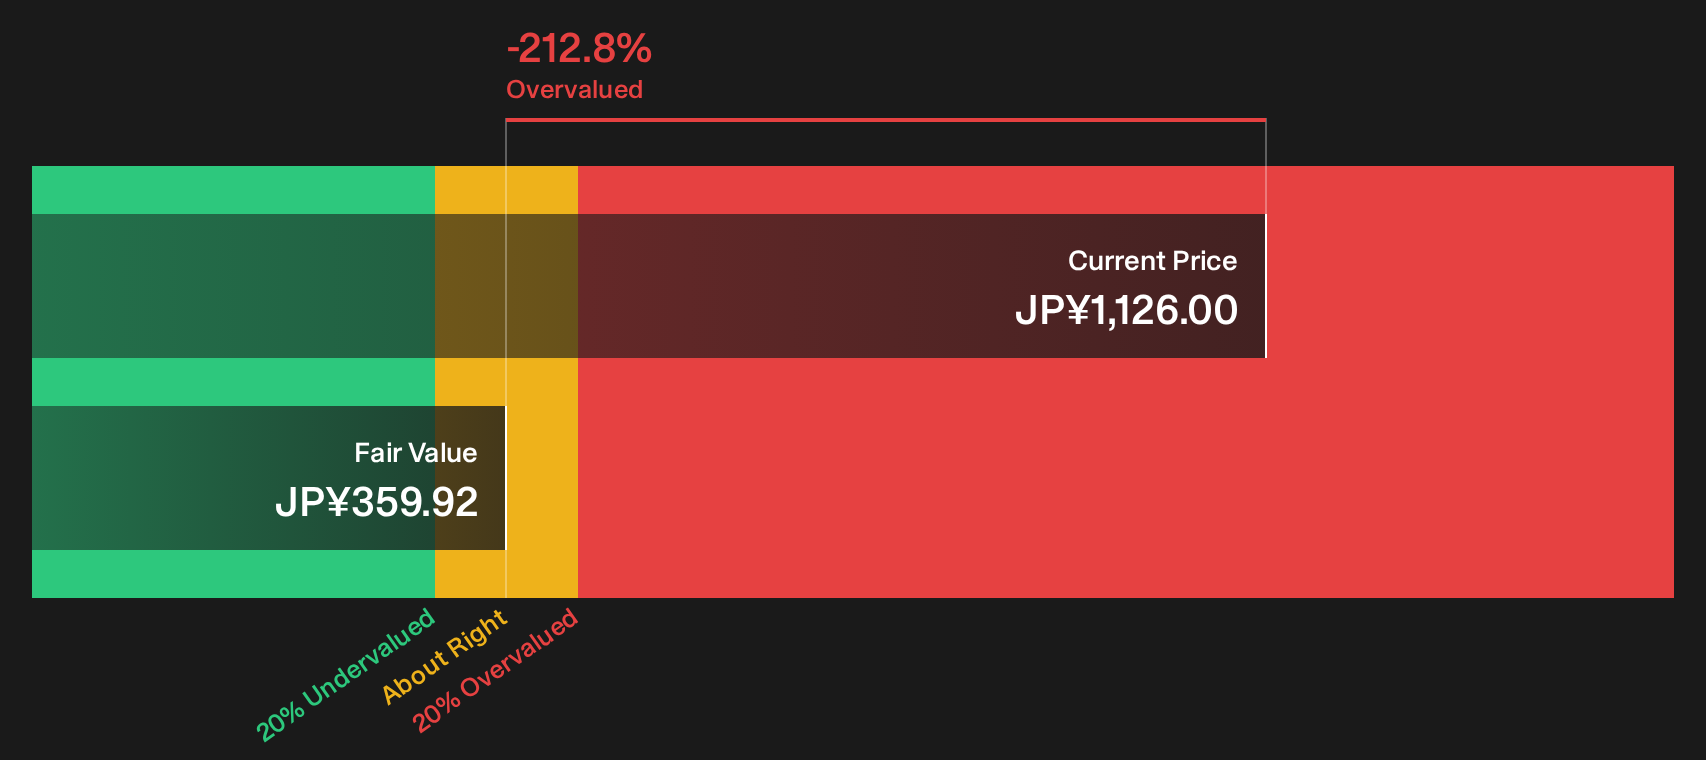
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Toho Bank for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Seen enough to sense both optimism and caution around Toho Bank but still unsure where you land? Act while the data is front of mind and weigh both the upside and the red flags by checking the 1 key reward and 3 important warning signs.
Looking for more ideas beyond Toho Bank?
If Toho Bank has sharpened your attention, do not stop there. Broaden your watchlist now and give yourself more choices before the next rerating wave hits.
- Target quality at a discount by scanning the 14 high quality undervalued stocks that pair solid fundamentals with room for sentiment to catch up.
- Strengthen your income stream by reviewing the 22 dividend fortresses that focus on yields with more robust payout profiles.
- Dial down portfolio stress by filtering for the 22 resilient stocks with low risk scores that score well on resilience and financial stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com