


Bitmine Immersion Technologies (BMNR) heads into its TOKEN2049 Singapore appearance on 7 October with chairman Tom Lee sharing the stage, giving investors fresh context around the company’s Ethereum treasury, share buybacks and staking strategy.
Recent trading has been choppy for Bitmine Immersion Technologies, with the share price down 2.2% on the day and 16% year to date. However, a 76.3% three-month share price return shows momentum picking up again after heavy one-year total shareholder losses of 55.7% and a mixed multi-year record.
Scan for other crypto exposed plays showing similar momentum shifts using our curated 21 cryptocurrency and blockchain stocks that is aligned with themes around Bitmine Immersion Technologies.
For Bitmine Immersion Technologies, that sharp three month rebound sits awkwardly against deep one year losses and a heavy unrealized ETH hit. Is this price action catching up to the balance sheet, or is it simply chasing sentiment into TOKEN2049?
Preferred Price-to-Book of 1.4x: Is It Justified for Bitmine Immersion Technologies?
Valuation right now hinges on a simple comparison. Bitmine Immersion Technologies trades on a P/B of 1.4x, while both its US Software peers and its closer comparables sit on far richer multiples.
The price to book ratio looks at what you pay for each dollar of net assets on the balance sheet. For a business like Bitmine Immersion Technologies, where reported earnings are still loss making and returns on equity are negative, asset based markers can sometimes give clearer context than profit based ratios.
With BMNR described as good value versus the broader US Software industry P/B of 2.8x and an even higher peer average of 6.2x, the market is assigning a much lower premium to its equity base. That gap is wide, and it suggests investors are either pricing in meaningful execution risk around its blockchain and digital asset operations, or are being cautious relative to the balance sheet value today.
This discount is striking when set against those comparison points. Relative to both the industry and direct peers, Bitmine Immersion Technologies sits on a materially lower P/B multiple, which implies the share price is not reflecting the same level of optimism embedded in similar software and crypto exposed stocks.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-book of 1.4x (UNDERVALUED).
Still, two pressure points hang over the Bitmine Immersion Technologies story: heavy reported losses and reliance on crypto related activity that can shift quickly around sentiment.
Find out about the key risks to this Bitmine Immersion Technologies narrative.
Another View: Bitmine Immersion Technologies Looks Expensive on Cash Flows
The price to book story paints Bitmine Immersion Technologies as cheap, but the SWS DCF model sends a different signal. On that framework, BMNR at $26.20 trades far above an estimated future cash flow value of about $0.01 per share. This indicates a high bar for the business to clear.
Investors weighing up BMNR using this cash flow lens can Look into how the SWS DCF model arrives at its fair value.
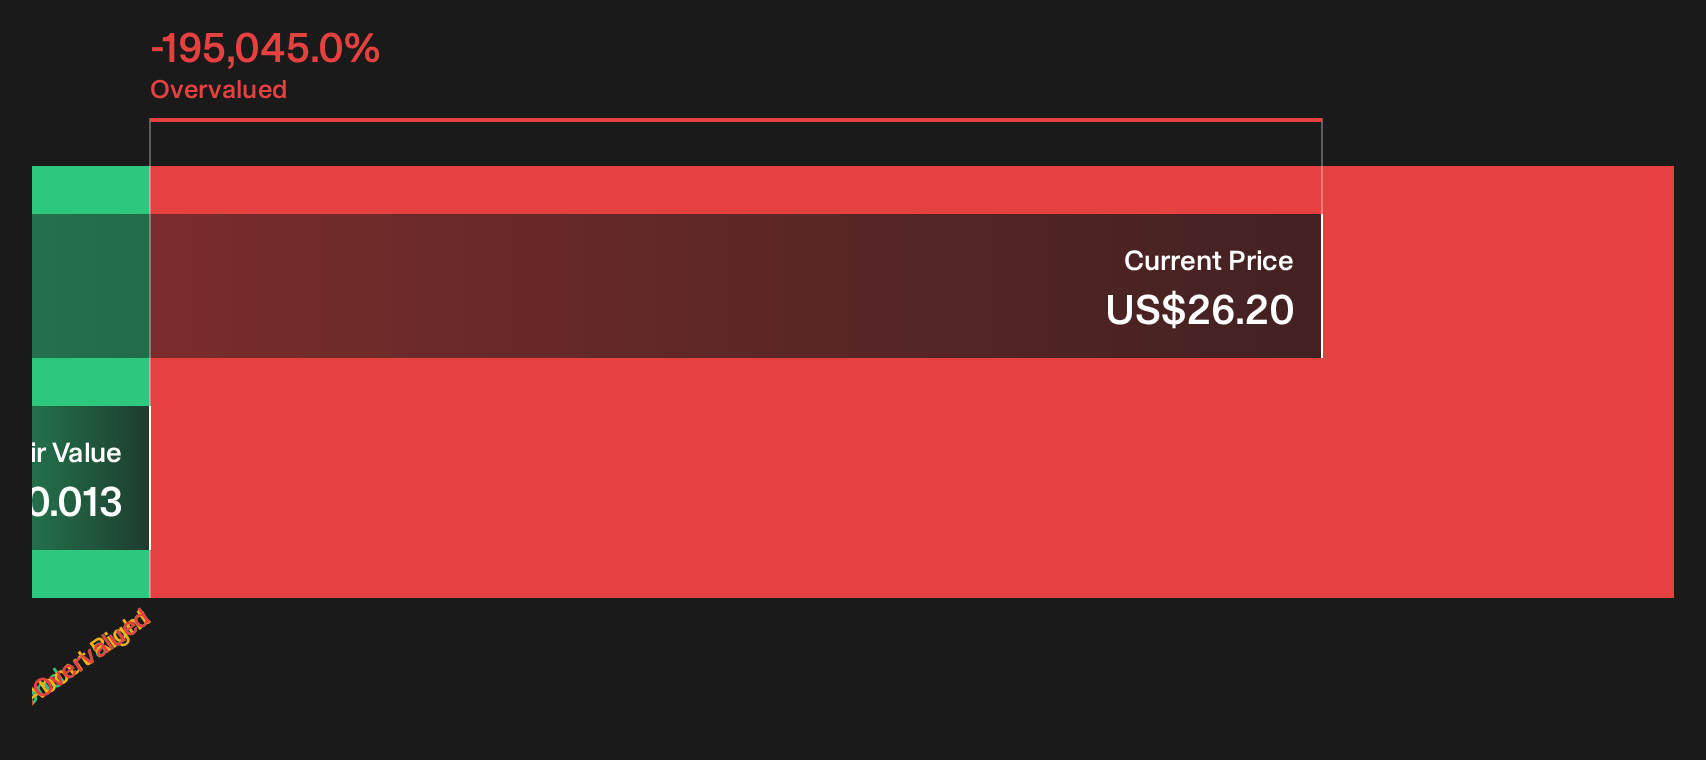
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Bitmine Immersion Technologies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Bitmine Immersion Technologies can feel confusing. Move quickly, review the numbers for yourself, and weigh both the upside and the red flags in 1 key reward and 3 important warning signs
Want More Ideas Beyond Bitmine Immersion Technologies?
Do not stop your research with Bitmine Immersion Technologies. Broaden your watchlist now so you are not scrambling later when prices have already moved.
- Target potential mispricing by scanning companies that combine quality fundamentals with valuation support through the 27 high quality undervalued stocks.
- Strengthen your income focus by reviewing companies with robust payout profiles using the 8 dividend fortresses.
- Prioritise resilience by checking companies that score well on balance sheet strength and fundamentals in the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com