


Ralph Lauren has delivered a powerful share price story in recent years, so the live question is whether the current US$368.67 price still lines up with the cash the business is expected to generate. With the focus squarely on its cash flows, investors are asking if the recent gains leave enough value supported by the Discounted Cash Flow (DCF) view.
- Ralph Lauren has returned 253.2% over the past 5 years, which puts a lot of weight on whether its future cash flows can sustain that kind of re-rating.
- The group’s brand strength and premium positioning can support pricing power and cash-flow durability, which matters for how long its current earnings can underpin value.
- If you'd rather focus on earnings, this one's for you. See why Ralph Lauren's 22.3x P/E tells a different valuation story.
For investors, the debate is whether Ralph Lauren’s present share price is adequately explained by the cash flows that the Discounted Cash Flow (DCF) intrinsic value is built on.
If you are questioning whether Ralph Lauren’s cash flows justify its current share price, it can help to compare that same valuation lens across 27 high quality undervalued stocks.
Where Does Ralph Lauren Sit on Cash Flow?
The Discounted Cash Flow (DCF) approach here focuses on Ralph Lauren’s ability to keep turning brand strength into hard cash over time. Over the last twelve months the group generated roughly $1.02b of free cash flow, which gives the model a solid starting base rather than a turnaround story built on hopes of future improvement.
Analysts feeding into this DCF assume Ralph Lauren’s free cash flow continues growing from that level, then tapers into more moderate expansion in the following years, which is consistent with a business already operating at scale. Because the projections keep free cash flow in positive territory and growing rather than shrinking, the discounted values in the model end up broadly aligned with the current $368.67 share price. For anyone holding the stock or considering fresh research, the key question is whether Ralph Lauren can keep defending that cash generation profile long enough to justify what the DCF suggests the business is worth today. Find out what Ralph Lauren could be worth using our Discounted Cash Flow (DCF) estimate.
The Ralph Lauren Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the DCF puzzle leaves off for Ralph Lauren by spelling out which paths for revenue, margins and earnings would need to hold for the current valuation to look meaningfully high or low. Rather than leaning on a single multiple or one model output, each narrative lays out the key drivers behind its fair value view so you can track those assumptions against Ralph Lauren's reported numbers over time.
Community views on Ralph Lauren’s valuation are split between those who see more upside in the brand’s cash generation and those who think rich expectations already do much of the work.
Bull case: 17% undervalued
"Early stage momentum in high potential categories such as women’s apparel, outerwear and handbags, which are growing at more than 20%…"
Discover why this Narrative puts Ralph Lauren at 17% undervalued.
Bear case: 9% overvalued
"Despite raised guidance supported by strong recent quarters and a solid balance sheet, external research flagging the shares as more than 40% above some intrinsic value estimates…"
Explore why this Narrative puts Ralph Lauren at 9% overvalued.
One more Ralph Lauren puzzle that the valuation does not answer
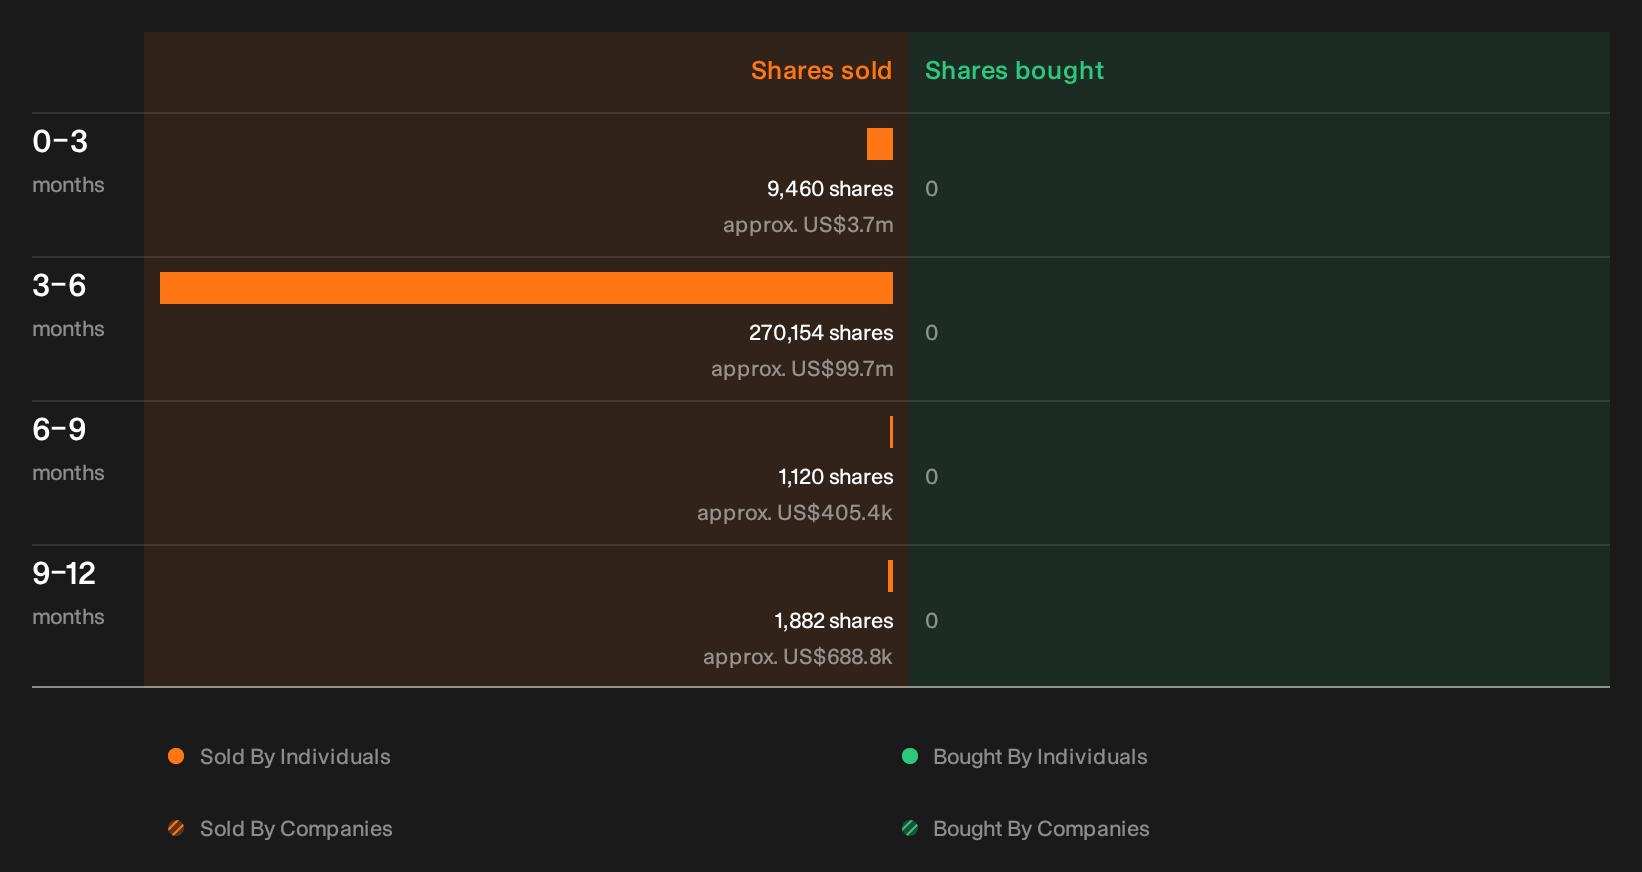
Cash flows and market pricing only tell part of the Ralph Lauren story, because recent insider share sales flagged by our checks raise a separate line of questions that you need to review for yourself. See the recent insider selling flagged for Ralph Lauren.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com