


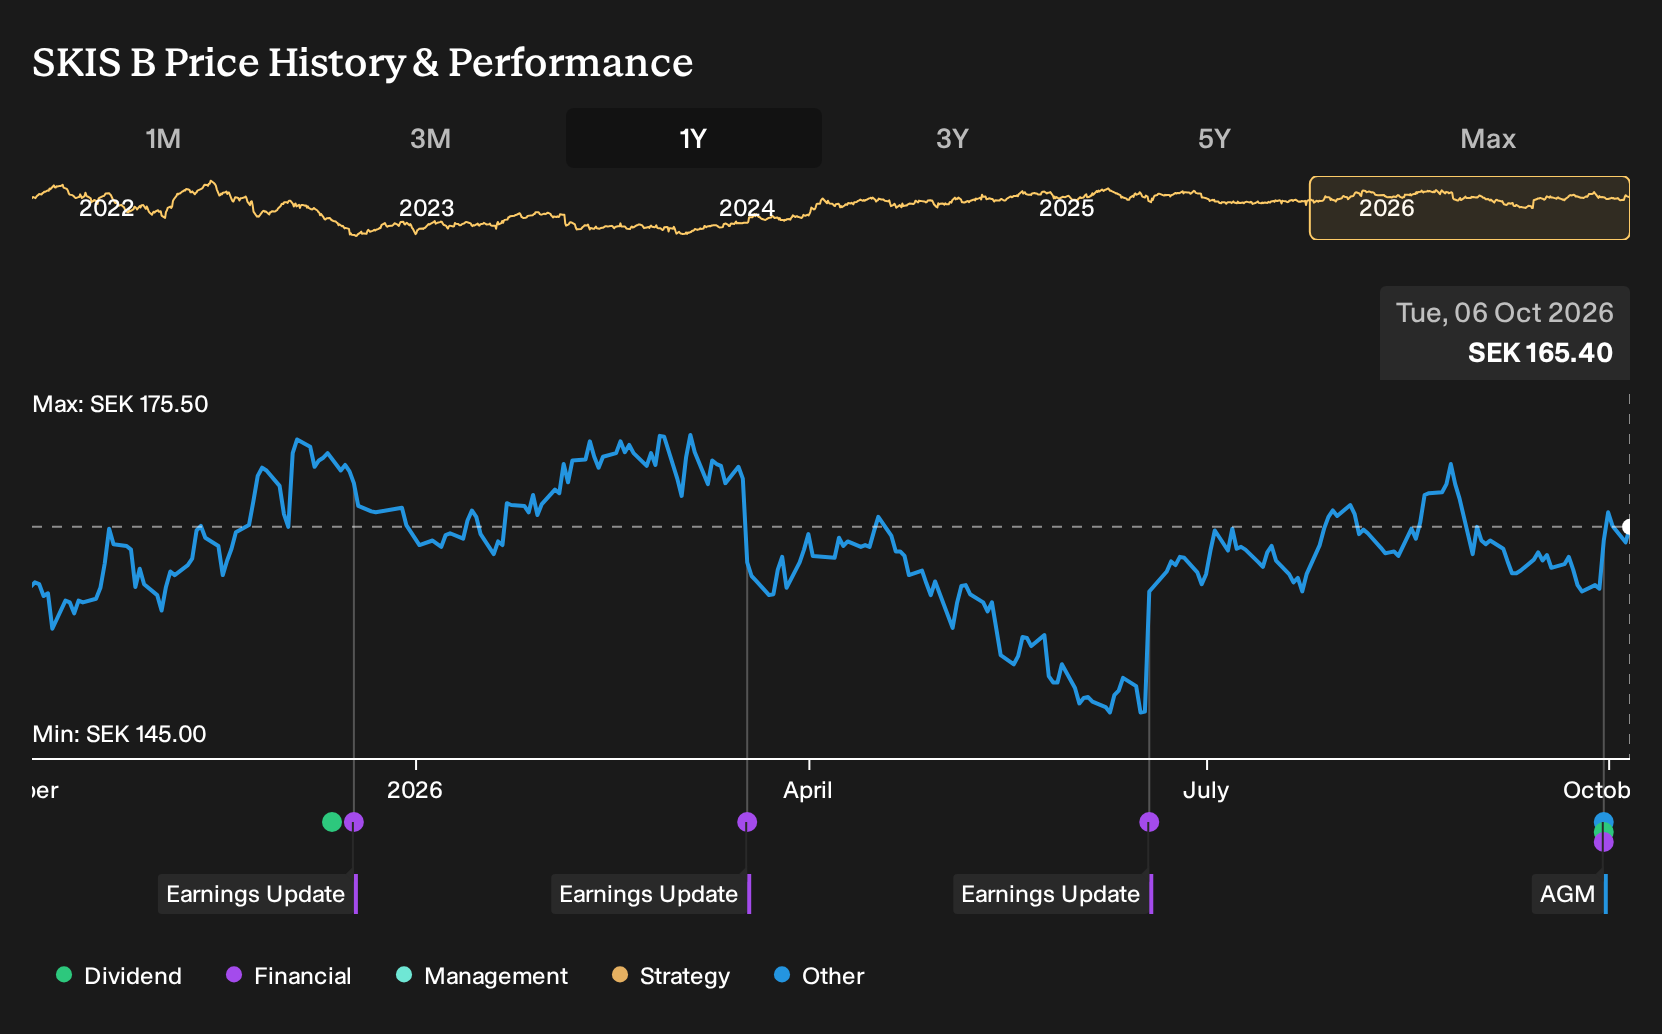
- SkiStar reported full year 2025/26 sales of SEK 4,954 million and net income of SEK 627 million, alongside a proposed dividend of SEK 3.50 per share, equal to 44% of profit after tax.
- The higher payout ratio and larger dividend pool indicate management confidence in SkiStar’s cash generation, despite a fourth quarter that still showed a net loss.
- We will now look at how SkiStar's higher proposed dividend shapes its existing investment narrative built around infrastructure and growth.
See how SkiStar’s higher payout compares with other cash-generating opportunities by exploring our hand picked list of 168 dividend fortresses for fresh dividend ideas.
SkiStar Investment Narrative Recap
To own SkiStar, you need to believe that its mountain resorts, hotels and property activities can keep filling beds and lifts despite weather, booking and retail swings. The latest full year figures show SEK 4,954 million in sales and SEK 627 million in profit, so the business is still generating cash. The key short term swing factor remains season quality and booking momentum. Weather, Easter timing and digital conversion trends still sit at the front of the risk list.
The proposed dividend of SEK 3.50 per share suggests SkiStar is comfortable returning more cash while funding its resort and accommodation projects. That payout alone does not change the main near term catalyst, which is how upcoming seasons convert into occupancy and ancillary spending. It also does not remove the core risk that heavy capital spending and higher cost seasons could squeeze returns if conditions disappoint.
The most relevant update here is the full year 2025/26 earnings report. SkiStar reported SEK 4,978 million in revenue and SEK 627 million in net income, while the fourth quarter still produced a net loss of SEK 225 million. This reflects a pattern common for ski operators, where strong winters and peak periods have to offset weaker quarters and heavy fixed costs.
For investors watching catalysts, this earnings print ties directly to questions about capital intensity and weather exposure. The resort portfolio, hotel operations and retail activities all depend on getting enough high margin days across the year to justify ongoing lift, bed and snowmaking investment. If conditions stay challenging or booking patterns weaken, the seasonal loss pattern in quarters like Q4 can become more of a concern than the higher dividend headline.
SkiStar's current analyst narrative points to SEK 5.6 billion in revenue and SEK 847.1 million in earnings by 2029, based on forecast annual top line growth of 3.8%. That outlook implies an earnings increase of about SEK 256 million from SEK 590.6 million today.
Uncover why SkiStar's fair value indicates a 16% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community has produced 2 fair value estimates for SkiStar, spanning roughly SEK 192 to SEK 231 per share, which shows how far opinions can stretch even before the latest dividend proposal and earnings release. When you set that against weather risk, heavy resort investment and shifting digital bookings, you get very different performance stories. Explore those alternative viewpoints to stress test your own stance.
Explore another SkiStar fair value estimate, including one that suggests potential upside of up to 40% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your SkiStar research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for SkiStar. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SkiStar's overall financial health at a glance.
Looking For More Ideas Beyond SkiStar?
If the SkiStar story has you thinking about portfolio balance and new opportunities, it can help to widen the lens and compare it with other businesses that share some of the same financial traits. The Simply Wall St Screener lets you filter for different profiles so you can match fresh ideas to your own risk, income and quality preferences.
- For investors who care most about resilient balance sheets and steady fundamentals, start with a list of solid balance sheet and fundamentals (206 results) that can handle tougher conditions.
- If lower volatility matters more to you than chasing every rally, consider reviewing a 228 resilient stocks with low risk scores that screens for relatively resilient returns.
- For those hunting for under-followed stories with cleaner financial profiles, broaden your watchlist with a 617 high quality undiscovered gems that might not yet be on the broader market's radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com