


- Kraft Heinz, through its Kraft Mac & Cheese brand, has introduced Cheesy Ramen, extending its familiar cheese flavor into the ramen aisle with a national rollout planned for early 2027.
- The move into ramen highlights Kraft Heinz leaning on its core brand equity to test new meal occasions while earnings expectations remain in focus.
- We will now explore how Kraft Heinz's earnings momentum and its Cheesy Ramen launch could influence the broader investment narrative.
Scan beyond Kraft Heinz and explore this ramen push by reviewing hand picked packaged food peers in the list of solid balance sheet and fundamentals (25 results) that may handle product expansion and earnings pressure in a similar way.
Kraft Heinz Investment Narrative Recap
To own Kraft Heinz, you need to be comfortable with a packaged food group that is still working through flat organic sales and unprofitable recent results while leaning heavily on brand strength and cost savings. The big near term swing factor is whether heavier marketing and product refreshes can stabilize volumes without eroding margins funded by productivity programs.
The biggest risk right now sits around revenue pressure in core North America retail and any hit to brand equity, especially as GLP 1 usage could weigh on consumption in key categories. The Cheesy Ramen launch looks incremental rather than a material shift to that near term earnings and volume picture.
The clearest link between the Cheesy Ramen news and the broader Kraft Heinz story is its recent pattern of earnings surprises versus consensus. Management has outperformed expectations in the last two quarters, which keeps attention squarely on execution in upcoming results as new product platforms roll out and marketing spend steps higher.
If earnings momentum holds while organic net sales guidance for 2026 remains under pressure, investors will likely focus on how launches like Cheesy Ramen support volume led growth and protect brand relevance. Any stumble on cost savings, or weaker than expected contribution from these extensions, would quickly refocus attention on debt levels, dividend coverage, and the risk of further pressure on returns.
Kraft Heinz's narrative projects US$25.2b revenue and US$2.9b earnings by 2029. This implies broadly flat revenue over the next few years and an earnings swing of about US$6.3b, from a loss of US$3.4b today to the US$2.9b forecast level.
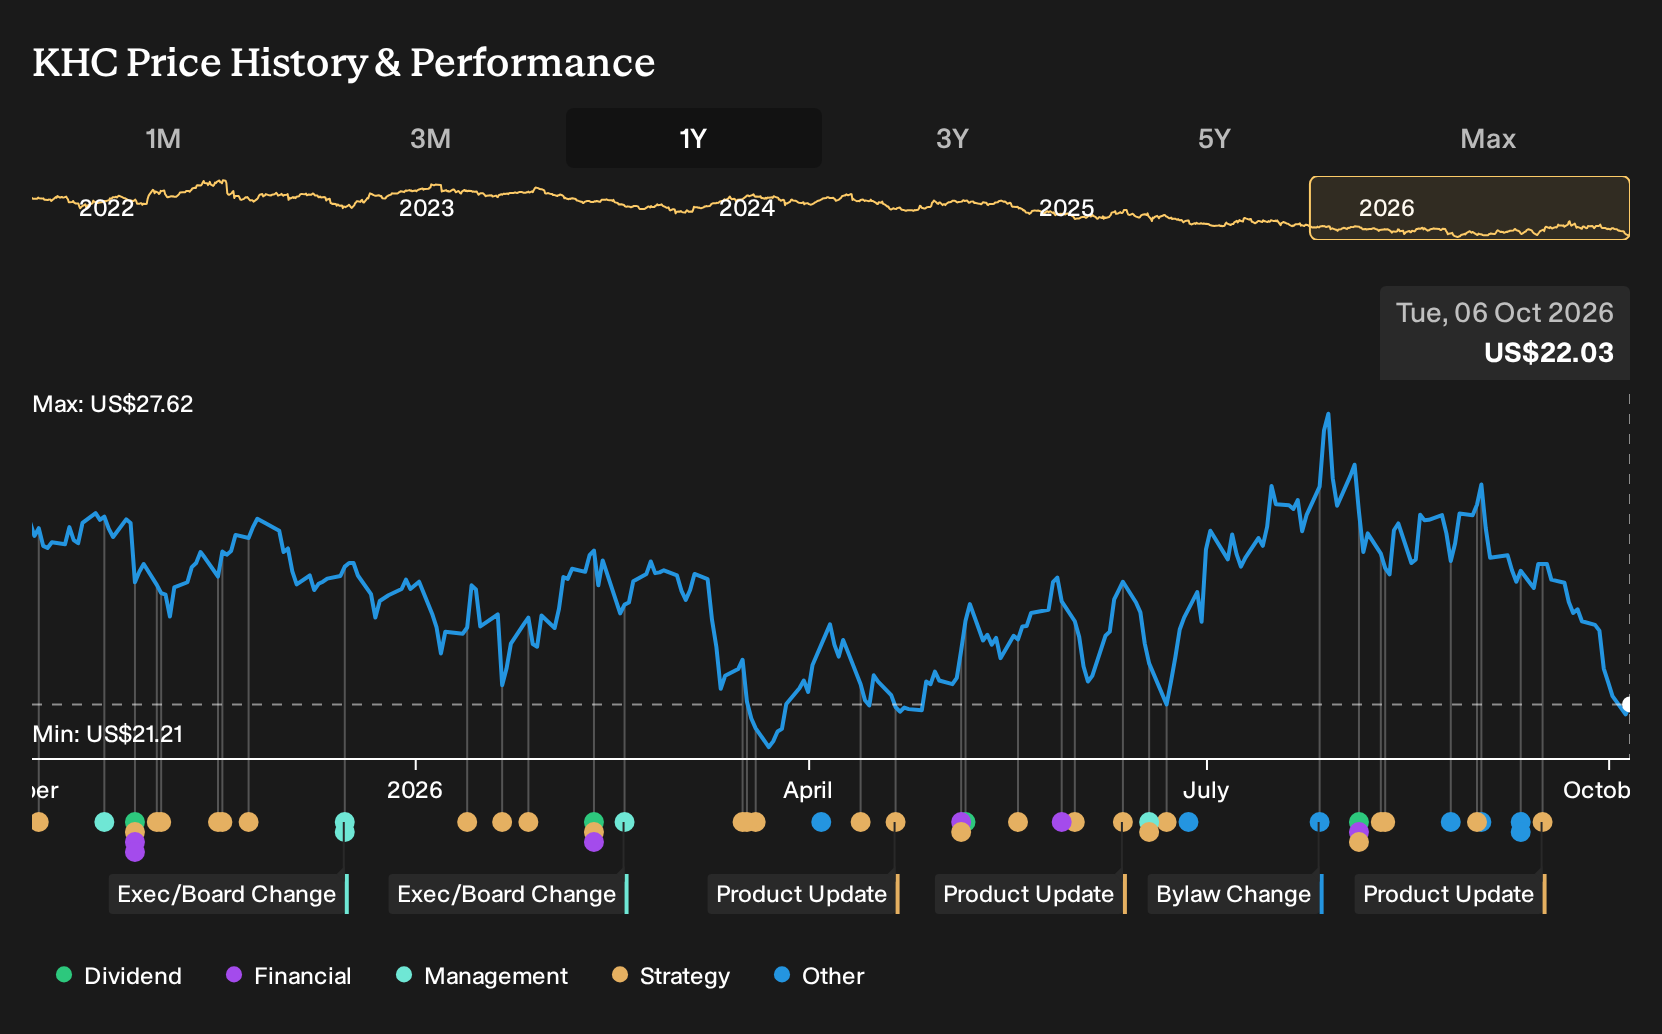
Uncover why Kraft Heinz's fair value indicates a 16% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the lowest ranked analysts see Kraft Heinz through a much harsher GLP 1 lens, worrying that appetite suppressing drugs could mute demand for products like Cheesy Ramen. Before this news, they were penciling in about US$24.9b revenue and US$2.6b earnings for 2029. Use this spread to explore how your own expectations might differ.
Explore 10 other Kraft Heinz fair value estimates, including one that suggests as much as 14% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Kraft Heinz research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Kraft Heinz. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kraft Heinz's overall financial health at a glance.
Looking For More Investment Ideas Beyond Kraft Heinz?
If the Kraft Heinz story has sharpened your thinking on earnings quality and brand resilience, you can use that same lens to scan a wider universe of opportunities with the Simply Wall St Screener.
- For investors who want quality at a sensible entry point, review a curated set of companies trading below their assessed value in the 27 high quality undervalued stocks.
- If capital preservation and balance sheet strength matter most to you, focus on businesses with healthier finances using the 31 resilient stocks with low risk scores.
- For readers hunting for less crowded ideas, scan financially robust smaller players that receive less attention in the 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com