


Redwire (RDW) just picked up fresh work from Axiom Space, extending its Roll-Out Solar Array technology to the second Axiom Station module and reinforcing its role in commercial low Earth orbit infrastructure.
Recent contracts with Axiom Space, Honda and U.S. Space Force have arrived as Redwire’s 17.61% year to date share price return contrasts with a 3.19% decline in total shareholder return over the past year, while the very large 3 year total shareholder return suggests earlier buyers have already seen substantial swings in sentiment.
Scan other space infrastructure and defense contractors showing similar contract momentum with curated lists such as 87 robotics and automation stocks to see how Redwire’s latest win compares across the sector.
Redwire trades at a clear discount to both analyst targets and some intrinsic estimates after a sharp year to date rebound. Is that a pricing mistake, or a fair warning label on a loss-making space contractor?
Most Popular Narrative: 17% Undervalued
Against a last close of $10.62, the most followed narrative on Redwire pegs fair value at $12.82, implying a clear valuation gap that hinges on how contract wins and new platforms translate into cash generation.
The pipeline of roughly US$10 billion of identified opportunities, with US$3 billion of proposals submitted year to date and a Q3 2025 book to bill ratio of 1.25x that lifted backlog to US$355.6 million, suggests that converting even a portion of this funnel could support revenue visibility and a path toward positive adjusted EBITDA and cash from operations.
See why 36 investors see Redwire as 17% undervalued.
Result: Fair Value of $12.82 (UNDERVALUED)
Still, Redwire’s reliance on U.S. government programs and ongoing adjusted EBITDA losses, along with potential equity dilution, could quickly flip this undervaluation story on its head.
Find out about the key risks to this Redwire narrative.
Another View On Redwire’s Valuation
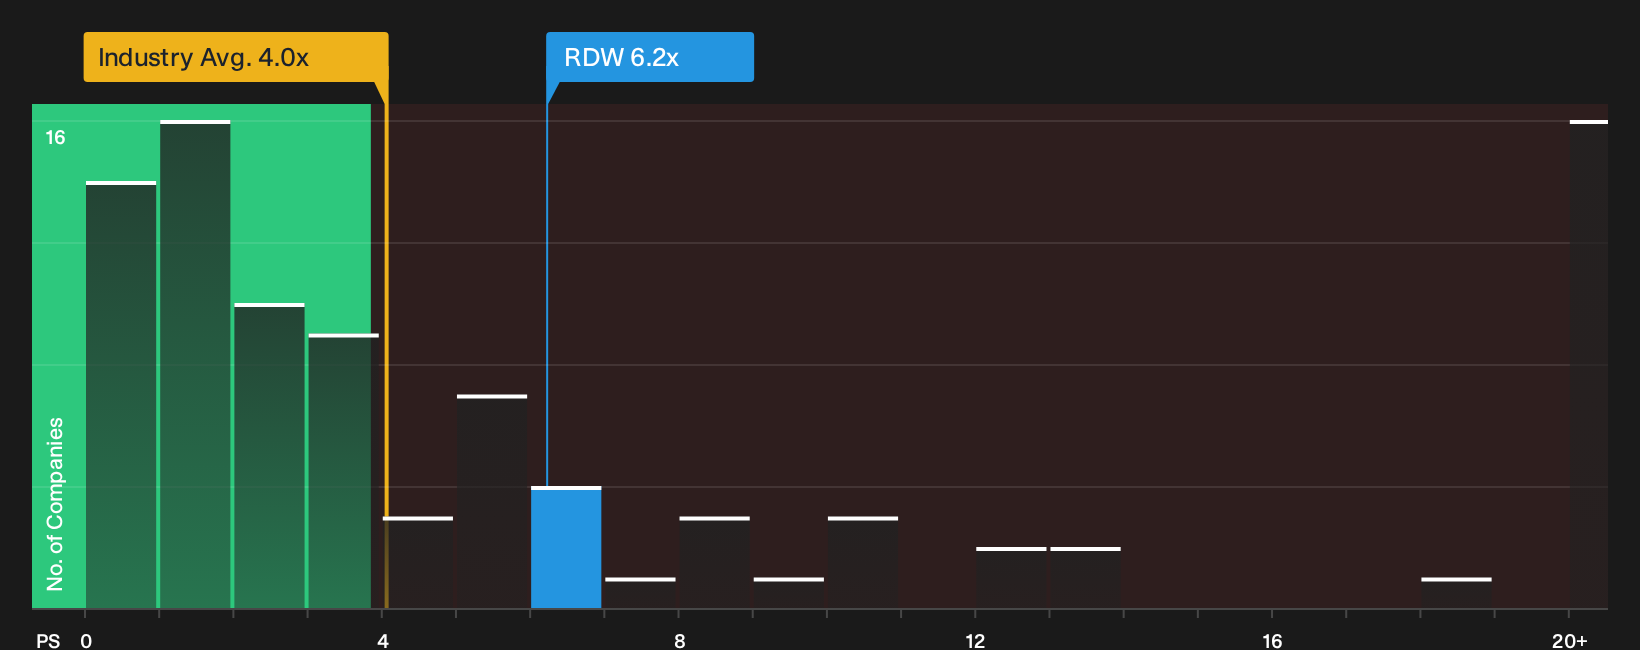
Switch the lens from cash flows to sales multiples and the picture turns less comfortable. Redwire trades on a P/S ratio of 6.2x compared with 4x for the US Aerospace & Defense group, a 2x peer average and a fair ratio of 2.7x that the market could drift toward over time.
If sentiment cools, that kind of premium can unwind quickly or compress more slowly as revenue catches up. The question for investors is whether the contract pipeline and growth expectations justify paying such a marked step up today.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Redwire’s valuation story are clear. Move fast on your own homework, weigh the contract wins against the red flags, then test your thesis against the 2 key rewards and 3 important warning signs
Looking for more Redwire-sized ideas?
Do not stop with Redwire. Use targeted stock lists to hunt for fresh ideas that fit your risk level, income goals and balance sheet preferences.
- Target higher upside potential by scanning the 19 high quality undiscovered gems that may not yet be crowded with institutional money.
- Build a steadier core by reviewing a list of solid balance sheet and fundamentals (25 results) that can help anchor a more conservative portfolio.
- Reduce portfolio stress by focusing on a 31 resilient stocks with low risk scores that filters for companies with stronger risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com