


FDA clearance puts Immunome’s IM-1340 program in focus
Immunome (IMNM) moved into the spotlight after the FDA cleared its IND application for IM-1340, an antibody-drug conjugate aimed at advanced solid tumors that has shown encouraging preclinical anti-tumor activity.
Short term momentum for Immunome has cooled, with the share price falling 8.8% over the last day, 11.8% over the past week and 27.8% over the past month. However, the 1 year total shareholder return of 39.7% and 3 year total shareholder return of about 1.5x suggest longer term holders have still seen strong gains.
Spot opportunities around Immunome’s news by scanning a curated list of oncology and biotech peers through the 34 healthcare AI stocks.Immunome now trades well below the average analyst target and a more modest intrinsic estimate, after a sharp pullback. Is the market correctly resetting expectations, or overshooting fair value on the IM-1340 news reset?
Most Popular Narrative: 47% Undervalued
Against Immunome’s last close of $19.31, the most followed narrative points to a fair value near $36.31, which frames today’s pullback as a sharp discount grounded in long term pipeline expectations rather than short term trading momentum.
The move from a single lead asset to a broader Immunome oncology platform, with IM-1021, IM-1617 and IM-3050 already in Phase 1 and two additional solid tumor ADC INDs planned for 2026, increases the number of shots on goal that could support multi-asset revenue streams and help spread fixed costs over a larger base, which may benefit margins over time.
See why 1 investors see Immunome as 47% undervalued.
Result: Fair Value of $36.31 (UNDERVALUED)
Still, the bullish Immunome narrative runs into real hurdles if regulators push back on varegacestat or if desmoid specialists adopt the oral therapy more slowly than hoped.
Find out about the key risks to this Immunome narrative.
Another view on Immunome’s valuation
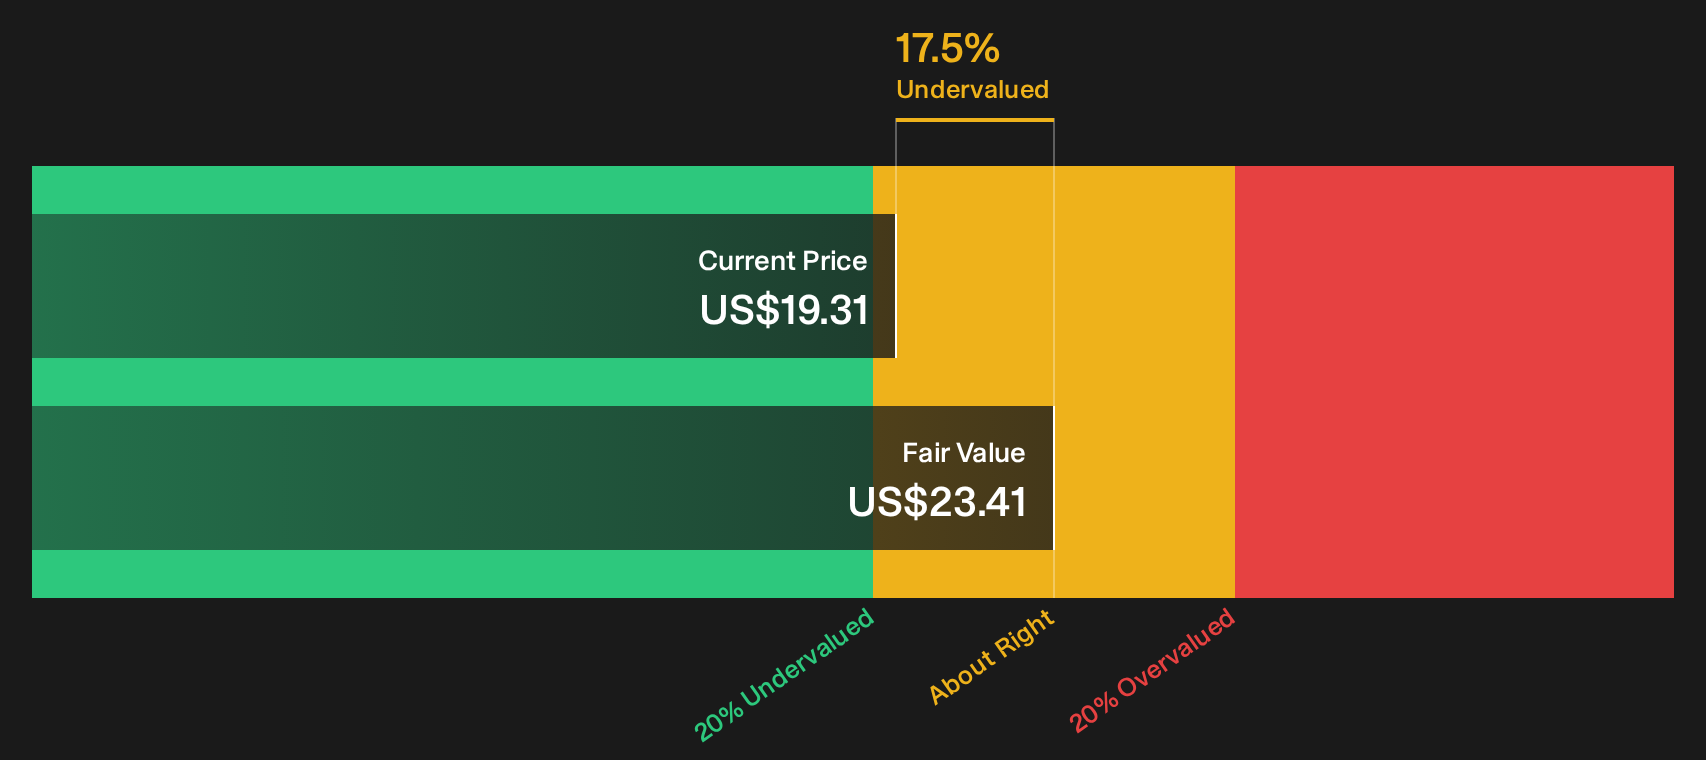
The first fair value story around Immunome leans heavily on analyst targets and long term earnings assumptions. A simple reality check comes from the SWS DCF model, which places future cash flow value at about $23.41 per share versus today’s $19.31, suggesting a smaller undervaluation. Which lens do you find more convincing?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on Immunome so far, right? Move quickly from headline takes to your own judgment by weighing the 3 key rewards and 3 important warning signs.
Hunting for more ideas beyond Immunome?
Do not stop your research with Immunome. Broaden your watchlist with fresh ideas that match different goals, risk levels and income needs using the Simply Wall Street Screener.
- Target potential mispricings across sectors by running through a focused set of 27 high quality undervalued stocks that pair quality fundamentals with attractive entry points.
- Strengthen the income side of your portfolio by reviewing a shortlist of 8 dividend fortresses that aim to combine yield with resilience.
- Dial down overall risk by scanning a curated pool of 31 resilient stocks with low risk scores that score well on balance sheet strength and volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com