


QCR Holdings (QCRH) drew fresh attention after its recent share move, with the price closing at US$99.02. Investors are weighing this regional bank's valuation in relation to its performance over the past year.
QCR Holdings has delivered shareholders a weaker 1‑month share price return, down 3.57%, although the year‑to‑date share price gain of 20.55% and 1‑year total shareholder return of 32.18% indicate momentum that has built over a longer period.
Compare QCR Holdings' recent run with a curated group of regional banks and financials in the 27 high quality undervalued stocks that share solid fundamentals and potential valuation gaps.
QCR Holdings now trades at a double discount: about 12% below the average analyst price target and roughly one third under an estimated intrinsic value. Is that caution well earned, or has the market mispriced this bank?
Price-to-Earnings of 11.4x: Is it justified?
On a simple earnings yardstick, QCR Holdings trades on a P/E of 11.4x, which lines up closely with the wider US banks group yet still suggests a modest valuation edge versus closer peers.
The P/E ratio compares the current share price with earnings per share and gives a quick sense of how much investors pay for each dollar of profit. For a regional lender like QCR Holdings, where earnings quality and growth can be just as important as balance sheet size, this measure helps frame what the market is currently willing to pay for its profitability.
Earnings grew 25.9% over the past year and have risen by 8% per year over the past 5 years, and the business is described as having high quality earnings. Against that backdrop, paying 11.4x earnings versus a fair P/E estimate of 10.6x implies investors might be building in a premium for that profit track record. At the same time, the model suggests a level that the market could move towards that is slightly lower than today.
Relative to the broader US Banks industry average of 11.5x, QCR Holdings trades almost in line, which points to the stock being priced broadly similarly to the sector rather than at a steep discount or a rich premium.
Explore the SWS fair ratio for QCR Holdings.
Result: Price-to-Earnings of 11.4x (ABOUT RIGHT)
Still, QCR Holdings faces meaningful risks if credit quality weakens or funding costs rise, which could pressure earnings and challenge the current valuation case.
Find out about the key risks to this QCR Holdings narrative.
Another View on QCR Holdings' Value
The SWS DCF model gives a different angle on QCR Holdings. On this view, the shares at $99.02 trade below an estimated future cash flow value of $147.60. That gap suggests the market might be underrating the durability of cash generation, or the model could be too optimistic. Which side are you on?
Look into how the SWS DCF model arrives at its fair value.
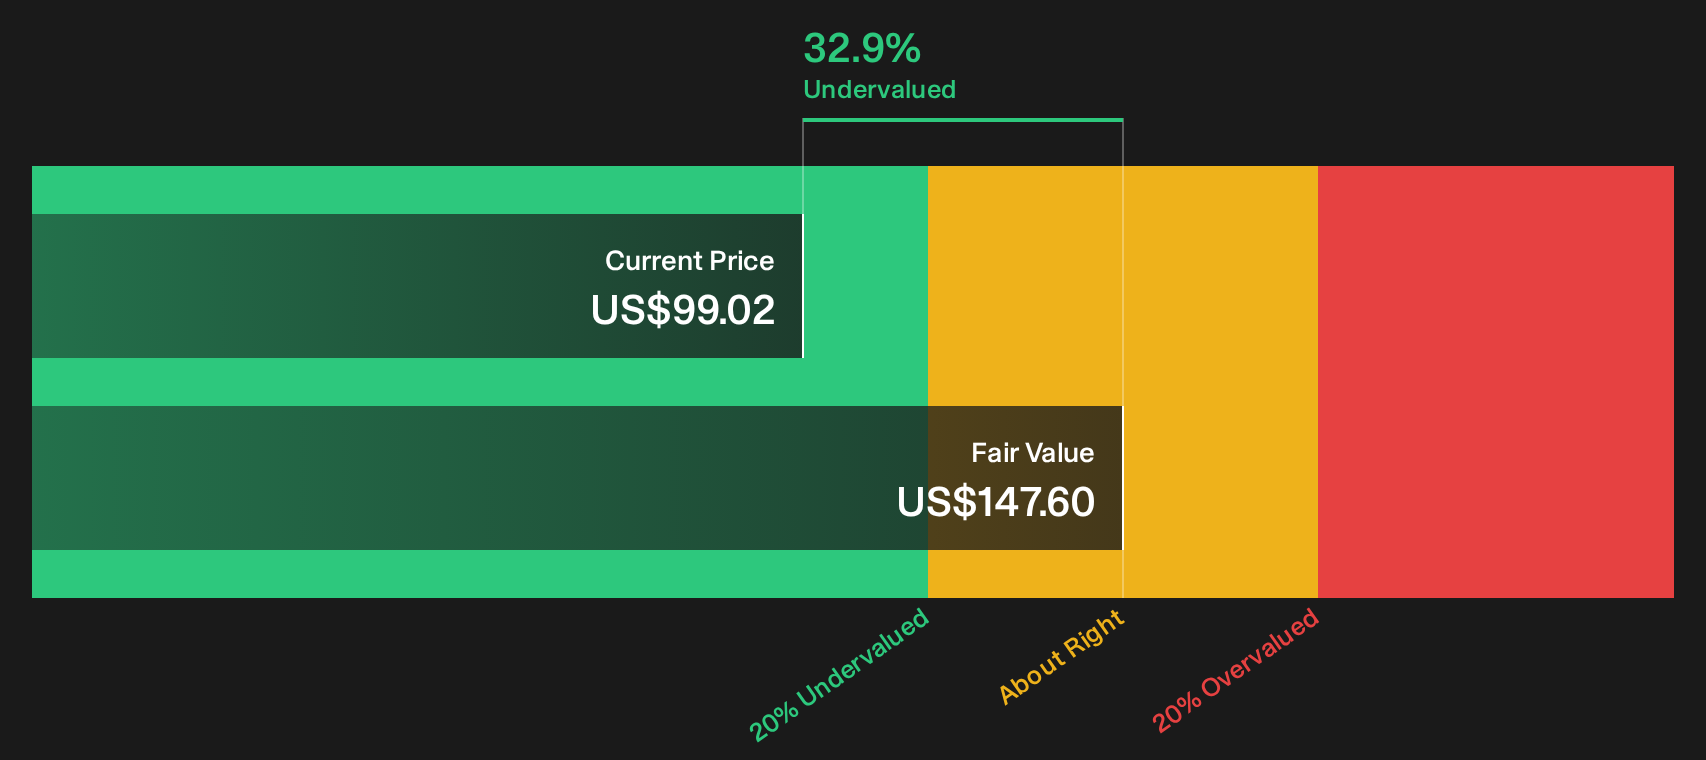
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out QCR Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling that QCR Holdings might be getting a mixed verdict here and want your own take before sentiment shifts again? Review the optimism already reflected in the 2 key rewards
Looking for more investment ideas beyond QCR Holdings?
If QCR Holdings has sharpened your focus on value and quality, do not stop here. Broader ideas can help you stress test your thinking and find fresh opportunities.
- Target stronger balance sheets by scanning companies in the list of solid balance sheet and fundamentals (25 results) that combine resilient finances with room for the story to develop.
- Hunt for mispriced quality and review the 27 high quality undervalued stocks so you do not miss businesses trading below what their fundamentals suggest.
- Spot potential early movers by checking the 19 high quality undiscovered gems before more investors pay closer attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com