


Rising UK gilt yields have pushed bond income back into focus, but many investors still want payouts that can grow faster than inflation over time. That is where established British dividend payers offering yields above 3% with solid coverage and consistent growth records can look appealing. This article highlights three such high income stocks from our quality filter and explains what makes each one worth a closer look today.
The three dividend payers below are just a small sample. The full Dividend Powerhouses filter surfaced another 60 income stocks with covered, growing payouts and equally interesting stories that are not unpacked here.
If you want to identify which of those might deserve a place on your watchlist, head straight to the Dividend Powerhouses (3%+ Yield) screener to analyze yields, payout strength, and dividend consistency side by side.
MONY Group (LSE:MONY)
MONY Group is a familiar brand for many UK households, and for income investors its MoneySuperMarket insurance comparison arm is the key attraction. It feeds steady fee income that helps support the high yield and puts digital execution firmly in the spotlight.
"The ongoing investment in digital and AI-enabled platforms is increasing automation and operational efficiency, evidenced by a 300% improvement in tech productivity and cost reductions from replatforming, which is likely to support sustainable long-term expansion of net margins."
What matters next is how one subtle shift in customer acquisition costs ripples through those margins and, by extension, payout resilience.
Those payout shock absorbers only matter if you can see the full engine. Read the full narrative for MONY Group to see where MONY Group’s income story could be accelerating next.

Lloyds Banking Group (LSE:LLOY)
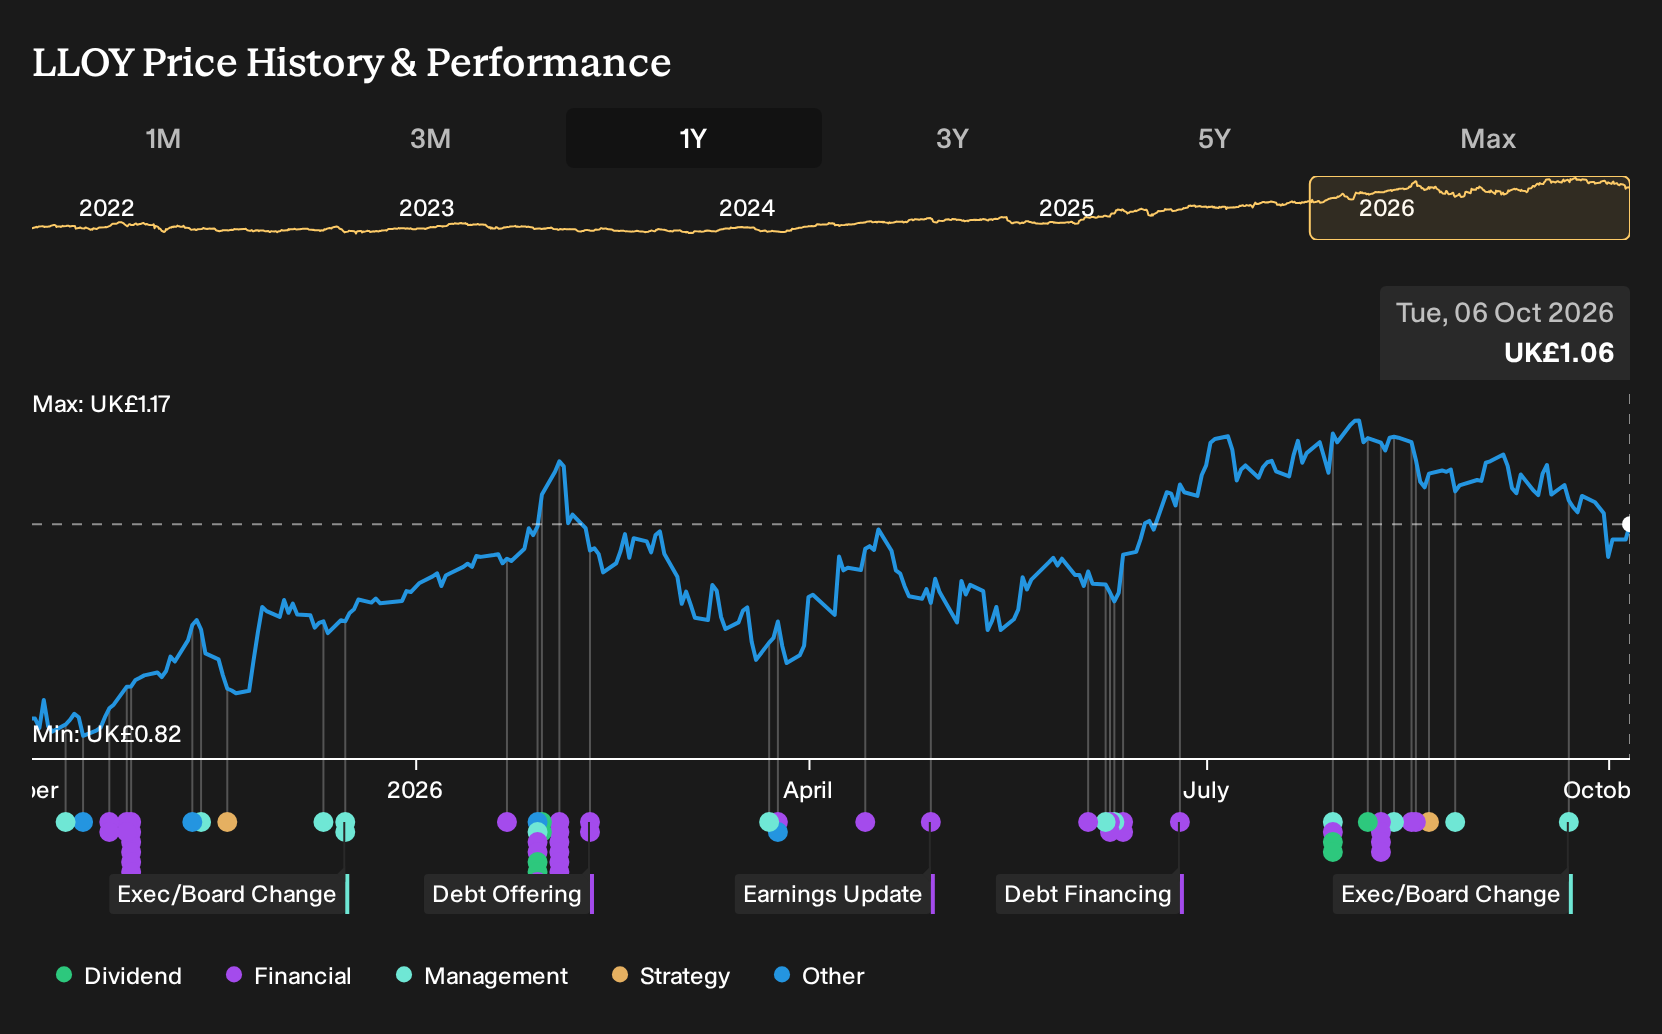
Lloyds Banking Group is best known for everyday banking in the UK, with its high street mortgage and deposit franchises helping to support the covered, 3%+ yield profile that income investors look for in this Dividend Powerhouses screen.
Lloyds Banking Group runs a broad UK banking and financial services operation, with Retail, including wealth, generating about £11.9b of revenue, Commercial Banking around £5.7b, and Insurance, Pensions and Investments roughly £1.4b. This gives the £60.6b group a large, income-focused footprint.
"Digital transformation and AI adoption are reducing costs and driving efficiency, supporting margin expansion and improved earnings quality."
What really matters now is how one unseen pressure on credit quality plays out and feeds through to future dividend headroom.
That pressure point on credit quality is where things get interesting, and the full narrative for Lloyds Banking Group shows how Lloyds Banking Group's income story could be accelerating beyond headline margins.
Foresight Group Holdings (LSE:FSG)
Foresight Group Holdings manages income-focused infrastructure and private equity funds, channeling investor capital into real assets that can support regular dividends. Real Assets contribute about £114.8 million of revenue, with Private Equity adding £50.1 million, and the group is valued at roughly £492.1 million.
For income investors, Foresight Group Holdings links the 3%+ yield theme directly to real world assets, since many of its funds own renewable energy and storage projects that pay out steady cash distributions, while the manager collects fees on those long term contracts.
"Foresight is rapidly evolving new product strategies such as standalone private credit-focused business relief, with early demand signaling the potential to become a flagship offering. The strategy aims to access sizeable, untapped wealth and institutional flows and to elevate recurring revenue growth rates as financial advisors and pension funds shift allocations for long-term yield."
The real test for that income story sits in how one shift in funding costs and leverage eventually filters through to dividend flexibility.
That funding twist is only the starting point, and the full narrative for Foresight Group Holdings explains how Foresight Group Holdings could turn shifting capital costs into accelerating, income-backed growth potential.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first, and slow research often gets caught watching breakouts from the sidelines while the early momentum drops under the radar for now. Get in early.
- Snag quality businesses when nerves run high by scanning the 4 resilient stocks with low risk scores that keep compounding quietly while others chase whatever is flying this week.
- Hunt for future winners in real-world materials as the 16 top copper producer stocks highlights producers powering grids, vehicles, and infrastructure before demand stories crowd the trade.
- Track the next wave of automation by reviewing the 87 robotics and automation stocks curated to spotlight businesses wiring factories, warehouses, and logistics for the next productivity breakout.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com