


Privia Health Group (PRVA) is back in focus after Anthem Blue Cross and Blue Shield in Virginia renewed an agreement that keeps Privia Medical Group physicians in network for Anthem members across the state.
For investors tracking Privia Health Group, the renewed Anthem agreement lands after a mixed stretch for the stock, with the share price down about 25% over 90 days and the 1-year total shareholder return declining roughly 16%. At the same time, recent quarterly results, an expanded 2026 outlook, and entry into New Jersey have started to rebuild short-term momentum, reflected in a positive 7-day share price return.
Spot potential companions to Privia Health Group’s value-based care story by scanning a curated set of healthcare and quality-focused stocks in our list of solid balance sheet and fundamentals (25 results).Privia Health Group now trades at a steep discount to both its intrinsic value estimate and analyst targets after a sharp 90 day slide. Is that caution well earned, or has the pullback gone too far?
Most Popular Narrative: 36% Undervalued
On the most followed narrative, Privia Health Group’s fair value of $31.47 sits well above the last close of $20.28. This frames today’s discount as a question of execution rather than survival risk.
Ongoing expansion of Privia Health Group’s national, primary care focused provider network, with 5,644 implemented providers across 25 states and D.C. caring for over 6.1 million patients, creates more capacity to direct patient volumes into its platform and can support future revenue growth as additional markets mature.
See why 7 investors see Privia Health Group as 36% undervalued.
Result: Fair Value of $31.47 (UNDERVALUED)
Still, Privia Health Group’s story can crack if subscale free cash flow margins persist, or if continued insider selling keeps investor confidence under pressure.
Find out about the key risks to this Privia Health Group narrative.
Another View: Privia Health Group Looks Expensive On Earnings
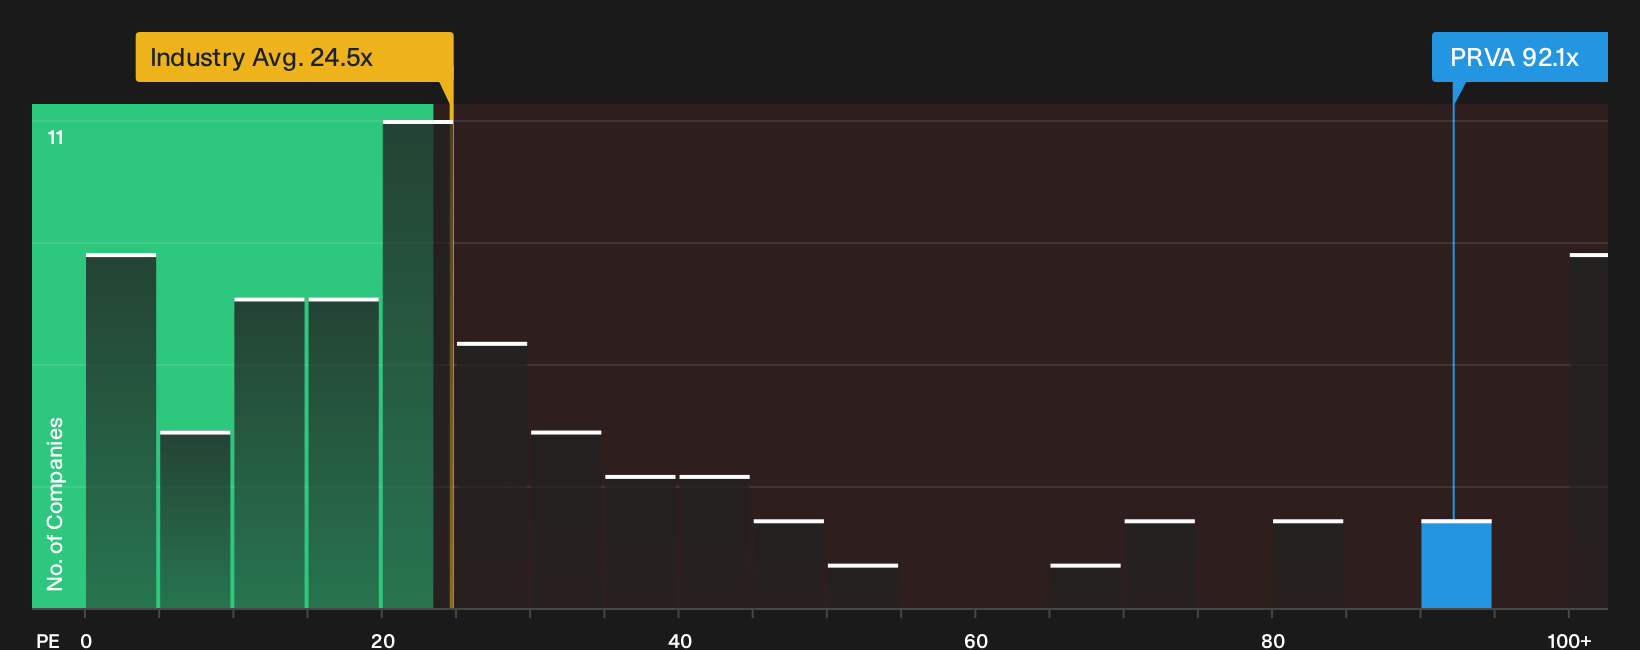
On a simple earnings yardstick, Privia Health Group screens very differently. The shares trade on a P/E of 92.1x, compared with 24.3x for the US Healthcare industry and 22.8x for close peers, while the fair ratio is 30.6x. That gap points to meaningful valuation risk if sentiment cools.
Before leaning on any one approach, pressure test the earnings based view against cash flow, capital needs, and your own expectations for how long the market will pay such a premium. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by the mixed tone around Privia Health Group and its valuation gap or premium earnings multiple? Move quickly, review the underlying drivers for yourself, and weigh them against the 4 key rewards.
Looking for more investment ideas beyond Privia Health Group?
If Privia Health Group has your attention, do not stop here. The market rewards investors who keep scanning fresh setups instead of staying anchored to one ticker.
- Target steadier compounding by reviewing a 31 resilient stocks with low risk scores that filters for resilience when conditions change faster than headlines.
- Hunt for quality at a discount by checking a 19 high quality undiscovered gems built around strong fundamentals that have not yet caught broad attention.
- Upgrade your watchlist by focusing on a 8 dividend fortresses that highlights higher yielding businesses with the potential for more reliable income streams.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com