


Alcoa (AA) has been back on investors’ radar after recent trading moves that contrast sharply with its mixed return profile, including a decline of about 24% year to date and a gain over the past year.
Alcoa’s recent pullback, including a 30 day share price return of about a 14% decline and an 11% fall over 90 days, sits awkwardly beside a 1 year total shareholder return of roughly 22%. This suggests fading short term momentum even as longer term holders remain ahead.
Spot similar materials names where recent pullbacks contrast with stronger longer term returns by scanning our hand picked 27 high quality undervalued stocks.Recent weakness now meets a longer track record of positive total returns for Alcoa. The key question is whether that points to more upside ahead or indicates that most of the easy gains are already behind it.
Most Popular Narrative: 31% Undervalued
The most followed narrative on Alcoa pegs fair value at $62.98, compared with a last close of $43.17. This frames the recent pullback as a potential gap between price and modeled fundamentals.
Decarbonization trends, supply constraints, and sustainable product innovation position Alcoa for stronger pricing, improved margins, and resilient long-term growth amid shifting global demand.
Alcoa's successful development and commercialization of its EcoLum low-carbon aluminum products and the ELYSIS zero-carbon smelting process position the company to capture premium pricing and greater market share as customers and regulators increasingly prioritize sustainability, which could sustain or expand profit margins over time.
See why 47 investors see Alcoa as 31% undervalued.
The fair value estimate in this storyline uses a 9.09% discount rate and ties that to modest modeled revenue expansion and a profit margin assumption of 14.11%. That framework also leans on a future P/E of 11.27x that sits below the current average multiple for the US Metals and Mining group referenced in the same narrative, which keeps the earnings expectations grounded in sector context.
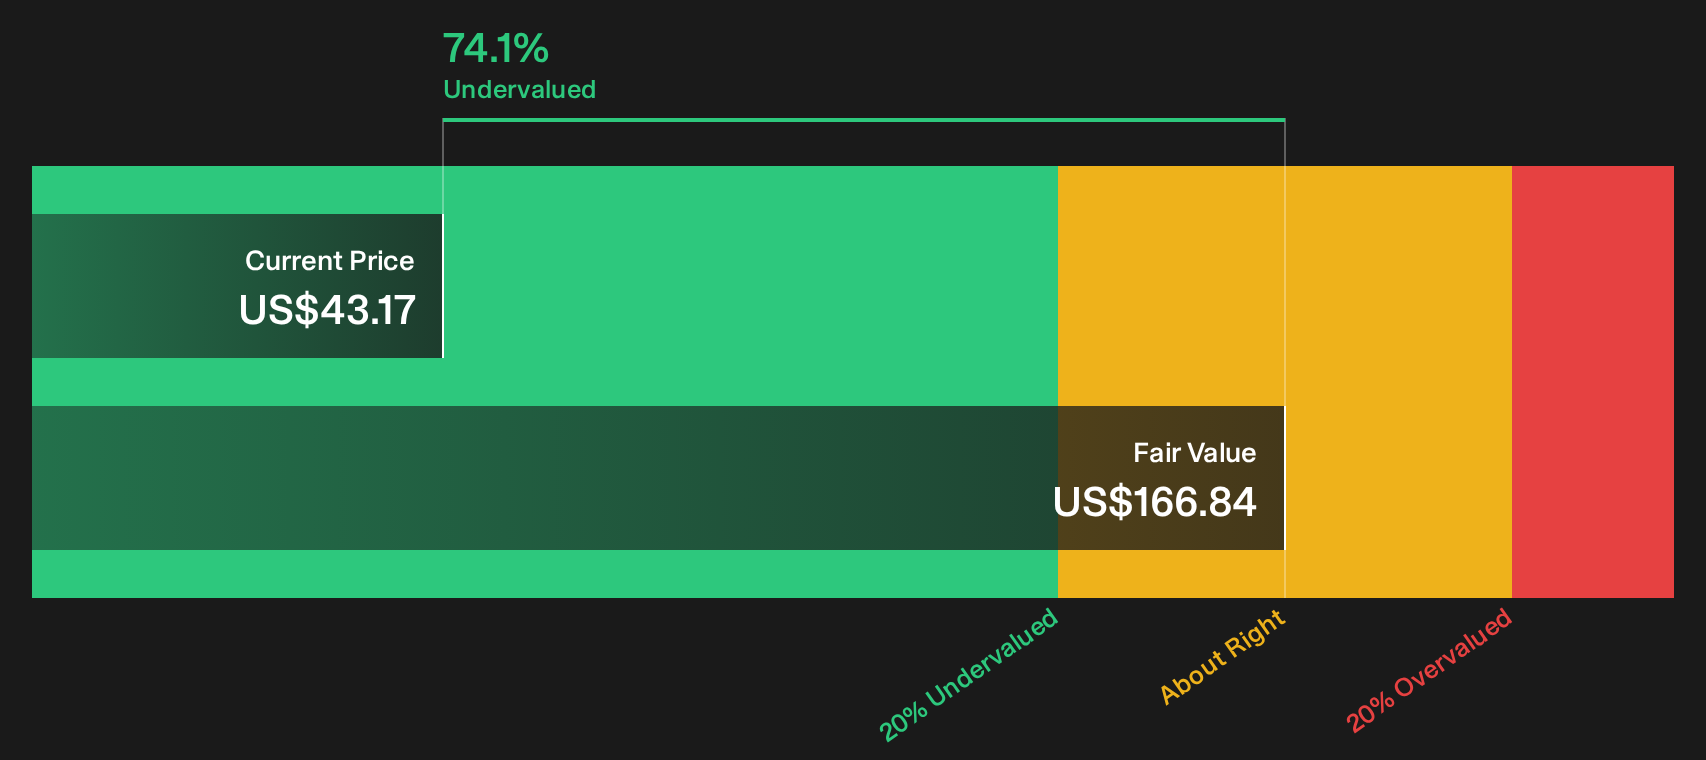
Against that backdrop, Alcoa's current market value of about $11.5b and annual revenue of $13.6b give readers a sense of scale for the cash flows that underpin this discounted cash flow style narrative. The large gap between the quoted $166.84 future cash flow value from the SWS DCF model and the $43.17 share price further underlines how sensitive outcomes can be to growth, margin, and discount rate inputs, so readers may want to stress test those assumptions for themselves.
Result: Fair Value of $62.98 (UNDERVALUED)
Still, the narrative can change if recycled aluminum and substitute materials limit long-term demand, or if tariff and regulatory costs reduce Alcoa’s profitability more than expected.
Find out about the key risks to this Alcoa narrative.
Another View On Alcoa’s Valuation
The SWS DCF model points in the same direction as the popular narrative but with a far more aggressive result. On that framework, Alcoa at $43.17 trades against a future cash flow value of $166.84, labeled undervalued. That raises a blunt question: is the gap reflecting opportunity or just very optimistic inputs?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
The mixed mood around Alcoa puts the spotlight back on you as the decision maker. Move quickly, consider both sides, and review the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Alcoa?
Do not stop with Alcoa. Use the Simply Wall St screener to surface fresh opportunities that match your risk appetite and income goals before others catch on.
- Target potential undervalued opportunities early by scanning the 27 high quality undervalued stocks that combine solid fundamentals with compressed expectations.
- Strengthen your income stream by reviewing the 8 dividend fortresses built around companies offering higher yields with supporting financials.
- Reduce portfolio stress by focusing on stability first through the 31 resilient stocks with low risk scores that highlights businesses with lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com