


Fresh attention on MasTec (MTZ) is building after recent commentary highlighted a backlog growing an average 24.9% year-on-year, along with analyst expectations for 24.8% revenue expansion over the coming year.
Recent price action around MasTec reflects that tension between a softer quarter and a strong backlog, with the share price up 4.1% over the last day and 8.6% over the week. However, the 90 day share price return is down 40.4%, while the 3 year total shareholder return is about 3.3x, suggesting that long term holders have still seen substantial gains even as near term sentiment resets around new growth expectations.
Scan infrastructure builders facing similar growth expectations by reviewing our curated list of 44 power grid technology and infrastructure stocks alongside MasTec's latest move.
MasTec now trades at a sharp distance from both its recent highs and the range of analyst estimates. Where does a fair value anchor actually look reasonable after this swing?
Most Popular Narrative: 44.8% Undervalued
MasTec's most followed valuation storyline pegs fair value around $413.40, while the last close sits at $228.30. As a result, the market is pricing in a wide gap that hinges on how the backlog and margins play out.
Rapid acceleration in utility grid modernization, data center build outs and renewable energy investment continues to support MasTec’s record backlog of about US$21.4b and raised 2026 guidance. This points to further upside potential in revenue and earnings as these projects convert.
See why 27 investors see MasTec as 45% undervalued.
Result: Fair Value of $413.40 (UNDERVALUED)
Still, MasTec’s reduced 2026 Communications outlook and the share price reaction to a single EPS guidance miss illustrate how quickly this narrative could be challenged.
Find out about the key risks to this MasTec narrative.
Another View: MasTec Through The P/E Lens
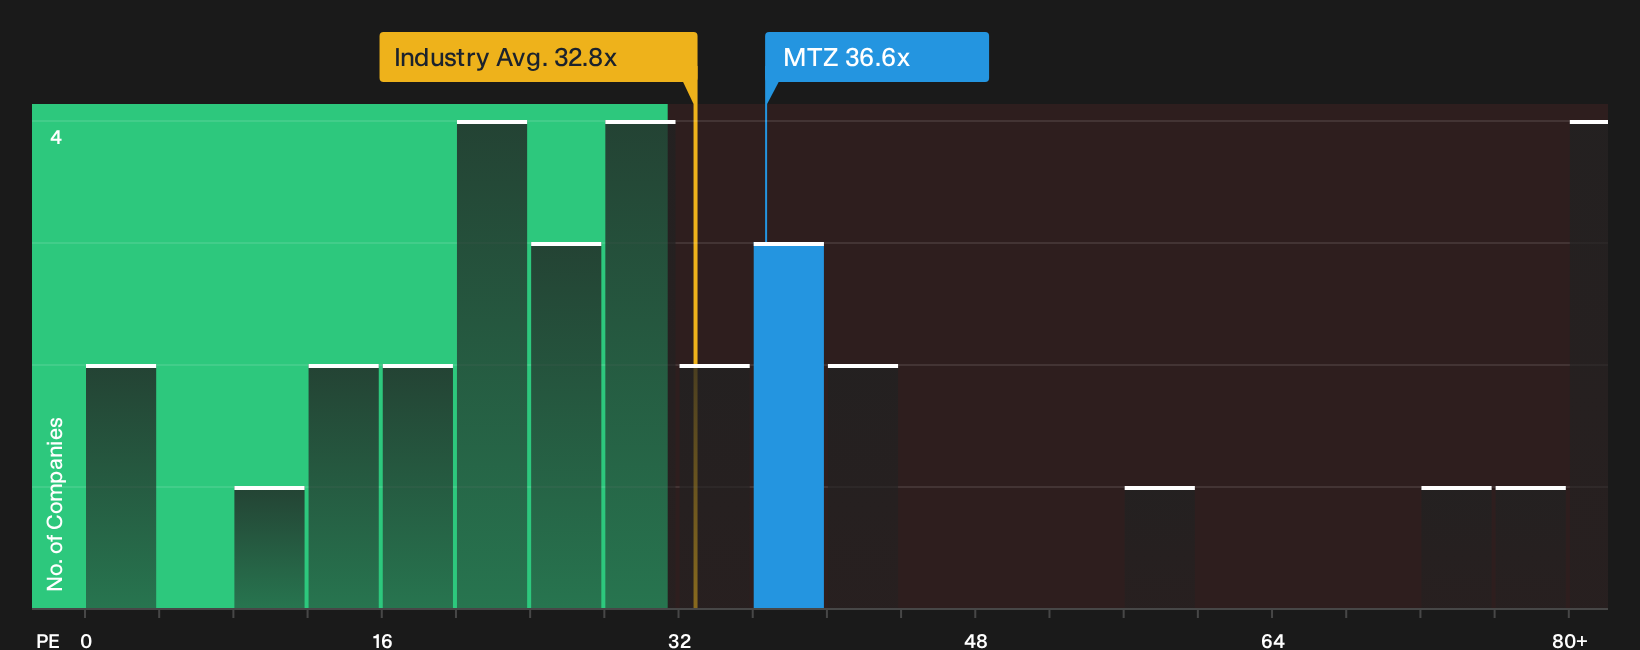
MasTec might look cheap against an internal fair value of $413.40, yet the market is not giving it a low price tag on earnings. The stock trades on a P/E of 36.6x versus 32.8x for the US Construction group and 30.5x for peers, while the fair ratio sits even higher at 39.1x.
That mix of a richer P/E than the sector and a fair ratio above both signals a tight margin for error if growth or margins slip, even if some investors see room for the multiple to move closer to that fair ratio over time. It raises a simple question: Is this a mispriced opportunity or just a higher risk way to get construction exposure?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around MasTec can make the story feel messy, so move quickly on your own homework and weigh both sides using the 3 key rewards and 1 important warning sign
Looking for more MasTec-adjacent investment ideas?
If MasTec has sharpened your focus on where capital might work harder, do not stop here. Broader opportunities across the market could suit your goals even better.
- Target sturdier balance sheets by scanning the list of solid balance sheet and fundamentals (25 results) that pair financial resilience with fundamental strength.
- Hunt for mispriced potential by checking the 19 high quality undiscovered gems that rarely feature on headline lists but still show solid underlying metrics.
- Prioritise staying power by reviewing the 31 resilient stocks with low risk scores that may better match a capital preservation mindset without stepping entirely out of equities.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com