


PDF Solutions (PDFS) drew investor attention after reporting Q2 2026 revenue of US$61.5 million, 19% higher year over year, reaffirming 20% full year growth guidance and highlighting a US$271 million backlog.
At a share price of US$54.44, PDF Solutions has just come off a 1-day share price decline of 2.92% after the Q2 release. However, the 7-day and 30-day share price returns of 9.38% and 19.26% point to strengthening momentum, while the 84.23% year to date share price return and 114.25% 1-year total shareholder return show that recent enthusiasm builds on a much longer upswing in investor confidence.
Scan for other semiconductor and AI infrastructure plays showing similar contract momentum to PDF Solutions by reviewing the hand picked 92 AI infrastructure stocks in the same space.
After a surge like this, with PDF Solutions leaning on a larger backlog and hotter AI demand, the real tension is simple: does the current valuation still leave enough upside to justify fresh risk?
Most Popular Narrative: 8% Undervalued
Analysts following PDF Solutions see its fair value at $59.38, which sits above the latest $54.44 close. As a result, the current setup points to a modest upside case that depends heavily on how recurring software economics evolve.
PDF Solutions is benefiting from surging semiconductor complexity, driven by trends like advanced packaging, AI, and 3D processing, which increases the need for its yield improvement and process analytics products; this supports ongoing top-line expansion as manufacturers seek to manage greater data and process variability.
See why 13 investors see PDF Solutions as 8% undervalued.
Result: Fair Value of $59.38 (UNDERVALUED)
Still, the narrative around PDF Solutions could be shaken if China exposure is disrupted by tech restrictions or if heavy R&D spending fails to translate into stronger profitability.
Find out about the key risks to this PDF Solutions narrative.
Another View: PDF Solutions Looks Expensive On Sales
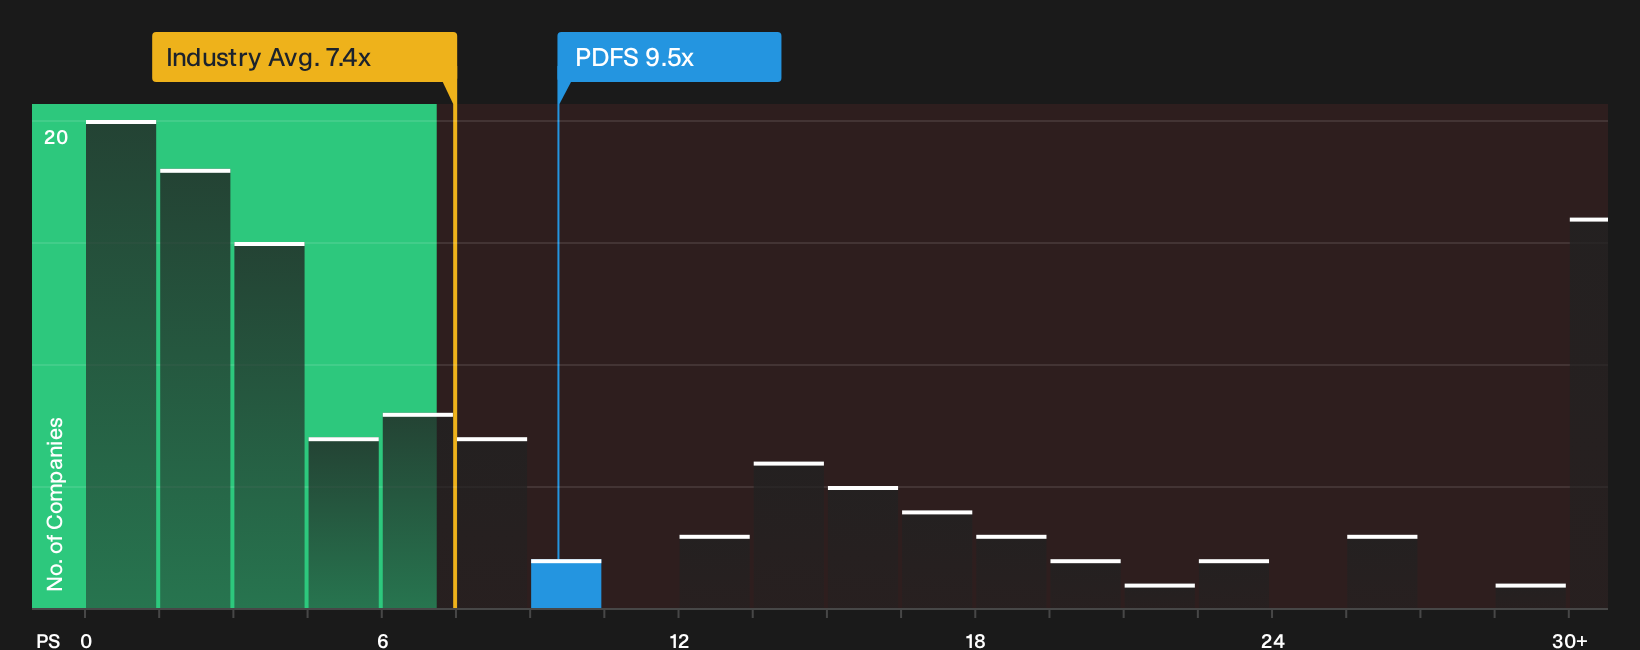
On the flip side of that fair value story, PDF Solutions trades on a P/S of 9.5x, compared with 7.2x for the US Semiconductor group and 2.7x for closer peers. The Simply Wall St fair ratio sits at 7.5x, which raises a simple question: How much valuation stretch are you comfortable paying for growth that is still being proved?
To see how those sales multiples line up against cash flows, margins and peer groups in more detail, have a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on PDF Solutions can pull investors in opposite directions, so move quickly, review the full data set and weigh the 2 key rewards and 3 important warning signs.
Looking For More Ideas Beyond PDF Solutions?
If PDF Solutions caught your eye, do not stop here. Broader context matters, and a wider watchlist often reveals opportunities you would otherwise miss.
- Target sturdier portfolios by reviewing a list of solid balance sheet and fundamentals (25 results) that can help anchor your higher risk positions.
- Hunt for potential mispricings through the 19 high quality undiscovered gems that pair quality fundamentals with quieter market attention.
- Stack income potential on top of growth by scanning the 8 dividend fortresses and spotting yields that fit your risk tolerance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com