


- Wise Group recently introduced an integrated travel feature that pairs customizable eSIM data plans across more than 150 destinations with a cross border QR payment scanner covering schemes in Europe, Asia and the Americas through partners including Alipay+.
- This move pushes Wise Group beyond pure money transfers into connectivity and in trip spending. It could deepen customer engagement and broaden fee earning use cases around its existing account and card products.
- The focus now shifts to what this combined eSIM and QR payment roll out might mean for Wise Group's broader investment narrative.
Scan other travel focused payment plays by reviewing our hand picked list of 19 high quality undiscovered gems that are building products around cross border spending and connected customers.
Wise Group Investment Narrative Recap
For Wise Group, the core belief is that a broad cross border money platform can keep pulling in more everyday usage from 19 million customers, not just one off transfers. The new eSIM and QR payments bundle leans into that idea. It extends Wise into connectivity, in trip spend and more reasons for balances to sit in the account.
The near term swing factor remains how Wise manages price cuts, rising costs and reliance on interest income without eroding margins further. This launch appears helpful for engagement but not a clear, near term fix for take rate compression or regulatory risk around how interest on US$39b of customer balances can be shared.
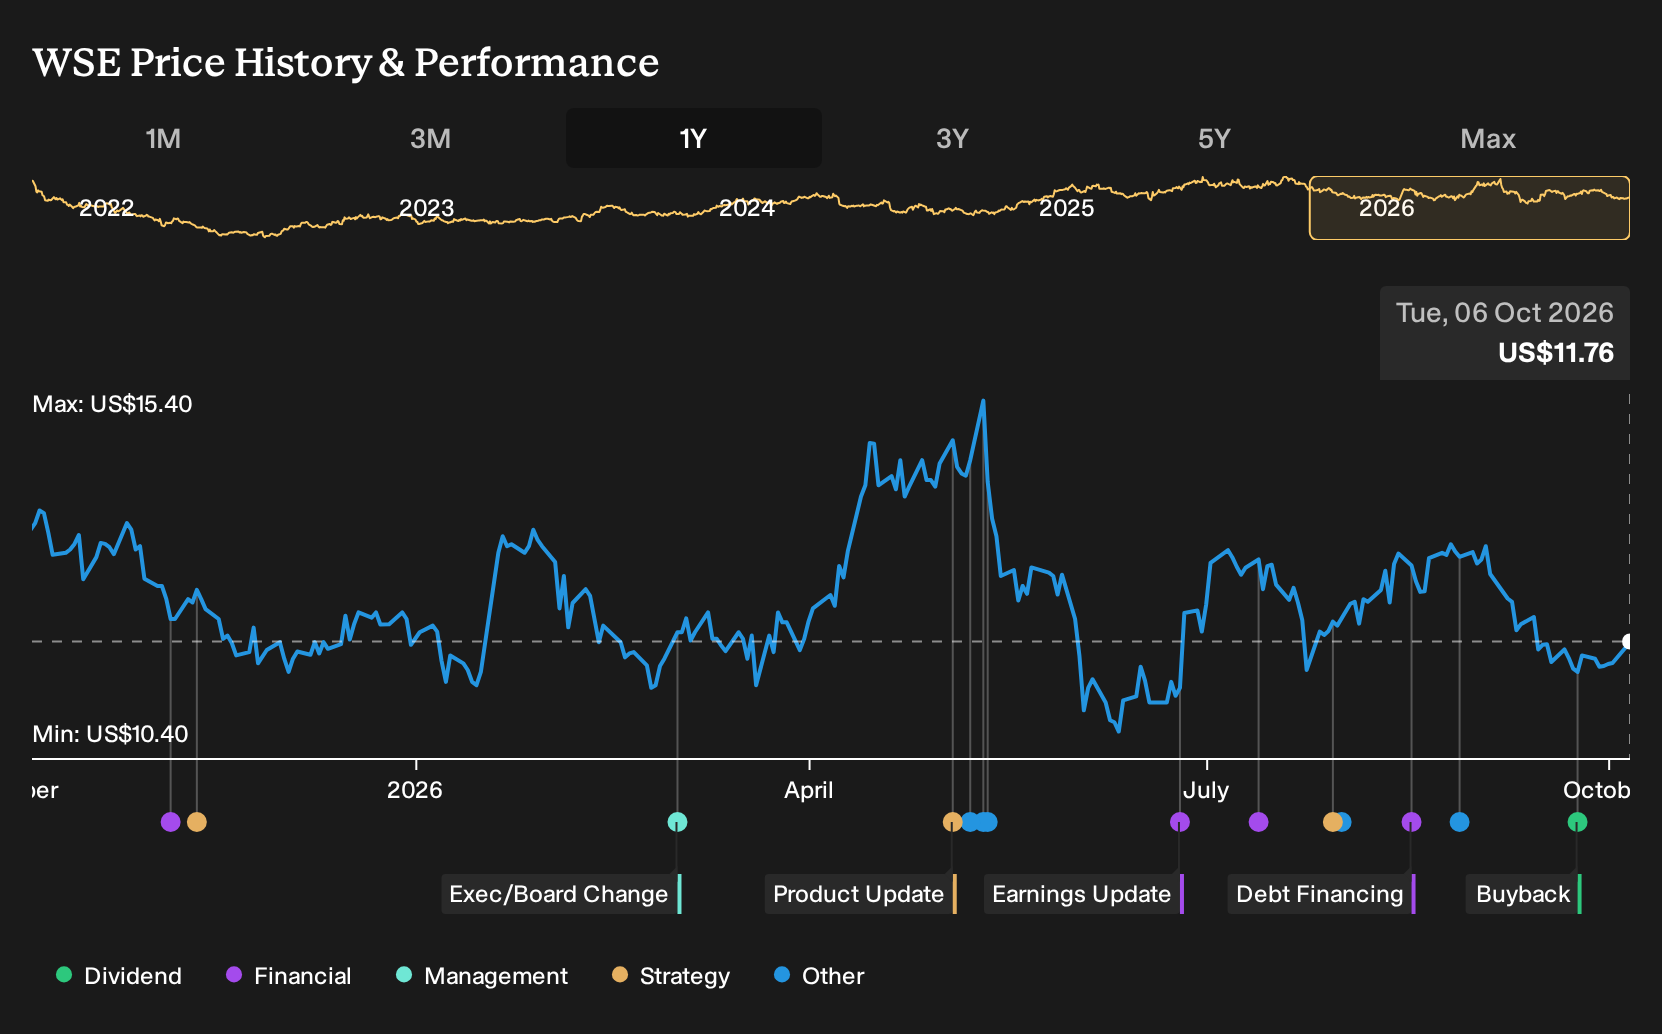
The recent share buyback program, which allows Wise Group to repurchase up to 102,516,456 shares, sits quietly in the background of this product push. Any reduction in the share count, if executed, would interact with earnings trajectories that already assume measured revenue growth and only modest margin pressure.
For you as a holder or prospective holder, the more interesting angle is execution. Management is adding complex global features such as QR schemes and eSIMs while also committing to repurchases and managing a high P/E multiple. The key consideration is whether product depth like this can keep transaction volumes expanding enough to offset lower pricing and a potential step down in interest income if rate conditions or rules change.
Wise Group's current analyst story points to revenues of $4.1b and earnings of $775.2 million by 2029, based on revenue growing around 18.3% a year and earnings rising by about $276.5 million from $498.7 million today.
Uncover why Wise Group's fair value indicates a 44% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about $13.44 and $16.94, so some private investors see Wise Group as meaningfully mispriced. These are prior to the eSIM and QR rollout, share buyback and new director appointment. Use this spread as a starting point, then test your own assumptions on pricing pressure, interest income and regulation.
Explore 2 other Wise Group fair value estimates, including one that suggests it could be worth just $13.44.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Wise Group research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Wise Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wise Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Wise Group?
Once you have a view on Wise Group, it can help to compare your thesis with other opportunities that share some of the same themes, like balance sheet strength, income potential or mispriced quality.
- For investors who want resilient businesses before anything else, start with a 31 resilient stocks with low risk scores that can keep your downside in focus while you assess upside potential.
- If income is a priority, scan a curated set of 8 dividend fortresses that combine higher yields with the sort of payout profile many long term holders look for.
- To round things out with quality that is not yet crowded, weigh up a 19 high quality undiscovered gems that screens for fundamentals first and popularity second.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com