


HVAC (heating, ventilation and air conditioning) and refrigeration equipment distributor Watsco (WSO) was one of 134 NYSE securities hitting new 52-week lows on Tuesday.
The Florida-based company hit its 17th new 52-week low of the past year yesterday at $290.10. It hasn’t traded this low since January 2023.
You would think that, with climate change being a serious challenge to the survival of the planet, let alone the global economy, investors would be more enthusiastic about the 79-year-old company that switched from manufacturing to distribution in 1989.
Since the transition, WSO stock has gained 10,220% cumulatively, or 13.34% annualized, 513 basis points higher than the Dow Jones Industrial Average.
WSO stock has historically traded at a premium valuation, with investors paying between 28x and 30x forward earnings. Investors and analysts clearly do not feel its future potential merits such a multiple. Other factors have also contributed to the share price stalling and then falling over the past two years.
On Nov. 25, 2024, WSO hit an all-time high of $571.42. In less than two years, it has lost nearly 50% of its value.
Which begs the question: value buy or value trap? Here are my two cents.
What’s Concerning About Watsco’s Business
The three biggest issues investors face with Watsco’s business right now are gross margins, slow organic growth, and a business model built around acquisitions.
In the second quarter ended June 30, its gross margin was 27.5%, 180 basis points lower than Q2 2025. In the first six months of the year, the gross margin was slightly better at 27.7%, 100 basis points lower than in the same period a year ago.
The company said the drop in gross margin resulted from equipment manufacturers raising prices in 2025 due to their own rising costs. Watsco passed those costs on to customers. Gross margin has stabilized in 2026 as suppliers' prices have returned more in line with historical levels.
However, the average gross margin over the past five Q2 quarters is 28.0%, so it remains to be seen whether it can return to that .
In the second quarter, Watsco’s revenues were $2.10 billion, up 2.1% from Q2 2025. Same-store sales rose just 1%. Its same-store growth in 2024, when its stock hit an all-time high, was 3%, higher than growth from acquisitions.
Watsco’s organic growth is a bit of a feast-or-famine situation. Its same-store sales growth in the past years (2021 through 2025) has been 18%, 14%, -1%, 3%, and -5%.
The stock’s premium valuation is rooted in two good years of organic growth in 2021 (18%) and 2022 (14%), leading up to its November 2024 all-time high. It needs to be more consistent on this front.
That leads to the final issue: a business model built around acquisitions. It has made 73 since it transitioned from manufacturer to distributor in 1989.
The latest was announced in mid-September. It acquired New Hampshire-based The Granite Group, a distributor of HVAC and plumbing products with $500 million in annual revenue from the seven states where it operates. Watsco paid $505 million for the distributor, split between 80% cash and 20% stock.
Acquisitions of any size aren’t easy to integrate. Management can't guarantee that the potential they see in an acquired company will come to fruition. Plenty of money has been wasted on poor-fitting acquisitions. That doesn’t appear to be the case here, but you never know for certain until long after the purchase is complete.
Further, Watsco has never made an acquisition anywhere near as large as the one it just made with Granite Group. Investors are left to wonder if this is an act of desperation or transformation.
I guess we'll see.
What Investors Should Like About It
While there may be ebbs and flows in Watsco’s business, I do not doubt that companies competing in this sandbox should have no concerns about demand for HVAC and refrigerant equipment over the next decade or more. The planet isn’t getting any cooler.
Three things make Watsco’s business stand out.
First, it's the largest distributor (10% share) in a fragmented North American HVAC market valued at $74 billion, with over 120 million HVAC systems installed that will eventually need replacing.
Despite making over 70 acquisitions since 1989, more than 2,100 independent HVAC distributors still operate in the North American market. If it acquired 10 annually, it would take 210 years to buy them all, which is not possible, either from a time perspective or because of regulatory oversight.
So, its Buy & Build acquisition strategy will remain in place until it’s proven not to deliver an appropriate return on capital invested.
Second, the company’s e-commerce sales continue to contribute significantly to Watsco’s overall business. In the 12 months ended June 30, e-commerce sales were $2.7 billion, accounting for 37% of total sales.
This side of the business has come a long way since it started its e-commerce joint venture with Carrier (CARR) in 2015. Investors should expect this business to keep growing with HVAC contractors in North America.
Finally, it’s grown its business without piling on debt. It finished the second quarter with no long-term debt and $464 million in cash. While the Granite Group acquisition will likely require the company to use some of its credit facility to finance its largest acquisition ever, it will still be just 1-2% of its market cap, more than manageable.
At the same time, it will use its approximately $700 million in annual free cash flow to pay significant dividends and repurchase its shares. In the past six years, it has paid out approximately $2.41 billion in dividends.
With a high 4.7% dividend yield, it will likely accelerate its share repurchases as soon as it’s financially prudent. Investors can expect Watsco’s shareholder yield to increase in the near term while its share price remains deflated.
Is WSO a Value Buy or Value Trap?
The chart from S&P Global Market Intelligence below shows the forward P/E ratio at any given time in the past five years. Today, it is 23.6x; it hasn’t been this low since October 2023.
Some argue it has never deserved a 20+ forward P/E multiple, making the historical record irrelevant. I would say that Watsco can’t do anything about what investors are willing to pay for its stock. The market is usually right.
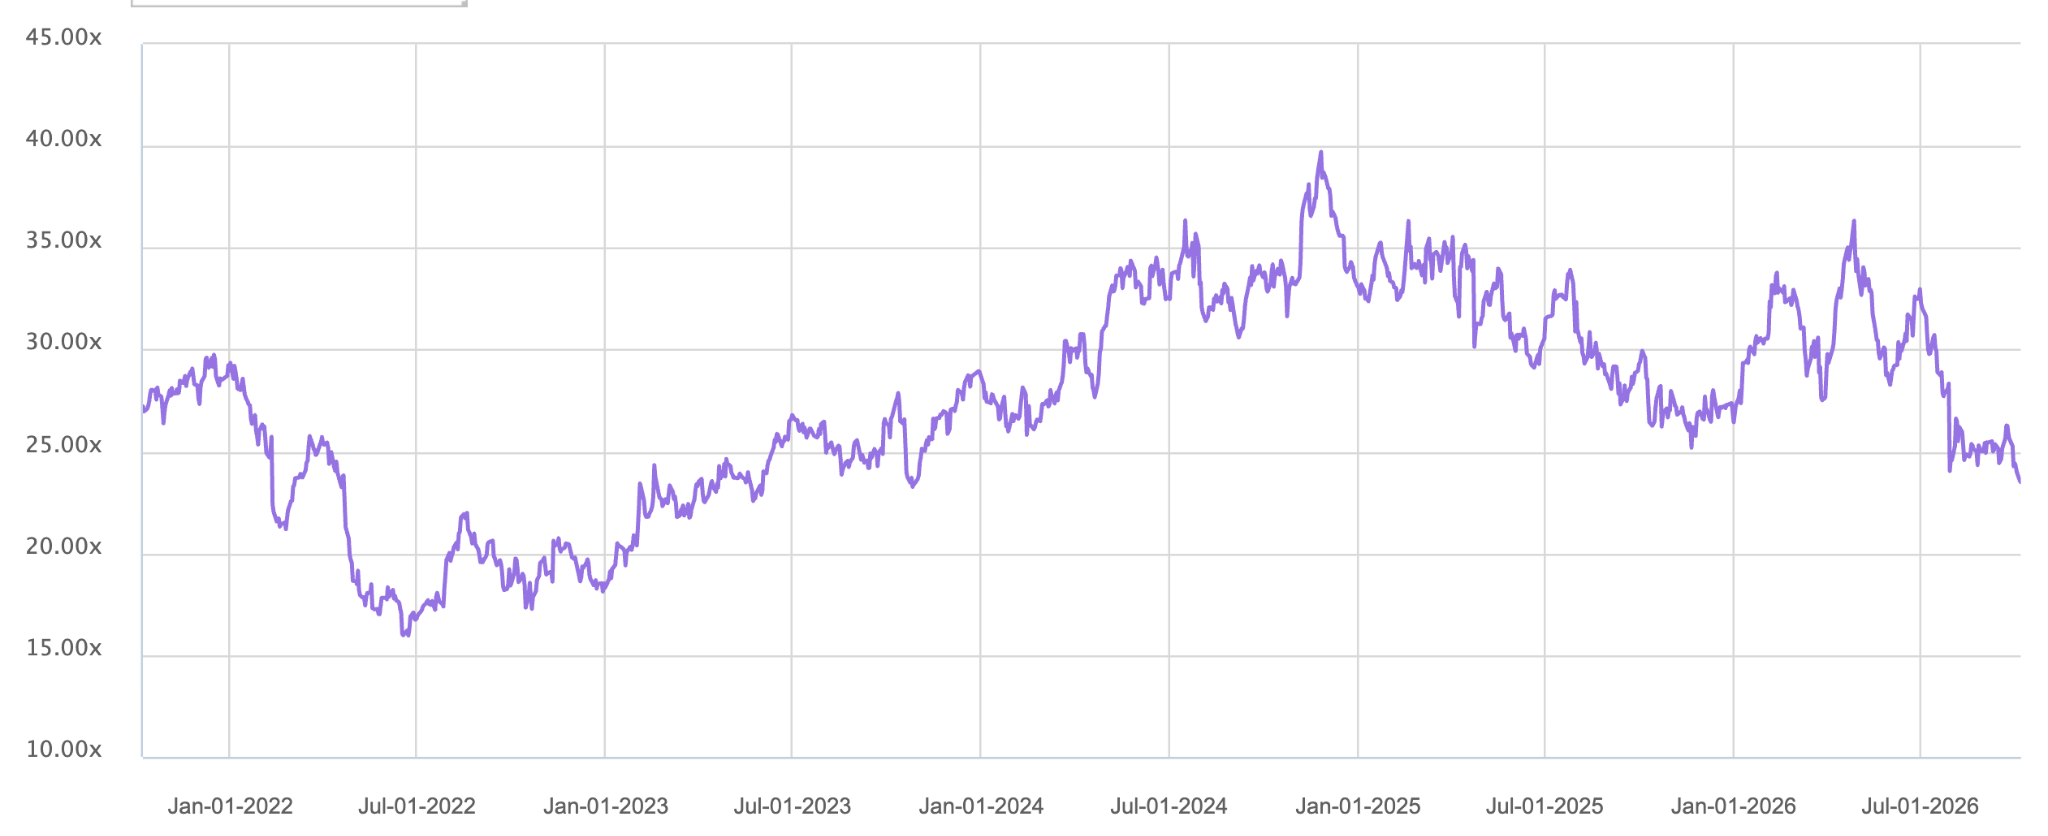
Source: S&P Global Market Intelligence
The question is whether investors will keep paying up for this quality business.
I think they will and should, because few businesses are run as well. Distributorships aren’t easy to operate. If they were, you’d see less fragmentation in the North American HVAC market.
As long as it keeps its long-term gross margin above 27% and focuses on growing same-store sales at 3% or more, its carefully selected acquisitions will take care of the rest.
Is it possible that WSO drops further in 2026? Absolutely. Will it drop to $220.68, Watsco’s five-year low? That seems unlikely given its nearly two-year fall from grace.
If Watsco hasn’t bottomed, it’s close. For long-term WSO holders, I like this value buy under $300.
On the date of publication, Will Ashworth did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.