


- EU and Chinese policymakers have been engaged in trade talks over low cost Chinese hybrid and electric vehicles, putting Mercedes-Benz Group under scrutiny as rules on imports, pricing and supply chains for European automakers are reassessed.
- The key operational risk for Mercedes-Benz Group is slower fleet refresh and softer software income if cheaper Chinese EVs face fewer trade constraints and weaken demand for its higher priced models.
- The focus now shifts to how the Mercedes-Benz Group investment narrative holds up as EU trade policy on Chinese EV imports becomes the central pressure test.
Scan beyond Mercedes-Benz Group and see how other European automakers stack up against Chinese competition with our hand picked list of solid balance sheet and fundamentals (207 results).
Mercedes-Benz Group Investment Narrative Recap
To own Mercedes-Benz Group, you need to believe the premium model, with high priced vehicles and software heavy features, can still earn decent returns even as Chinese EVs undercut on price. The near term hinge point is how fast new EV and hybrid models using MB.EA and MB.OS can refresh the line up without crushing free cash flow.
The biggest risk remains profit pressure from weaker China demand, trade rules that add 150 bps of margin drag, and high capex for electrification and software that peaks in 2025. The latest EU China trade talks mainly reinforce that tariff and import policy are now a real swing factor rather than a side issue.
There has not been a fresh Mercedes-Benz Group announcement directly tied to these Brussels Beijing negotiations. The most relevant information is management’s existing guidance for significantly lower sales in 2025 versus 2024, mainly from China, and the stated full year 150 bps margin impact from global tariffs and trade frictions.
Against that backdrop, the EU’s stance on Chinese EV imports becomes a live test of those margin and volume assumptions. Any change in effective market access, pricing power, or required localization spend would run straight through to cash generation, dividend cover, and the timing of when heavy spending on MB.EA, MB.OS, and the NLP efficiency program starts to ease.
Mercedes-Benz Group's current analyst narrative points to €140.9b in revenue and €6.8b in earnings by 2029, based on 2.9% yearly revenue growth and an increase in earnings of €1.8b from €5.0b today.
Uncover why Mercedes-Benz Group's fair value indicates a 40% potential upside to its current price, which could narrow quickly.
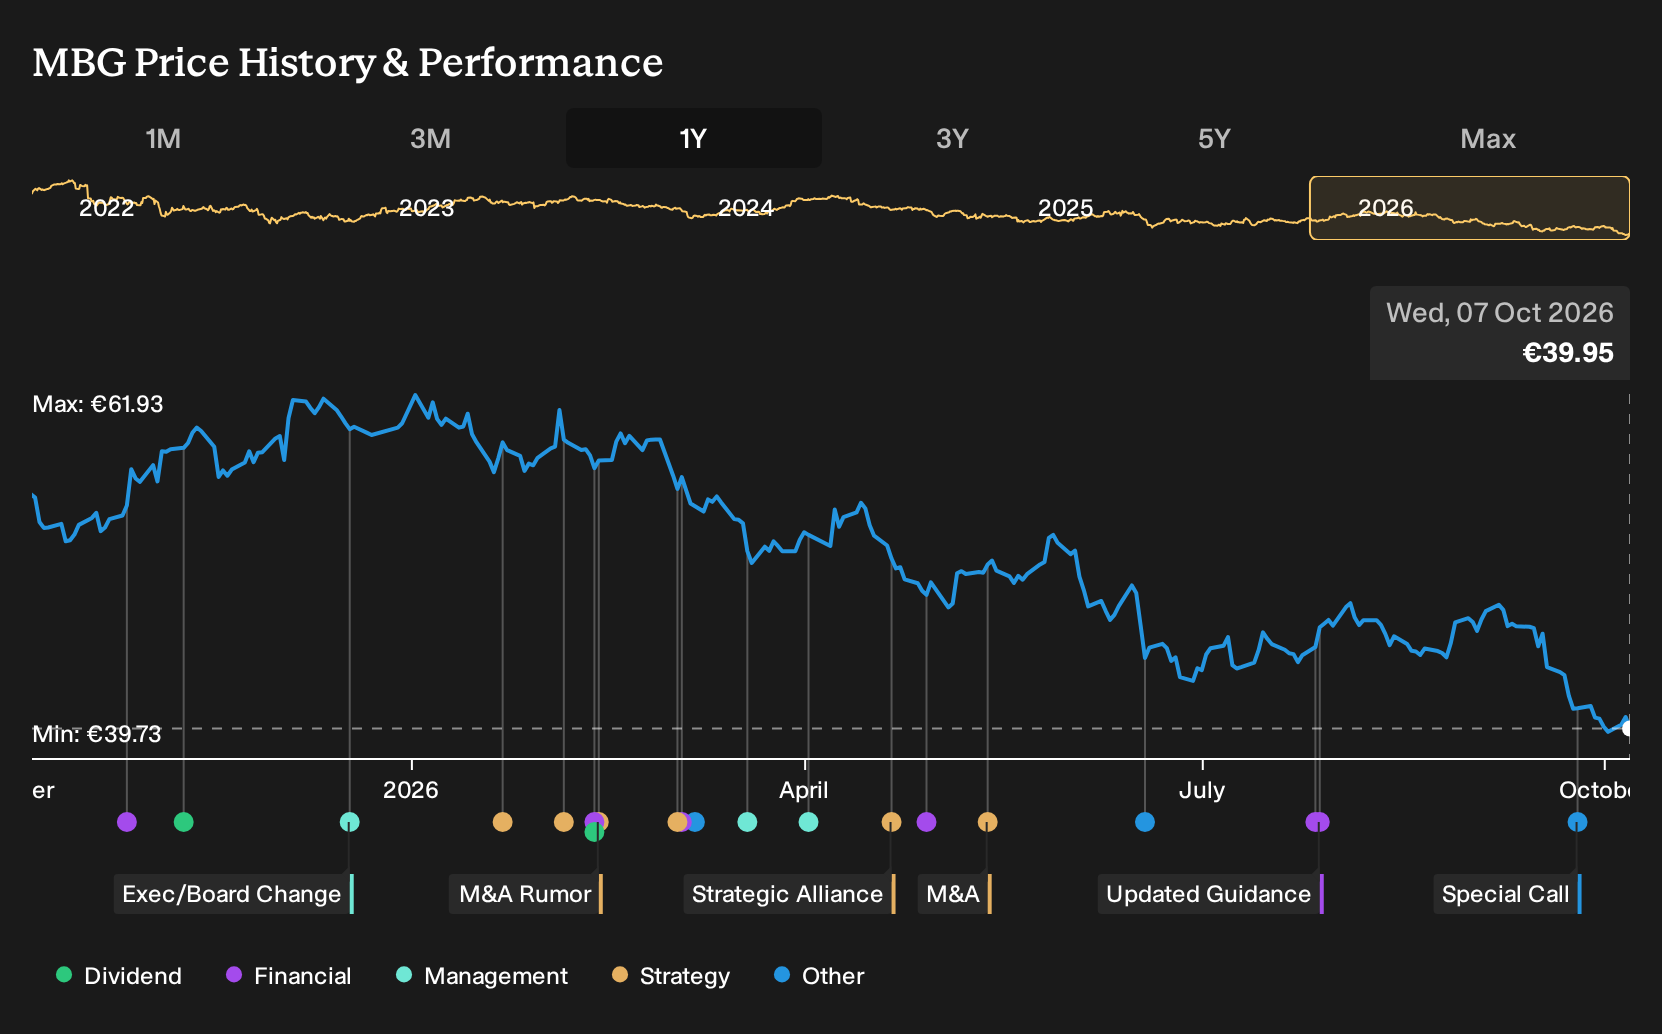
Exploring Other Perspectives
Some of the most optimistic analysts frame the Brussels Beijing talks very differently for Mercedes-Benz Group. You can treat tariff pressure as a short term hurdle that accelerates the shift to local for local production and deeper software and financial services income. That camp was pencilling in €145.6b of revenue and €8.5b of earnings by 2029, well above the baseline. Both narratives were built before this trade news, so views may change. Use this as a cue to compare several angles before you decide what feels reasonable.
Explore 5 other Mercedes-Benz Group fair value estimates, including one that suggests as much as 40% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research and analysis.
- A great starting point for your Mercedes-Benz Group research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Mercedes-Benz Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mercedes-Benz Group's overall financial health at a glance.
Looking for more investment ideas beyond Mercedes-Benz Group?
If the Mercedes-Benz Group story has you thinking about portfolio balance, you can use this as a springboard to explore other opportunities that fit your risk, income, and quality preferences through the Simply Wall St Screener.
- For potential value opportunities with resilient fundamentals, explore our 181 high quality undervalued stocks, which already clear basic quality checks.
- If you care most about income and payout resilience, consider this hand picked set of 169 dividend fortresses that may suit a yield focused approach.
- For a focus on financial strength and cleaner balance sheets, narrow your shortlist using the 227 resilient stocks with low risk scores that screen for lower risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com