


- GEO Group has redeemed all US$650,000,000 of its 8.625% Senior Secured Notes due 2029, using asset sale proceeds to fund an approximately US$678,000,000 payout and discharging the related indenture after depositing funds with the trustee.
- The company extended its US$550,000,000 revolving credit facility to 2031 and gained flexibility to make larger share repurchases, supported by a higher US$1.25b authorization that depends on leverage thresholds.
- We will now look at how GEO Group’s expanded capacity for share repurchases could reshape the existing investment narrative around detention contracts.
GEO Group Investment Narrative Recap
To own GEO Group, you need to be comfortable with a business still heavily tied to U.S. immigration detention and electronic monitoring contracts, where volume and pricing are shaped by policy and federal budgets rather than consumer demand. The short term swing factor remains how quickly ICE funded beds and ISAP monitoring capacity are used, which this debt move does not directly change.
The main operational risk stays the same. A shift in immigration priorities, funding delays or contract scrutiny could leave facilities and high security beds underused, and fee based services such as skip tracing can pause if appropriations lapse. The new balance sheet actions do not remove that dependence on federal decision making.
The most relevant piece of news for you is GEO Group redeeming all US$650,000,000 of its 8.625% Senior Secured Notes due 2029 using asset sale proceeds and extending its US$550,000,000 revolver to 2031. Retiring expensive secured debt can cut interest burden and frees covenant room, which supports GEO Group’s ability to fund detention expansions if ICE activates more beds.
Those same credit agreement changes now allow unlimited restricted payments, including buybacks, once leverage tests are met, alongside an authorization increased to US$1.25b through 2029. That extra flexibility gives management more options if cash flow from ICE contracts, ISAP and any future facility sales remains healthy. It also raises the question of how much capital goes to repurchases versus further reducing higher cost debt.
GEO Group's narrative projects US$3.8b revenue and US$137.8m earnings by 2029. That profile assumes revenue grows at 9.9% per year and earnings decline by about US$153.7m from US$291.5m today to reach the 2029 consensus forecast.
Uncover why GEO Group's fair value indicates a 26% potential upside to its current price that may not last much longer.
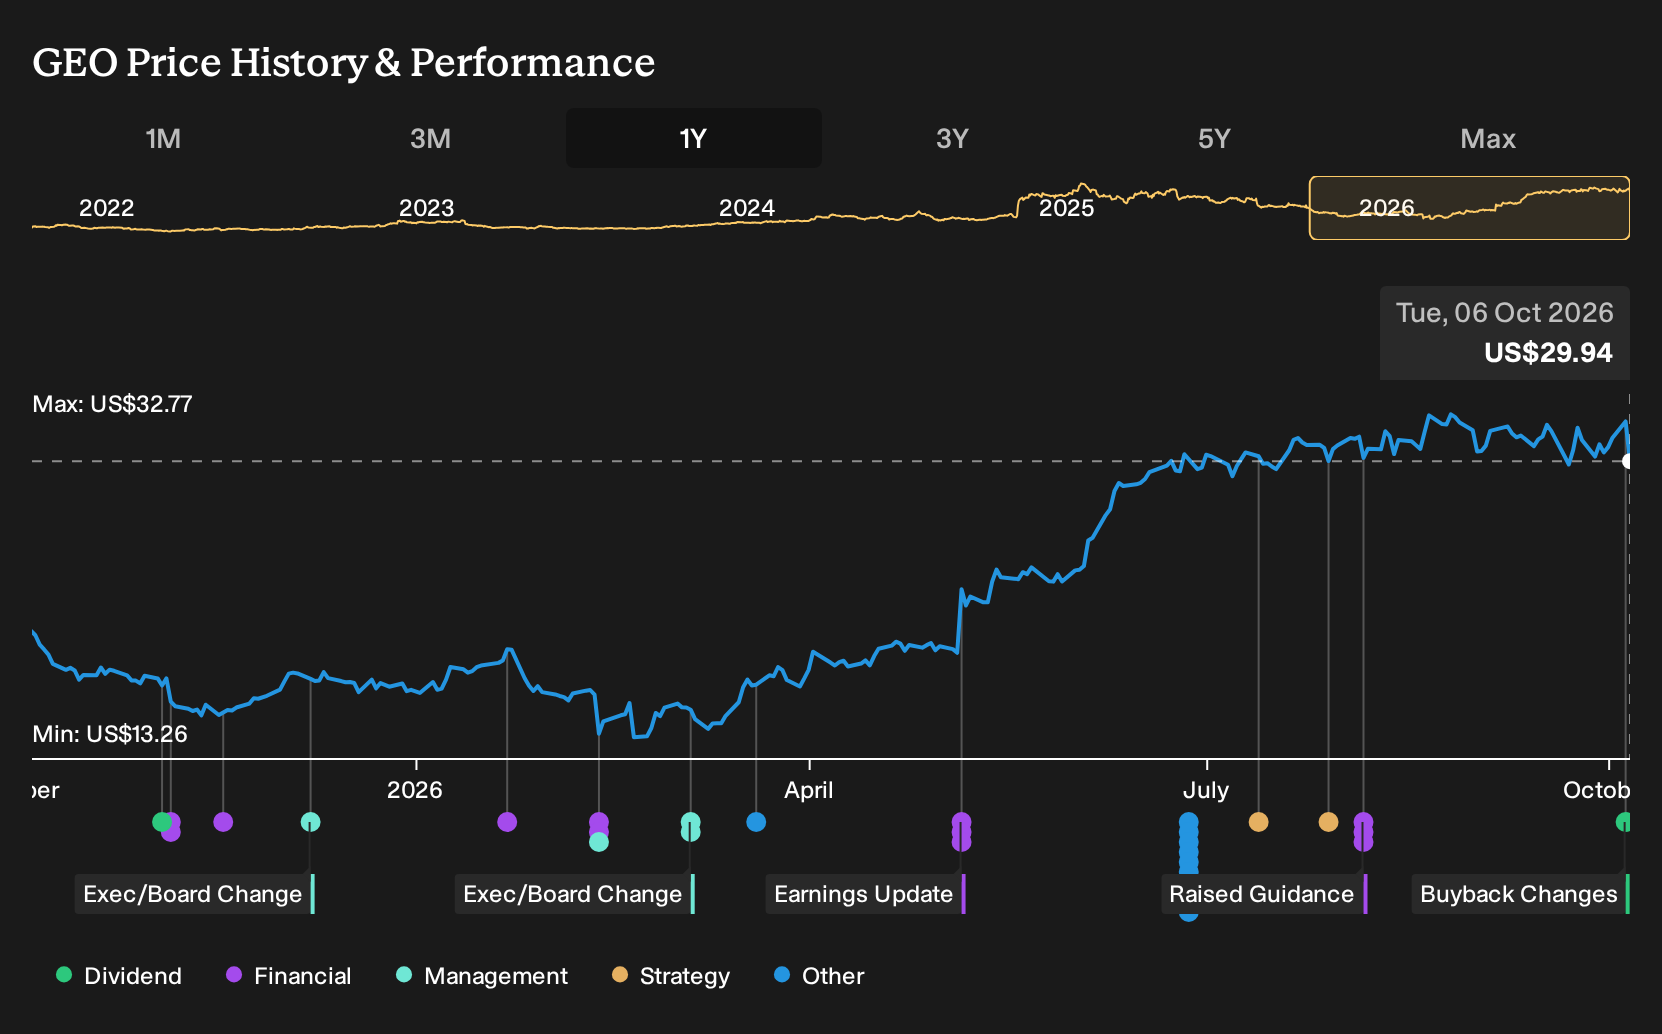
Exploring Other Perspectives
Some of the most optimistic analysts focus on GEO Group’s shift toward asset light contracts as a key upside catalyst. Before this debt and buyback news, they were already modeling about US$3.9b revenue and US$177.1m earnings by 2029. You can read those rosiest scenarios as one end of a wide spectrum that may evolve as this balance sheet reset plays through.
Explore 3 other GEO Group fair value estimates, including one that suggests potential upside of up to 433% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your GEO Group research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for GEO Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate GEO Group's overall financial health at a glance.
Looking for more investment ideas beyond GEO Group?
If the GEO Group story has you thinking about position sizing, balance sheet repair and capital returns, it can help to scan a wider field of opportunities using the Simply Wall St Screener.
- If you want income to do more of the heavy lifting, take a look at 8 dividend fortresses that focus on higher yields with an emphasis on resilience.
- If capital preservation ranks high on your checklist, filter for 31 resilient stocks with low risk scores that score well on balance sheet strength and business stability.
- If you are hunting for businesses that the market may not be fully pricing yet, start with 19 high quality undiscovered gems that pair solid fundamentals with relatively low visibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com