


United Airlines Holdings (UAL) has moved back into focus after a downward revision to earnings per share projections. This has pushed the stock into a Zacks Rank of #5 and signaled softer analyst sentiment.
Recent trading has been choppy for United Airlines Holdings, with the share price slipping around 11% over the past 90 days even though the 1 year total shareholder return is about 15.8%. This hints that longer term holders have still been rewarded while shorter term momentum has faded as the earnings reset and Strong Sell ranking weigh on sentiment, despite product news like the A321XLR delivery and upcoming appearances such as the Velocity 2026 conference.
Compare United Airlines Holdings with a curated 27 high quality undervalued stocks that analysts are watching closely as sentiment resets around earnings expectations.
United Airlines Holdings has given back some recent gains while longer term holders are still ahead, which sets up a simple tension: Is the meaningful move already in the rearview mirror, or does current pricing still leave room?
Most Popular Narrative: 28% Undervalued
Against a last close of $111.87, the most followed narrative for United Airlines Holdings pegs fair value at about $156.35. This frames the recent pullback as a potential mispricing rather than a simple loss of enthusiasm.
Execution of the United Next fleet modernization and capacity expansion strategy, particularly upgauging to larger, more fuel-efficient aircraft with more premium seats, will unlock further operational leverage, reduce per-seat operating costs, and drive operating margin improvement over the next several years.
See why 72 investors see United Airlines Holdings as 28% undervalued.
Result: Fair Value of $156.35 (UNDERVALUED)
Still, the United Airlines Holdings narrative leans heavily on stable premium demand, while carrying meaningful exposure to fuel costs and higher financial leverage that could pressure those assumptions.
Find out about the key risks to this United Airlines Holdings narrative.
Another View On United Airlines Holdings Valuation
The first narrative leans on analyst targets and earnings forecasts, yet the SWS DCF model for United Airlines Holdings points in the opposite direction. On those cash flow assumptions, UAL at $111.87 screens as overvalued versus an estimated future cash flow value of $90.37. Which lens do you trust more: projected cash generation or earnings multiples?
Look into how the SWS DCF model arrives at its fair value.
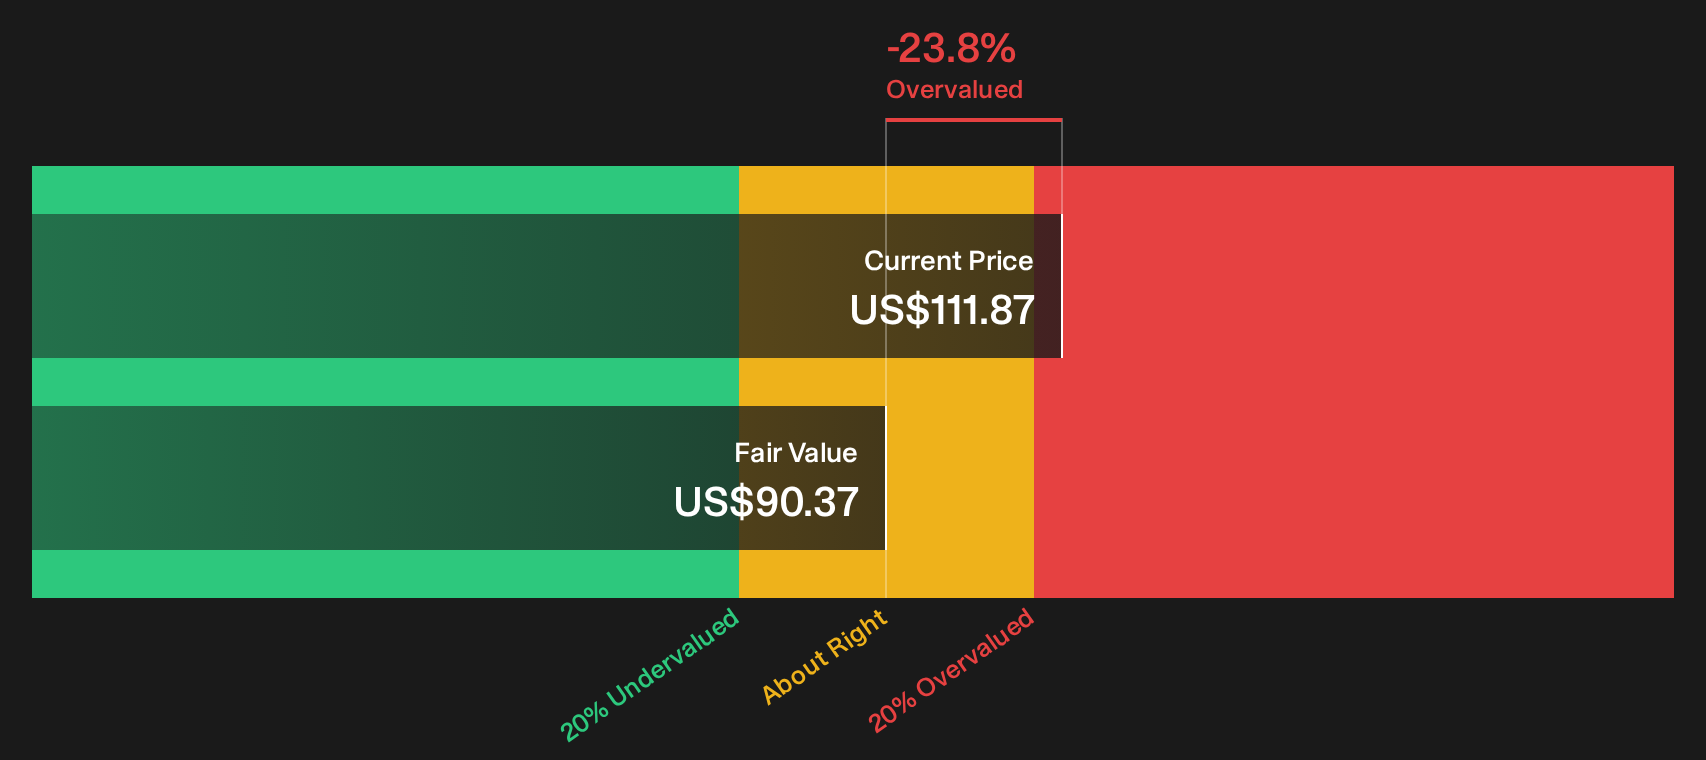
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out United Airlines Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around United Airlines Holdings can feel messy. Move quickly, look through the data yourself, and weigh the 5 key rewards and 2 important warning signs.
Looking for more investment ideas beyond United Airlines Holdings?
If United Airlines Holdings has your attention, do not stop there. Use the Simply Wall Street screener to spot fresh opportunities before they move without you.
- Target reliable cash generators by scanning companies with resilient balance sheets through the list of solid balance sheet and fundamentals (25 results).
- Hunt for quality businesses that the market may be overlooking by checking the 19 high quality undiscovered gems.
- Reduce portfolio stress by focusing on companies with steadier profiles inside the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com