


- ArcelorMittal reported that its Kryvyi Rih complex in Ukraine suffered four missile strikes over five weeks, resulting in five employee fatalities, 17 injuries and extensive damage to production facilities.
- The group plans to book an estimated US$1b non cash impairment related mainly to damaged property, plant and equipment at ArcelorMittal Kryvyi Rih, which directly affects asset values and future earnings capacity.
- This development raises questions about how ArcelorMittal’s investment narrative may adjust in light of the US$1b impairment tied to the Kryvyi Rih attacks.
Scan how other steel and materials stocks handle operational shocks like ArcelorMittal by reviewing our hand picked list of solid balance sheet and fundamentals (206 results) for potential resilience and downside protection.
ArcelorMittal Investment Narrative Recap
To own ArcelorMittal, you need to be comfortable with a large, cyclical producer that is trying to balance heavy decarbonisation spending with returns to shareholders. The immediate operational story now includes impaired capacity in Ukraine and a planned US$1b non cash charge. That affects reported earnings but not near term cash in itself.
In the short run, attention sits on how reliably ArcelorMittal can keep projects in Europe, India and the Americas on track while managing war related disruption and global overcapacity risk. The biggest operational swing factor remains utilisation and pricing. The key vulnerability is any mix of weaker demand, tariff shocks or further project delays.
The most relevant announcement is ArcelorMittal’s plan to record about US$1b of non cash impairment at Kryvyi Rih. That adjustment lowers the carrying value of Ukrainian assets and acknowledges damage to property, plant and equipment after repeated missile strikes, which in turn reduces future earnings capacity from that site.
For catalysts, this matters because management has already injected more than US$700m to support Ukrainian operations and maintain continuity. Investors now have to weigh that capital commitment and lower asset base against other uses of cash such as green steel capex, expansion in India and Brazil and any future portfolio reshaping or buybacks.
What The ArcelorMittal Forecasts Actually Assume
ArcelorMittal's narrative projects US$75.5b in revenue and US$5.7b in earnings by 2029. That profile rests on analysts building in 6.3% yearly revenue growth and an earnings increase of about US$3.9b from roughly US$1.8b today.
Uncover why ArcelorMittal's fair value indicates a 22% potential upside to its current price, which could narrow quickly.
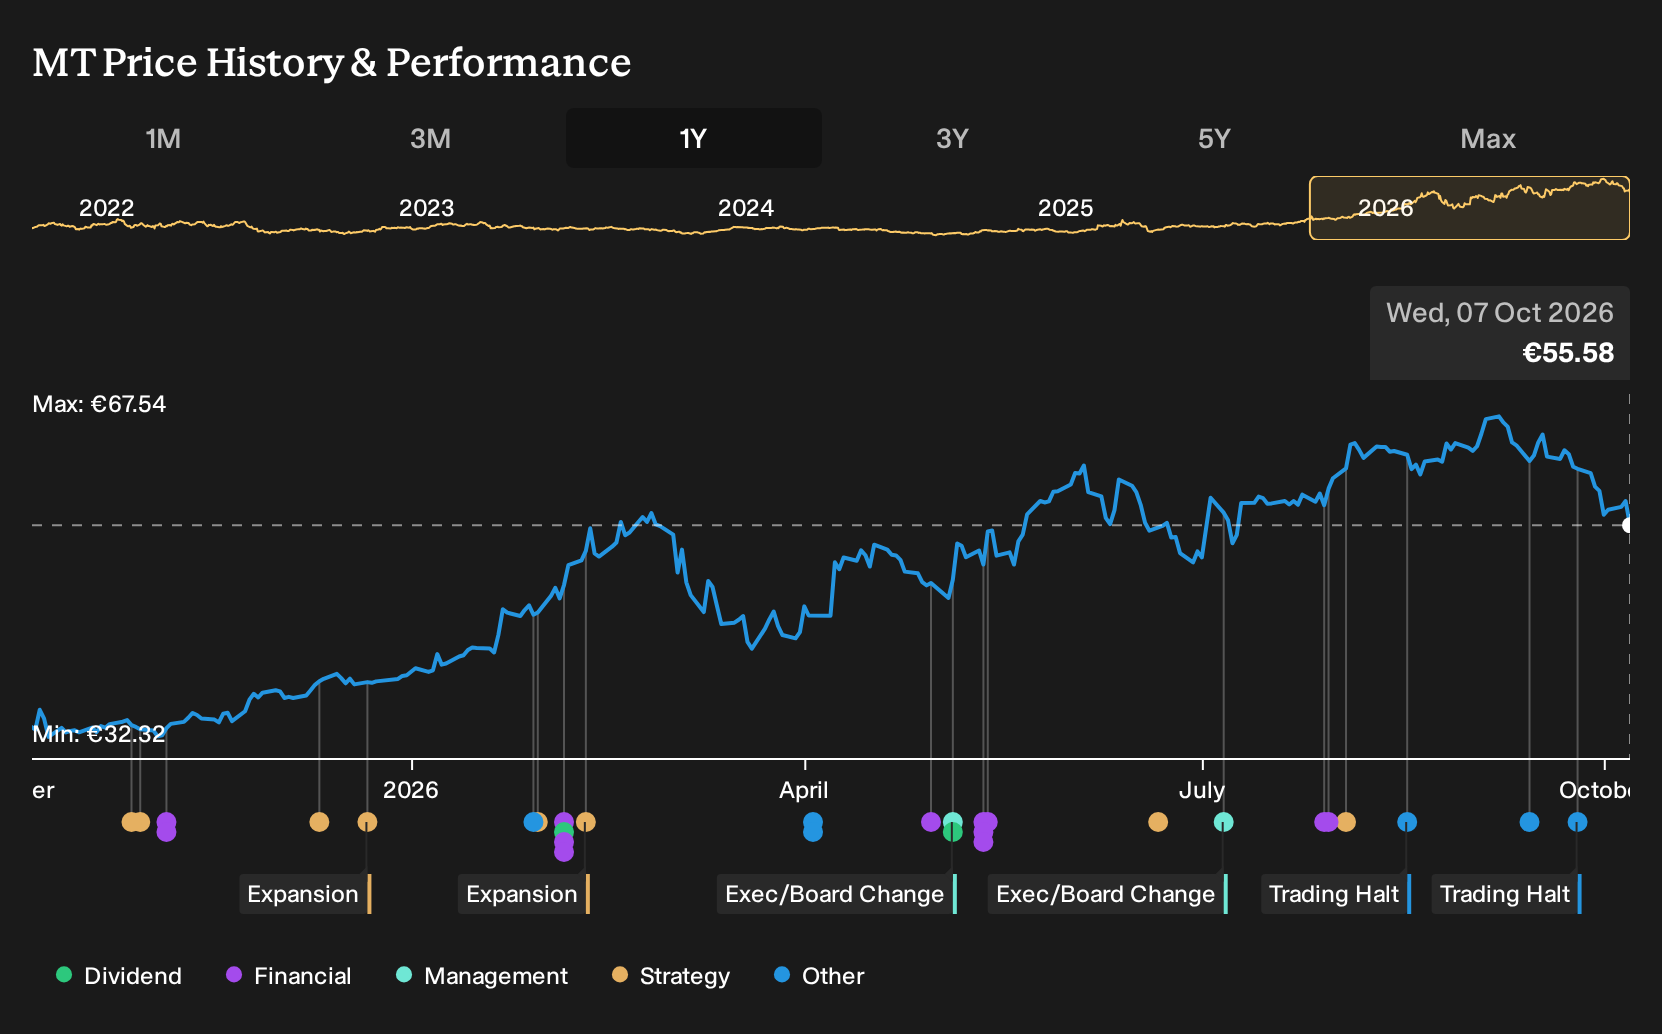
Exploring Other Perspectives
You can also weigh a very different angle. Some of the most optimistic analysts were pencilling in ArcelorMittal revenue of about US$81.3b and earnings near US$7.9b by 2029, assuming strong execution of big growth projects. The Kryvyi Rih attacks may cause those expectations to be revisited, so compare several viewpoints before deciding.
Explore 2 other ArcelorMittal fair value estimates, including one that suggests as much as 56% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your ArcelorMittal research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for ArcelorMittal. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ArcelorMittal's overall financial health at a glance.
Looking For More Ideas Beyond ArcelorMittal?
If you want to stress test your ArcelorMittal view against other opportunities, it can help to line it up beside businesses with different balance sheet strength, valuation profiles and payout habits. The Simply Wall St Screener lets you filter for those traits quickly so you can build a watchlist that suits your risk tolerance and income needs.
- For investors who want potential mispricings backed by fundamentals, scan our 184 high quality undervalued stocks that pair quality metrics with discounted valuations.
- If stability matters more than aggressive growth, focus on companies screened for resilient finances using the 227 resilient stocks with low risk scores as a starting universe.
- Income focused readers can prioritise cash returns to shareholders by zeroing in on the 170 dividend fortresses and assessing which payouts look sustainable.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com