


Election surprise and M&A retreat reset expectations for Nu Holdings
Nu Holdings (NYSE:NU) just rode a sharp mood shift. A better than expected first round for right wing senator Flávio Bolsonaro in Brazil, along with a clear pullback from a potential Monzo takeover, helped light a fire under the stock.
Nu Holdings has shifted from a year-to-date share price return that is down 8% to a punchy 27% 7 day share price gain and a 17% 90 day share price return. The 1 year total shareholder return of 3.5% sits against a much larger 3 year total shareholder return of about 2x, hinting that recent election and M&A headlines have reignited momentum rather than created it from scratch.
Scan how Nu Holdings compares with other fast moving digital finance stocks using our hand picked 19 high quality undiscovered gems.
Nu Holdings looks like a powerful business story, yet the latest election fueled jump leaves a tougher question. Are you paying up for quality, or still getting a fair entry point on the current numbers?
Most Popular Narrative: 31% Undervalued
Nu Holdings closed at $15.66, while the most followed narrative pegs fair value at $22.74 using a discounted cash flow approach. That gap frames the latest spike as a repricing of expectations rather than the end of a potential mispricing story.
The long-term vision, which CEO David Vélez refers to as the company’s “Act III,” is built around three pillars: deepening monetization in Brazil through high-margin products such as mortgages, private banking, and SME services in order to increase ARPAC from $16 to above $25; replicating the model in Mexico and Colombia until full profitability is reached; and preparing for expansion into the United States by leveraging the know-how accumulated across Latin America. At the same time, the planned investment of 45 billion Brazilian reais during 2026 (approximately $8.2 billion) signals an aggressive reinvestment commitment in AI, infrastructure, and segment expansion.
See why 99 investors see Nu Holdings as 31% undervalued.
Result: Fair Value of $22.74 (UNDERVALUED)
Still, Nu Holdings faces real pressure points if Brazil’s credit cycle worsens or the Brazilian real weakens sharply, as both could hit reported profitability.
Find out about the key risks to this Nu Holdings narrative.
Another View on Nu Holdings’ valuation
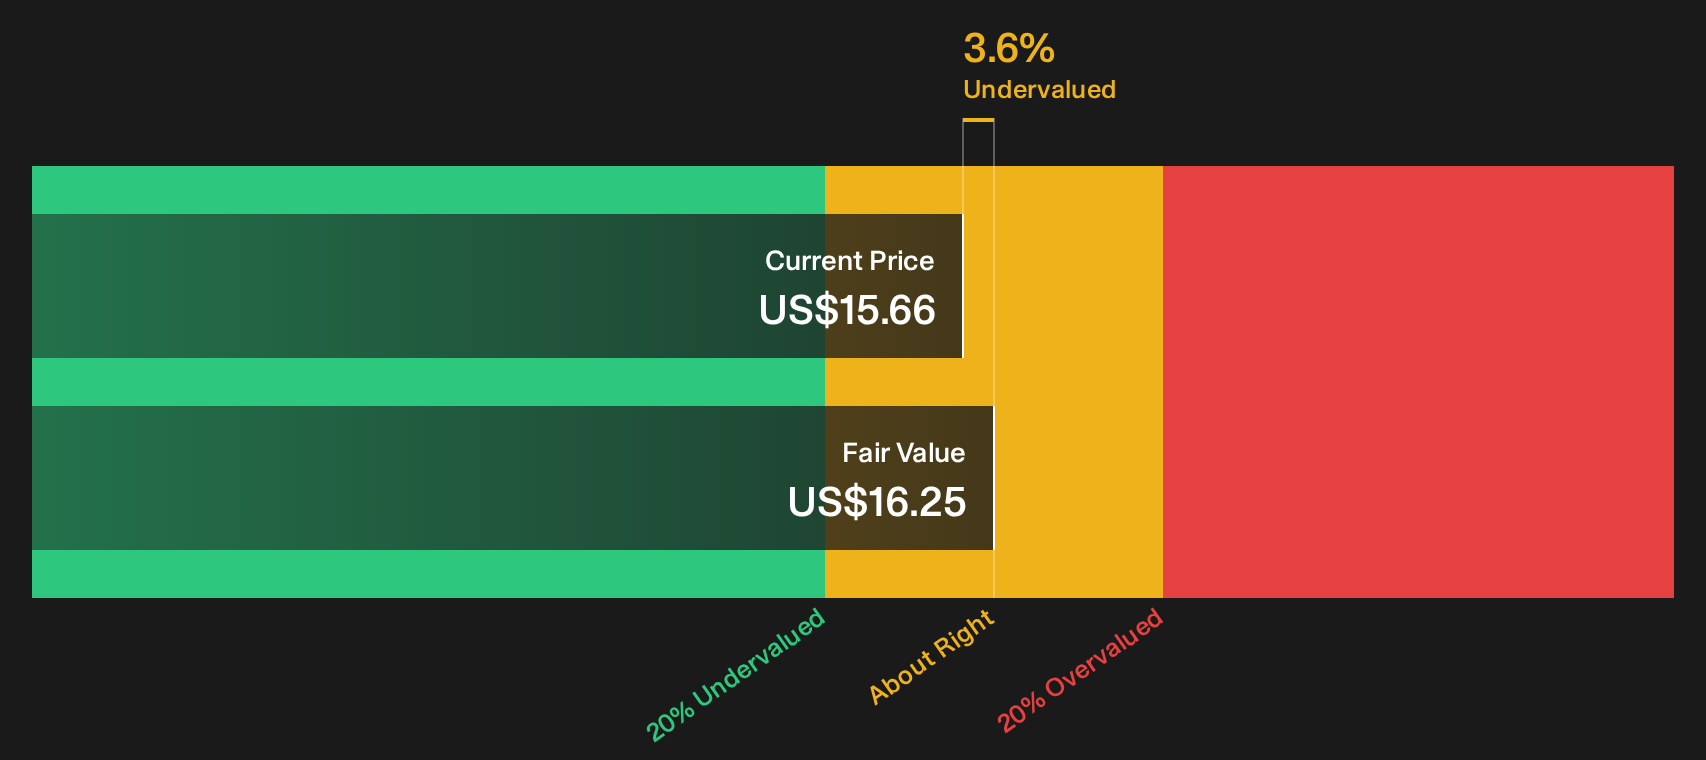
Nu Holdings screens as undervalued on a DCF lens, with the share price of $15.66 sitting about 3.6% below an SWS DCF fair value estimate of $16.25. That is a modest cushion, not a deep discount. For you, the real question is whether this narrow gap feels worth the earnings and credit risk being taken.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Nu Holdings can either sharpen your thinking or just add noise. Move quickly, check the full data, and weigh both sides through the 3 key rewards and 2 important warning signs.
Looking for more Nu Holdings style investment ideas?
If Nu Holdings has sharpened your thinking, do not stop here. Fresh opportunities keep surfacing, and missing them often comes down to not looking.
- Target quality at a discount by scanning companies that pair solid fundamentals with attractive pricing using the 27 high quality undervalued stocks.
- Prioritize sleep-at-night resilience by reviewing a 31 resilient stocks with low risk scores that focuses on businesses with more defensive profiles and lower risk scores.
- Hunt for under-the-radar potential with a list of solid balance sheet and fundamentals (25 results) that highlights companies combining sturdy finances with room for the story to develop.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com