


IMF chief Kristalina Georgieva has warned that record public debt and renewed inflation pressures are testing global growth, which puts a premium on companies that can fund expansion internally and whose leaders have substantial skin in the game. Fast growing Japanese businesses with hefty insider stakes fit that bill. This article highlights three such stocks from our screener and explains how their ownership profile and growth runway may appeal to long term investors.
The stocks below are just a small sample. The full screen surfaced 96 more fast growing businesses with high insider ownership and equally compelling stories that are not covered in this article. To identify and analyze the highest conviction ideas that match your own risk profile, head straight into the Fast Growing Stocks With High Insider Ownership screener.
HUMAN MADE (TSE:456A)
HUMAN MADE runs a multi brand apparel and lifestyle business, with its HUMAN MADE label directly aligned to the screener through fast growing online and retail sales of t shirts, hoodies, jackets and accessories. The group is valued at about ¥188b.
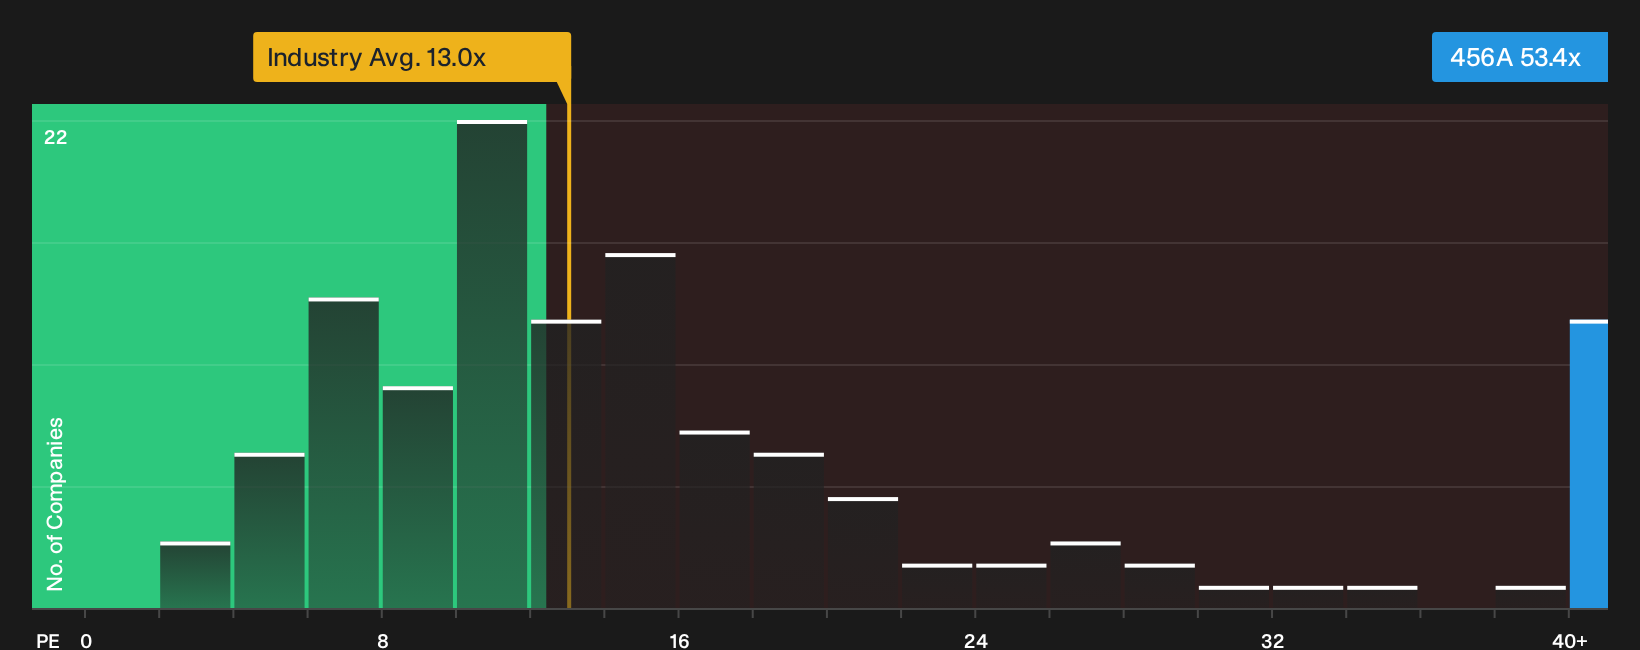
Revenue is forecast to rise about 26.5% a year, with earnings expected to compound near 28.7% and net margins around 20.6%. That growth story in e commerce driven fashion comes with a rich 53.4x P/E. As a result, future returns are likely to depend on how pressure on those margins plays out.
If you want to see how that premium P/E lines up against HUMANE MADE's growth runway and margin pressure, pull up the DCF valuation analysis for HUMAN MADE for the full picture.
Lasertec (TSE:6920)
Lasertec develops inspection and measurement gear for chipmakers, with its EUV mask and wafer inspection tools closely tied to fast growing advanced semiconductor nodes. The business generated ¥230.5b from this equipment line in FY2026 and has a market value of about ¥4.2t.
Lasertec links directly to the screener theme because its EUV inspection systems are integrated into advanced chip production, where customers often commit to long investment cycles. Forecast earnings growth near 19% a year and high forecast ROE around 33.9% reflect optimistic projections, although everything depends on how one unseen pressure on those growth assumptions plays out.
That hidden pressure point makes it worth pulling up the 1 key reward and 2 important warning signs (2 are major!) to evaluate where Lasertec’s growth story could accelerate or start to fray.

JX Advanced Metals (TSE:5016)
JX Advanced Metals develops copper and rare metal materials for electronics and semiconductor fabrication, with its semiconductor materials line plugging directly into fast growing chip demand. The group is valued at about ¥3.6t.
Earnings are forecast to rise about 13.2% a year, last year’s profit growth of 91.8% and ROE near 22.9% put JX Advanced Metals firmly in the fast growing, high quality bucket. However, everything depends on how one unresolved swing factor for its semiconductor materials economics plays out.
Those semiconductor swings could cut both ways, so pull up the 3 key rewards and 1 important major warning sign to see where JX Advanced Metals’ upside and pressure points may be quietly building.

Seeking Fresh Alternatives Before They Fly
Fresh opportunities move fast. By the time momentum headlines appear, early entry points may be gone and risk climbs. Scan these curated stock ideas while it matters and look for early entry opportunities.
- Explore resilient income by reviewing the 22 dividend fortresses, which focuses on companies that aim to maintain dividend payouts even when sentiment cools.
- Review early AI momentum through the 35 profitable AI stocks that aren't just burning cash, where cash-generating companies may have different risk characteristics than purely speculative names.
- Monitor infrastructure-related stocks using the 44 power grid technology and infrastructure stocks to identify companies involved in grid upgrades that may currently be less noticed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com