


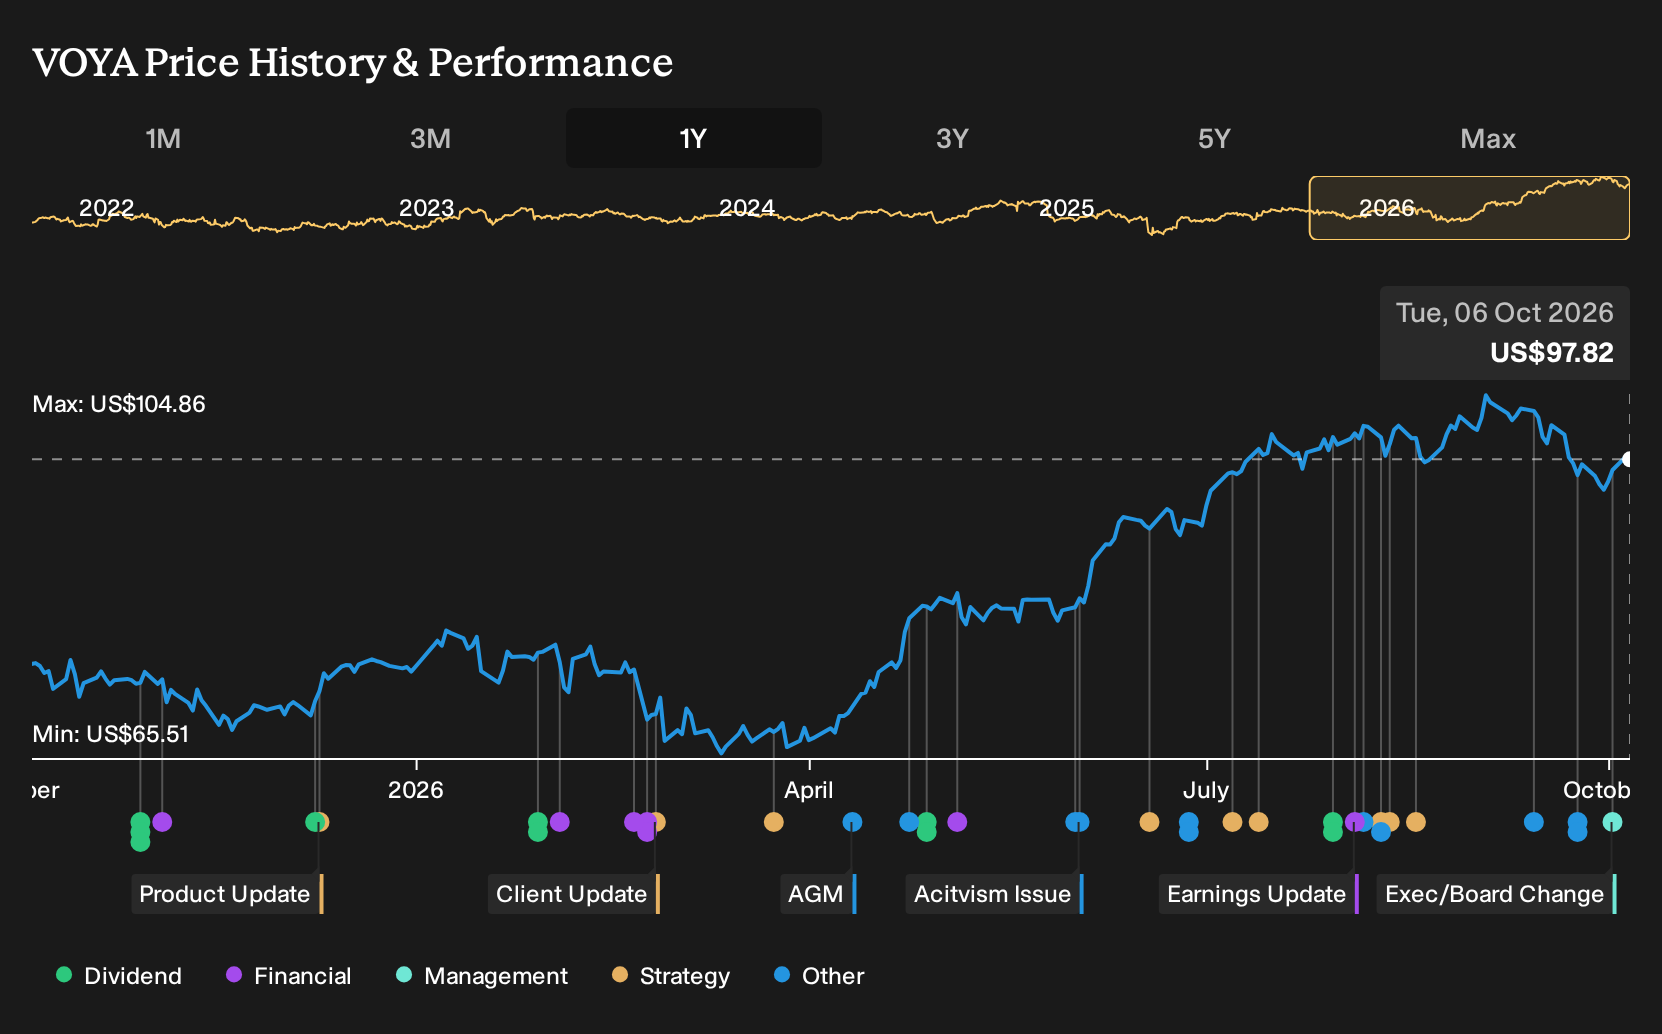
- Voya Financial has become the focus of an activist push after TOMS Capital filed definitive proxy materials and called for a non-binding shareholder vote expressing lack of confidence in the board and management, while also issuing a Section 220 books and records demand and updating its campaign website in late September 2026.
- This activism directly targets how Voya Financial is run. It can influence decisions on technology investment, risk oversight and capital allocation across its retirement, benefits and investment platforms.
- The focus now turns to how Voya Financial's workplace-centric investment narrative holds up against TOMS Capital's confidence vote campaign and governance challenge.
Scan how Voya Financial fits alongside other insurers facing governance and risk questions by lining it up against our hand picked 31 resilient stocks with low risk scores.
Voya Financial Investment Narrative Recap
To own Voya Financial, you need to believe its workplace-focused retirement, benefits and investment engine can keep converting employer relationships into fee and premium income, while keeping earnings volatility from alternatives and medical stop loss in check. The biggest near term catalyst remains execution on this ecosystem, especially wealth and investment flows, rather than the activist campaign itself.
The main risk right now is that governance noise and any further earnings misses weaken confidence just as the business leans on external borrowing and a relatively low 9.5% return on equity. If the activism stays contained to a non binding vote and engagement, the direct operational impact looks limited for now.
The board’s decision to expand Santhosh Keshavan’s remit to Chief Risk and Global Operating Officer from January 2027, while appointing Rajat Kalia as Chief Technology Officer, matters directly for this story. Voya Financial is leaning on AI, automation and digital onboarding to improve margins, so how risk and operations are stitched together at the top will shape execution quality.
For you as a shareholder or prospective investor, this reshuffle sits alongside the TOMS Capital campaign as a live test of governance and oversight. A clearer risk lead over enterprise technology and operations could help the firm manage alternative investment swings, stop loss underwriting and high leverage, which all sit close to the key earnings and valuation catalysts.
Voya Financial's current analyst script points to about US$8.5b in revenue and US$1.1b in earnings by 2029, based on a 1.4% yearly rise in revenue and an earnings increase of roughly US$533m from US$567.0m today.
Uncover why Voya Financial's fair value indicates a 10% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
For Voya Financial, the alternate view focuses on Stop Loss pricing risk. The most bearish analysts were already assuming only 1.1% yearly revenue growth to about US$8.4b and a lower 8.2x P/E on US$1.1b earnings by 2029. With activism and new risk leadership now in play, those expectations may shift again, in either direction.
Explore another Voya Financial fair value estimate, including one that suggests it could be worth just $99.75.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Voya Financial research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Voya Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Voya Financial's overall financial health at a glance.
Looking For More Investment Ideas Beyond Voya Financial?
If the Voya Financial story has you thinking about portfolio gaps, it can help to line it up next to other stocks with very different risk, income and quality profiles.
- For investors chasing under-the-radar potential, scan through 19 high quality undiscovered gems that pair resilient fundamentals with cleaner earnings profiles.
- If income is the priority, compare Voya Financial with a set of higher yielding payers by reviewing our 8 dividend fortresses that focus on stronger, more consistent distributions.
- To put capital preservation first, weigh Voya Financial against our curated 31 resilient stocks with low risk scores which concentrates on businesses screened for sturdier balance sheets and lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com