


- Coca-Cola reported strong Q2 results with 7% revenue growth, 5% unit case volume gains and raised full-year guidance, backed by higher free cash flow coverage of its dividend.
- The business leaned heavily on volume-led demand for its flagship brand, supported by new zero-sugar and functional drinks that respond to GLP-1 driven health trends.
- This article examines how Coca-Cola's investment narrative aligns with this volume-led Q2 momentum and higher full-year outlook.
Coca-Cola Investment Narrative Recap
To be comfortable owning Coca-Cola, you need to believe the business can keep pairing everyday beverage demand with disciplined brand extensions, even as health concerns and GLP 1 drugs reshape habits. The short term swing factor is whether volume led growth and revenue management continue to offset refranchising headwinds and soft spots in consumer spending.
The appointment of Rob Gehring to lead North America looks important but not transformational by itself. Execution on pricing, packaging and product mix in that region remains the key near term catalyst. The bigger risk still sits with potential regulatory pressure on sugar sweetened drinks and any sustained pullback in higher calorie beverages.
The most relevant recent thread for this leadership change is Coca-Cola leaning harder into zero sugar and functional drinks, including prebiotic offerings and fairlife expansion. North America is central to that shift. A seasoned operator with experience at Monster, Hershey and Swire Coca-Cola now has direct responsibility for how that portfolio lands with retailers and shoppers.
For you, the question is whether this management move improves the odds that Coca-Cola executes cleanly on its current playbook. The priorities are clear. Keep volume growth healthy, manage the refranchising drag, and stay ahead of health trends while GLP 1 usage and regulation keep evolving. That execution record will likely matter more than any single quarter’s headlines.
Coca-Cola Through The Analyst Lens
Coca-Cola's narrative projects US$53.4b in revenue and US$17.0b in earnings by 2029. This implies forecast revenue growth of 2.1% per year and an earnings increase of about US$2.7b from earnings of US$14.3b today.
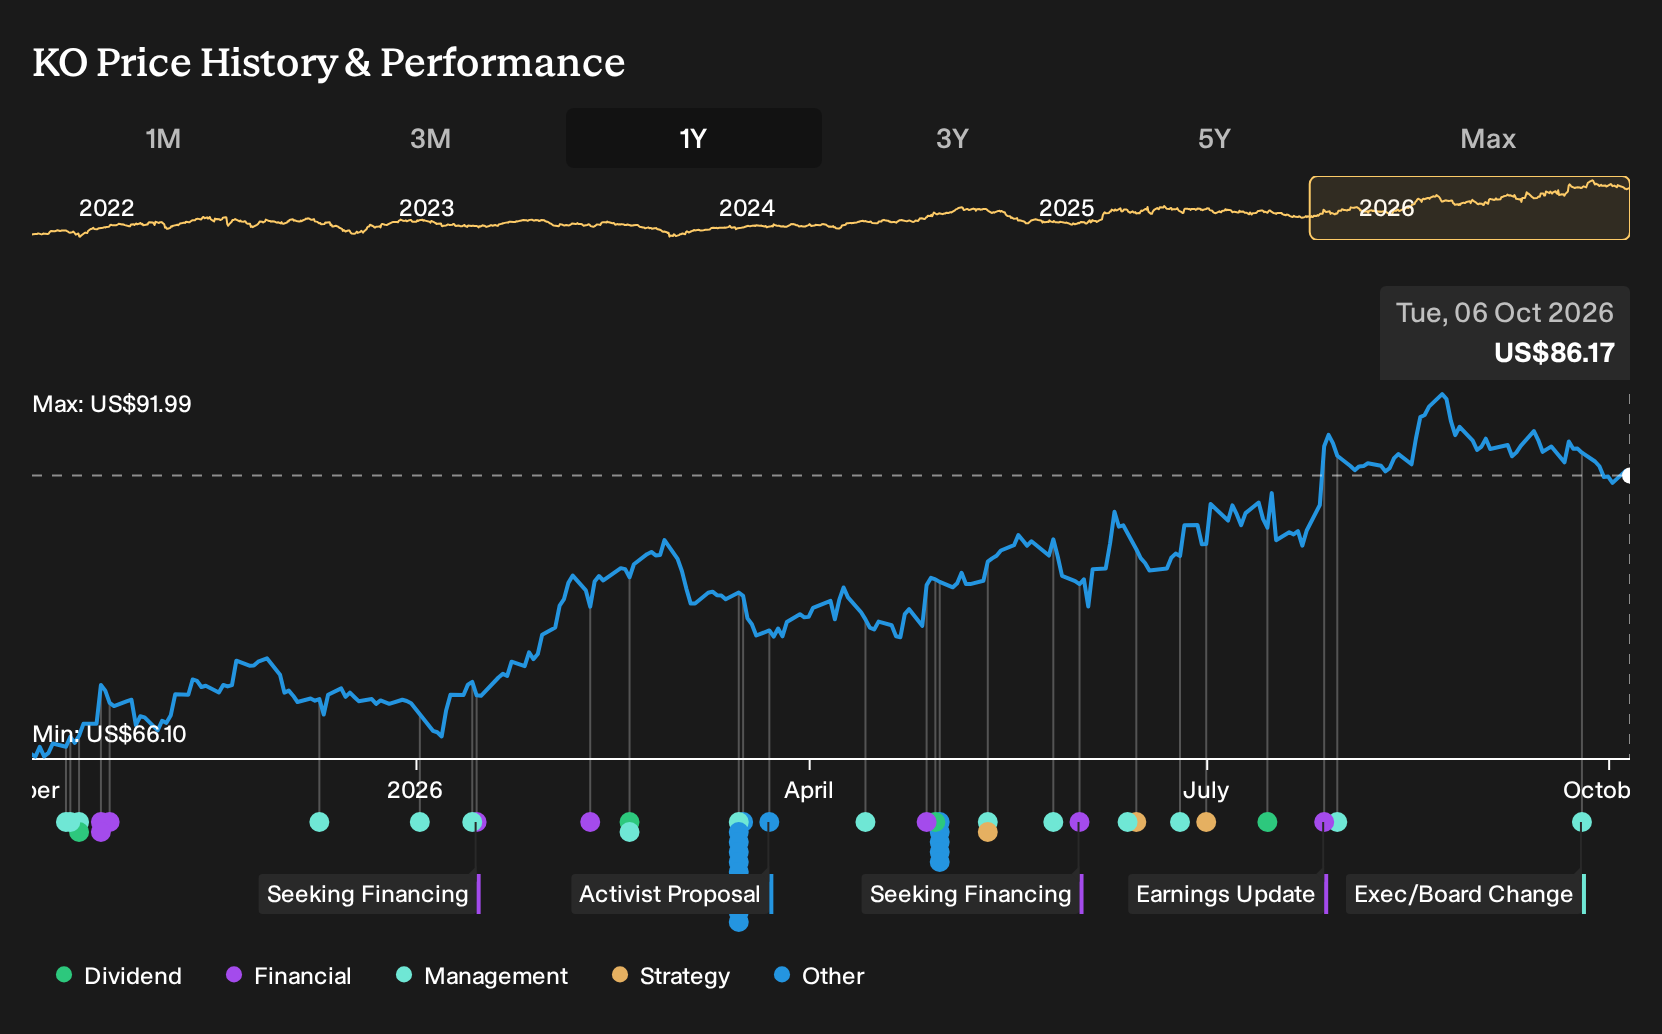
Uncover how Coca-Cola's fair value indicates a 10% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
Ten fair value estimates from the Simply Wall St Community cluster between US$66.20 and about US$94.65, so private investors are split on how far Coca-Cola should trade above or below current levels. Layer in the risk of tighter sugar rules or a stronger push into functional drinks, and you get very different earnings paths. Use this diversity of views as a prompt to test your own assumptions and explore multiple angles before deciding where Coca-Cola fits in your portfolio.
Explore 9 other Coca-Cola fair value estimates, including one that suggests as much as 10% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Coca-Cola research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Coca-Cola. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Coca-Cola's overall financial health at a glance.
Looking for more Coca-Cola style investment ideas?
If Coca-Cola's blend of durable demand and cash generation appeals to you, it can help to widen the lens and scan for other businesses with traits that fit your risk and income preferences. The Simply Wall St Screener lets you filter for fundamentals that match your playbook rather than chasing headlines.
- For investors who want resilient balance sheets and steady fundamentals, start with a list of solid balance sheet and fundamentals (25 results). This can help anchor the more defensive side of your holdings.
- If your focus is on quality at a sensible entry point, use the 27 high quality undervalued stocks to find companies where fundamentals and price are not fully aligned.
- When reliable income is the priority, scan for a stream of cash returns using the 8 dividend fortresses as a shortlist of ideas to research further.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com