


- Hormel Foods, through its SKIPPY brand, has already launched SKIPPY Peanut Butter Chocottone in partnership with Bauducco, adding a new peanut butter driven twist to Bauducco's seasonal sweet loaf lineup alongside a Pistachio Chocottone flavor.
- The Bauducco collaboration gives Hormel Foods another branded platform for SKIPPY in holiday gifting and sharing occasions, which can matter for mix, shelf space, and how effectively the business turns brand equity into higher value product formats.
- Next, we will examine how this SKIPPY Chocottone collaboration could shape Hormel Foods' broader investment narrative around branded protein.
Hormel Foods Investment Narrative Recap
For Hormel Foods, a key belief is that branded protein and snacks can support steadier earnings as the portfolio leans into value added products, foodservice channels and mix improvement. The SKIPPY Chocottone launch fits that story, but its financial impact looks modest compared with larger factors such as Brakebush integration, cost discipline and pricing execution.
The main near term swing factor is whether Hormel Foods can protect margins while managing still elevated freight and commodity costs after a period of weaker net profit margins. The biggest risk remains a combination of volatile pork, beef and nut prices and any consumer pushback if further pricing is required.
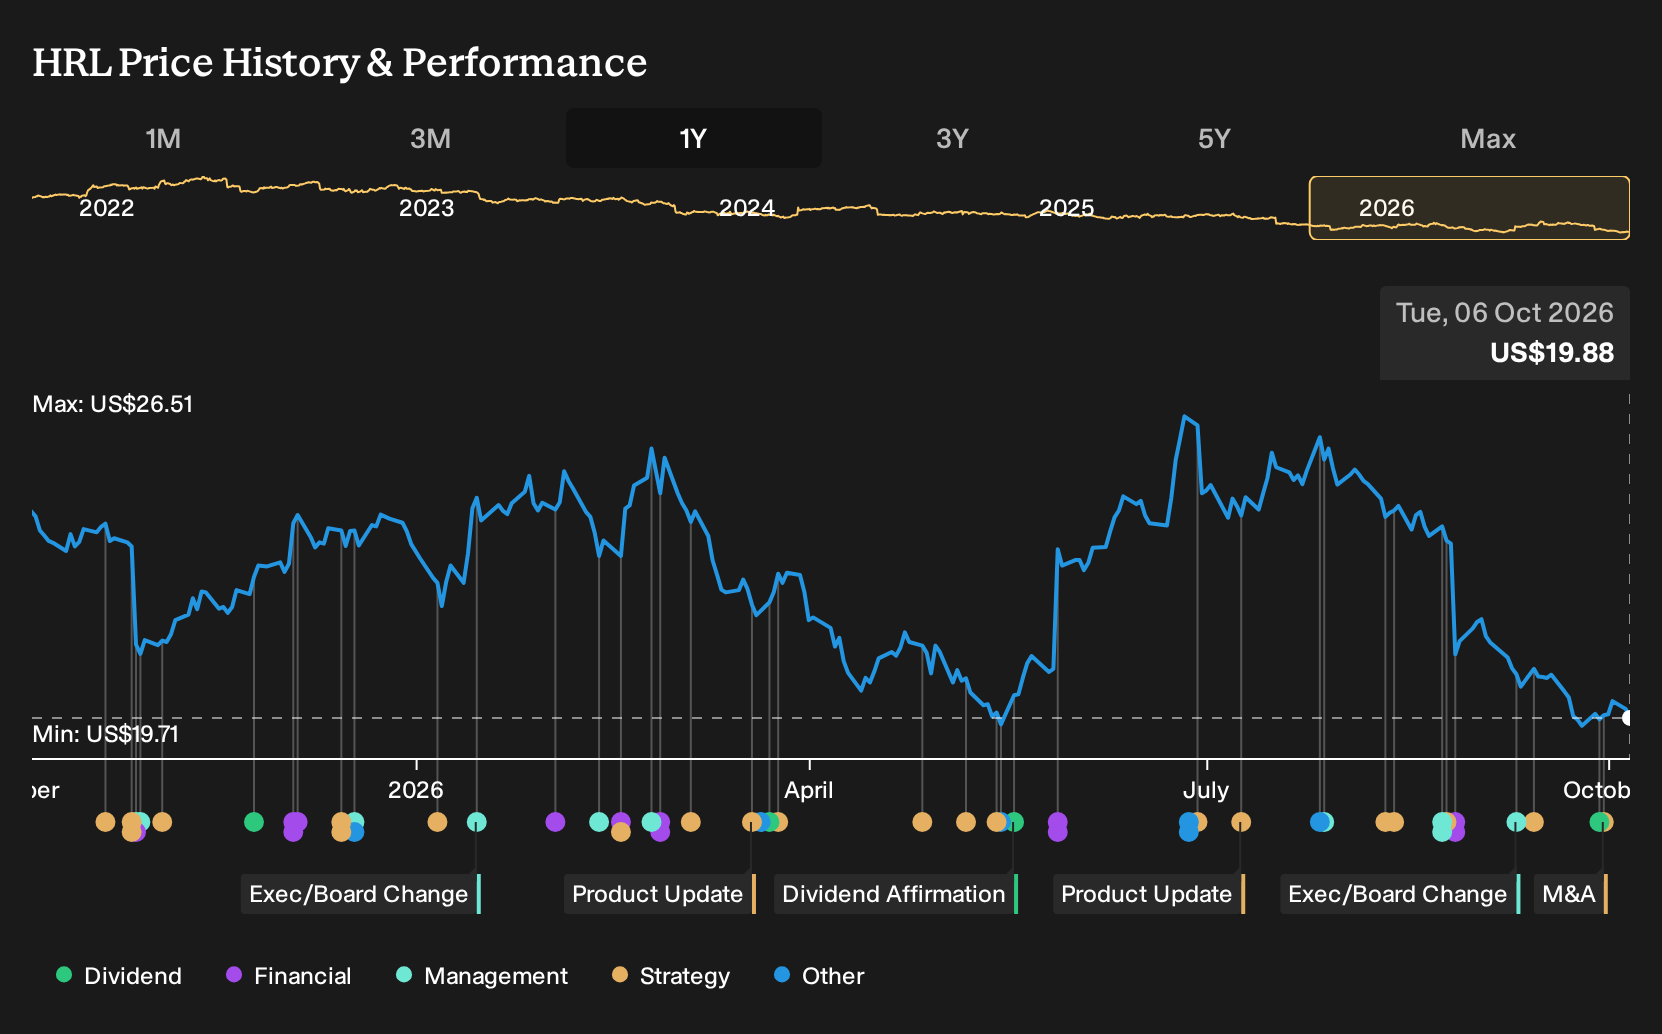
The most relevant recent update is the plan to acquire Brakebush, a value added chicken producer that would increase Hormel Foods' exposure to foodservice and higher margin poultry. This represents a different kind of mix shift than SKIPPY Chocottone, but both point toward more products where brand power and preparation can support higher pricing.
For you as a shareholder, the link between Brakebush and SKIPPY seasonal items is execution. Hormel Foods now needs to absorb a sizeable US$1.2 billion revenue acquisition, continue integrating prior divestitures and still deliver on brand led product launches. Any stumble in foodservice demand or integration would likely have a greater effect on results than the performance of a single holiday loaf.
Hormel Foods' narrative projects US$13.3b revenue and US$909.4m earnings by 2029. This assumes 3.2% yearly revenue growth and an earnings increase of about US$566.7m from current earnings of US$342.7m.
Discover why Hormel Foods' fair value points to a 30% potential upside from its current price, which could materialize sooner than many investors anticipate.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$25.94 to US$48.48 per share, indicating very different views on Hormel Foods. Some members focus on catalysts such as the Brakebush deal, SKIPPY Chocottone and the affirmed dividend, while others worry about commodity costs and foodservice demand. Explore these contrasting viewpoints before forming your own stance.
Explore 2 other Hormel Foods fair value estimates, including one that suggests it could be worth just $25.94!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Hormel Foods research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Hormel Foods. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hormel Foods' overall financial health at a glance.
Looking for more Hormel Foods style investment ideas?
Hormel Foods shows how brand strength and product extensions can reshape where earnings come from. If you want to apply that same lens across the market, the Simply Wall St Screener can help you quickly narrow the field to companies that fit your preferred mix of quality, value and resilience.
- For investors who care about steady balance sheets as much as headlines, start with a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without stretching finances.
- If you want to tilt toward quality at a reasonable entry point, look across a 27 high quality undervalued stocks that combine fundamentals with prices that do not fully reflect them.
- If you prefer to focus on resilience first and upside second, especially when markets feel noisy, then filter for a 31 resilient stocks with low risk scores that may offer a smoother ride.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com