


Key Points
MercadoLibre has held its own as the leader in e-commerce in Latin America.
The company is also a leading financial technology provider.
If you believe profit margins will start expanding, the stock looks very cheap at these prices.
Amazon and Sea Limited are two e-commerce platforms that have sought to expand into many global markets. However, in Latin American markets like Mexico and Brazil, neither has been able to dethrone the leading e-commerce and financial technology (fintech) platform in the region: MercadoLibre (NASDAQ: MELI).
The $94 billion market cap giant is growing incredibly quickly and gaining share of commerce transactions across Central and South America. Here's why this Latin American dominance can lead to strong returns for the stock in the coming years.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Growing online shopping penetration
When it comes to payment volume penetration, MercadoLibre has an estimated 25% market share of e-commerce sales across its major operating countries, including Brazil, Mexico, and Argentina. With e-commerce as a percentage of overall retail sales smaller than in the United States, there should be a nice tailwind that lifts MercadoLibre's e-commerce sales in the years ahead.
Gross merchandise volume (GMV) grew 36% in constant currency to $21.9 billion last quarter, with strong growth across all its operating countries. It can grow so quickly because of its enviable product offering, with a wide selection and fast delivery times. Like Amazon, it has a subscription service called Meli+, and is beginning to monetize through advertisements.
Advertising is especially promising, with MercadoLibre estimating it now holds 10% market share in digital advertising in Latin America, up 62% year over year last quarter.
Image source: Getty Images.
Financial services arm
MercadoLibre also differentiates itself from e-commerce competitors by layering on its own fintech services, which are a moneymaker and also reinforce the power of its shopping advantages.
This comes in the form of Mercado Pago, which is a spending wallet for shoppers. It offers loans for purchases, among other services, and has recently launched a push to introduce its own credit card to drive everyday spending and even more shopping on MercadoLibre. Credit card users are 2 to 3 times more likely to use both MercadoLibre's marketplace and fintech tools than other MercadoLibre users.
For merchants, Mercado Pago offers payment processing, both on MercadoLibre and off-platform with retail payment terminals. Acquiring payment volume off-platform was $64 billion last quarter, up 44% year over year.
Total financial services revenue was $4.4 billion last quarter, and grew 47% year over year in constant currency. Not only is MercadoLibre one of the fastest-growing e-commerce platforms, but it is also a dominant force in fintech in Latin America.
MELI Revenue (TTM) data by YCharts
Betting on the leading commerce provider in Latin America
MercadoLibre's stock is down due to fears of margin compression. The company's operating margin was 6.7% last quarter, translating to just $683 million in earnings.
Management is purposefully driving down margins in the short term for two main reasons. First, it is investing ahead to increase its e-commerce infrastructure, allowing it to now offer rapid free shipping on most items on its marketplace (depending on where shoppers live, of course). Second, it is pushing to get more and more Mercado Pago credit cards into shoppers' hands, which comes with an upfront expense tied to estimated losses from the average client.
But MercadoLibre's profit margin should start expanding again. Since it has a large percentage of its business coming from fintech, I think it is plausible that MercadoLibre's consolidated operating margin can sustainably reach 15%. This is higher than Amazon's e-commerce division, but Amazon doesn't have a massive fintech arm with high margins.
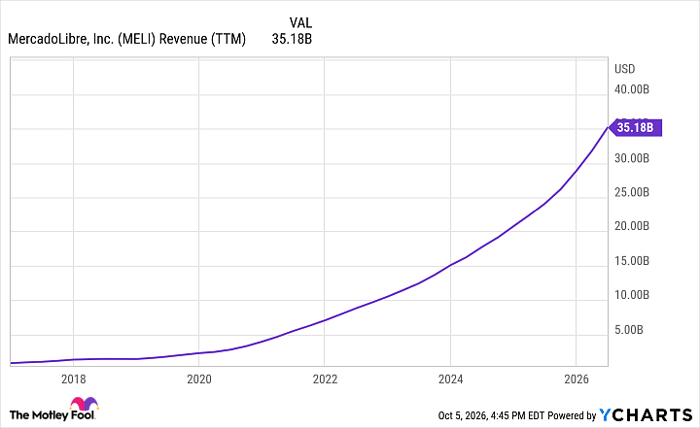
MercadoLibre's trailing revenue is $35 billion, but it grew by 43% in constant currency as of last quarter, meaning revenue won't stay in this area for long. If revenue doubles to $70 billion within the next few years and profit margins revert to 15%, MercadoLibre should generate $10.5 billion in operating earnings, or less than 10 times its current market cap of $94 billion. This makes the stock a nice buy at today's prices.
Brett Schafer has positions in MercadoLibre. The Motley Fool has positions in and recommends Amazon, MercadoLibre, and Sea Limited. The Motley Fool has a disclosure policy.