


Millicom International Cellular (TIGO) moved back into focus after Zacks highlighted a 35.4% rise in its consensus earnings estimate over the past two months, along with a Zacks Rank #1 and a 3.3% dividend yield.
Recent trading has cooled slightly, with the share price down 4.6% over the past 30 days and 3.9% over 90 days. Millicom International Cellular still carries a 60% year to date share price return and a very large 3 year total shareholder return, which points to momentum that has been strong over a longer stretch, even as investors reassess expectations in the short term following the sharp upgrade to earnings forecasts.
Scan beyond Millicom International Cellular and see how other income and quality plays are setting up in the current market using our curated 27 high quality undervalued stocks.
Millicom International Cellular has put up the kind of returns and earnings revisions that suggest a solid telecom platform in Latin America. The open question is whether that recent optimism already fully sits in the current valuation.
Most Popular Narrative: 8% Undervalued
Set against Millicom International Cellular's last close of $90.46, the most followed narrative anchors fair value at $98.39, framing today’s price as a discount that hinges on cash generation and balance sheet repair actually materialising.
The current valuation implies that Millicom shares are trading very strongly and at levels some reports describe as well above estimated intrinsic value, yet this narrative still treats the stock as undervalued and assumes the market is underpricing the durability of its cash generation and balance sheet repair.
See why 19 investors see Millicom International Cellular as 8% undervalued.
Result: Fair Value of $98.39 (UNDERVALUED)
Still, heavy net debt of about US$8.1b and ongoing legal claims and provisions could pressure Millicom International Cellular’s cash generation story if sentiment turns.
Find out about the key risks to this Millicom International Cellular narrative.
Another View on Millicom International Cellular’s Valuation
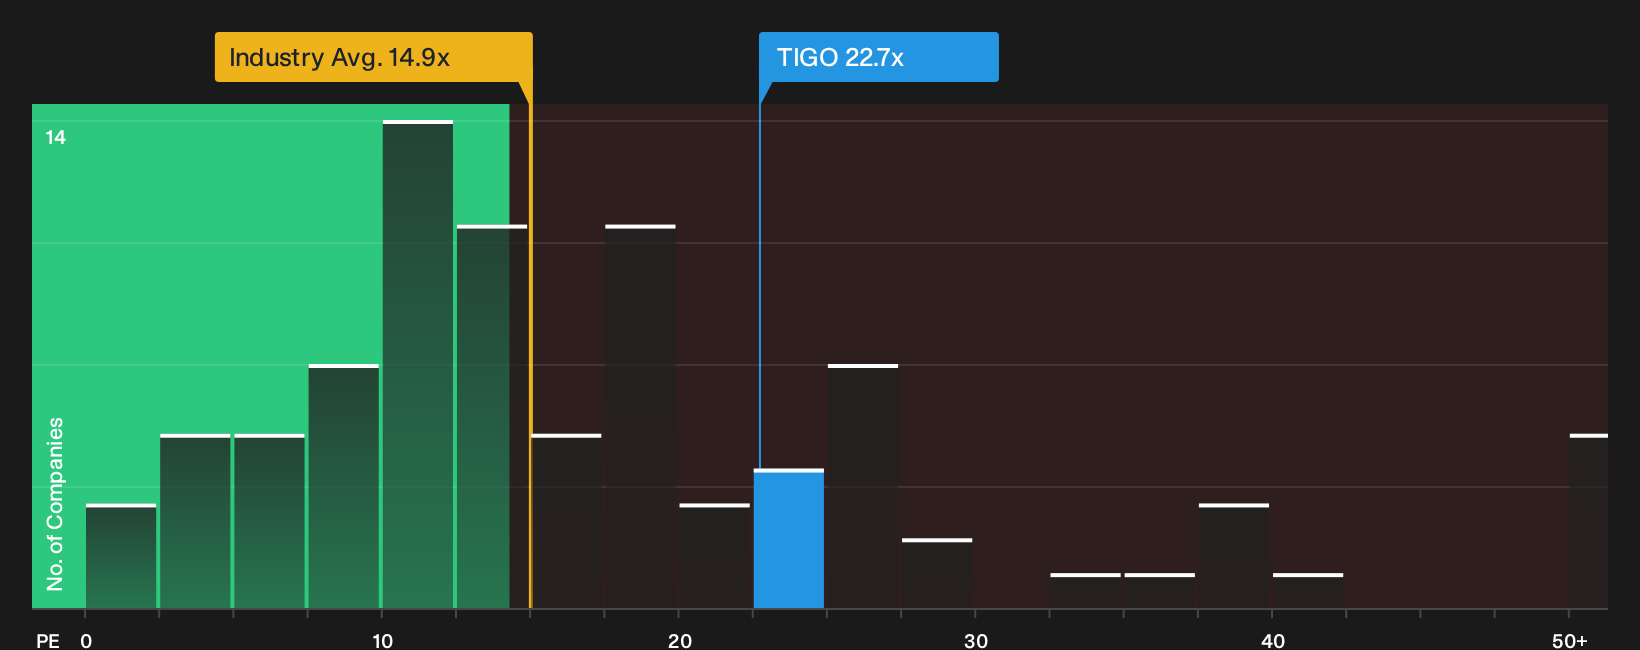
The earlier narrative leans heavily on future cash flows and a fair value estimate of $98.39, yet the current P/E of 22.7x tells a slightly different story. It sits above the Global Wireless Telecom average of 15x and even edges past the 22.6x fair ratio. That gap suggests less room for error if growth or cash generation disappoints, so which signal do you trust more?
For a closer look at how this valuation gap could close in either direction, including how the fair ratio might act as a magnet over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Millicom International Cellular's valuation can create both hesitation and opportunity, so move quickly to test the numbers and shape your own conclusion with the 2 key rewards and 3 important warning signs
Looking for more ideas beyond Millicom International Cellular?
If Millicom International Cellular has you rethinking your watchlist, do not stop there. Use this moment to widen your opportunity set before the next move passes you by.
- Target potential upside in overlooked corners of the market by scanning a curated pool of 19 high quality undiscovered gems that already show strong underlying fundamentals.
- Strengthen your defense by reviewing a 31 resilient stocks with low risk scores that focuses on resilient balance sheets and steadier risk profiles when conditions change fast.
- Prioritize quality and financial robustness by building your shortlist around a list of solid balance sheet and fundamentals (25 results) that filters for stronger fundamentals from day one.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com