


A fresh legal challenge is now front and center for Vail Resorts (MTN). On October 6, a shareholder filed a derivative suit alleging that executives allowed horizontal price fixing, which raises questions about antitrust exposure and governance risk.
Vail Resorts shares have been volatile around the latest headlines, with a 1-day share price return of 4.24% and a 30-day gain of 7.59% lifting the stock to $145.20. However, the 5-year total shareholder return has declined 47.19%, indicating that long-term momentum has faded despite a modest 1-year total shareholder return of 1.70%.
Spot opportunities beyond Vail Resorts by scanning a hand picked set of resilient businesses in our 31 resilient stocks with low risk scores that may better match your risk comfort.After a sharp bounce on legal headlines and only a small 1-year gain, the question for Vail Resorts now is simple. Has most of the upside already played out, or does the valuation still leave meaningful room ahead?
Most Popular Narrative: 1% Overvalued
On the most followed narrative, Vail Resorts screens only slightly above its inferred fair value of about $143.85 against a last close of $145.20. The bigger question becomes what has to go right in the story to justify that small premium.
The analysts have a consensus price target of $143.85 for Vail Resorts based on their expectations of its future earnings growth, profit margins and other risk factors. However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $191.0, and the most bearish reporting a price target of just $117.0.
See why 10 investors see Vail Resorts as 1% overvalued.
Result: Fair Value of $143.85 (OVERVALUED)
Still, the narrative can unravel if weaker destination visitation persists or if currency swings hit Vail Resorts earnings harder than analysts currently factor in.
Find out about the key risks to this Vail Resorts narrative.
Another View on Vail Resorts Valuation
On one hand, analyst targets place Vail Resorts at about fair value around $143.85. On the other, the SWS DCF model points to a future cash flow value of $207.76, which implies the shares trade at a steep discount. Which framework do you trust when the gap is this wide?
Look into how the SWS DCF model arrives at its fair value.
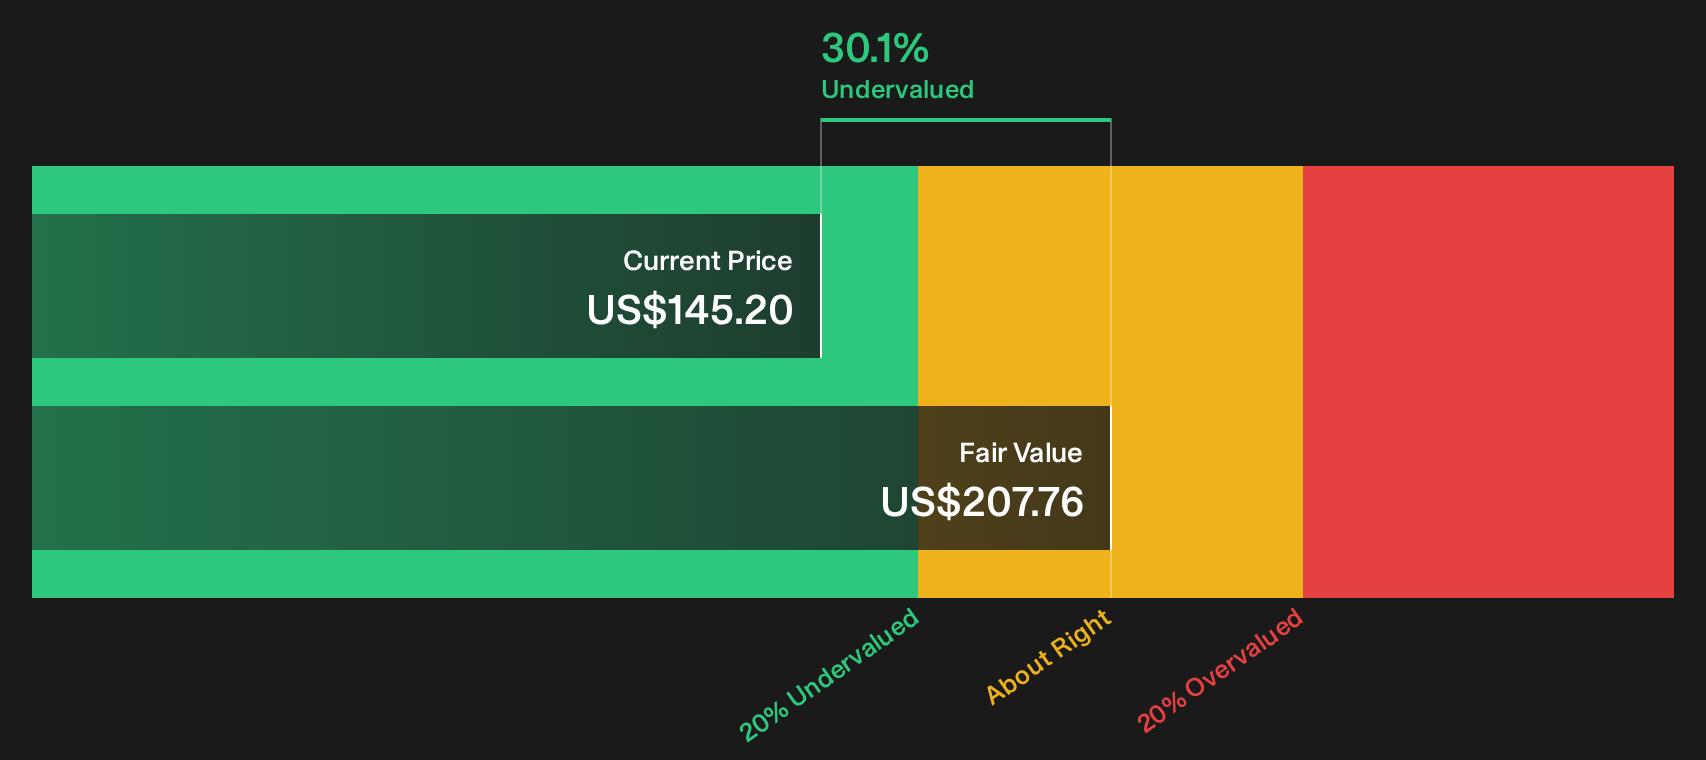
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Vail Resorts for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Vail Resorts can feel confusing, so move quickly, look through the underlying data yourself, weigh the concerns against the upside, then judge the 2 key rewards and 3 important warning signs
Looking for more Vail Resorts investment ideas?
If Vail Resorts has your attention, do not stop here. Push further, compare it with other opportunities, and let the data help you spot what the market is overlooking.
- Target quality at a discount by scanning companies that appear mispriced on fundamentals using the 27 high quality undervalued stocks.
- Focus on staying power by reviewing a list of solid balance sheet and fundamentals (25 results) that can better handle shocks and still fund growth.
- Look for earlier-stage opportunities by combing through 19 high quality undiscovered gems that strong fundamentals highlight before wider attention catches up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com