


Rocket Lab has ridden a remarkable share price run over the past few years, with fresh contract wins keeping the story in the headlines. The immediate question for anyone looking at the stock today is whether that price now lines up with what its cash flows can support.
- Over the past 3 years the stock has delivered a very large gain of about 13x. That puts a lot of weight on whether the current valuation can be supported by the cash the business is expected to generate.
- A record 20 launch deal with Synspective, plus a Neutron contract with Kepler Communications, can shift expectations for future revenue timing and capital needs. This feeds directly into any cash flow based valuation of Rocket Lab.
- What if you looked at Rocket Lab through its book value instead? See why Rocket Lab's 12.3x P/B tells a different valuation story.
The issue now is whether Rocket Lab's current US$71.92 share price is justified by its cash flows when measured against an intrinsic value estimate using a Discounted Cash Flow (DCF) approach.
If this jump in Rocket Lab's valuation has you rethinking where cash flows really line up with price, broaden the lens with 27 high quality undervalued stocks.
Is Rocket Lab Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) model here looks at what Rocket Lab’s future cash generation could be worth in today’s money. Latest twelve month free cash flow shows an outflow of about $370.5 million, so the whole setup rests on a sharp swing from cash burn to cash generation over the coming decade rather than on current profitability.
Analysts and model extensions are projecting free cash flow to move into positive territory and then grow, with estimates reaching hundreds of millions of $ per year within the 2030s. That kind of curve implies a recovering and then growing cash profile that needs consistent execution on launches, spacecraft services, and Neutron build out to hold up. The projected intrinsic worth from those cash flows currently sits substantially above the traded price of $71.92, because the record 20 launch agreement with Synspective adds longer term visibility but the market is still treating Rocket Lab as a high risk cash burner. Find out what Rocket Lab could be worth using our Discounted Cash Flow (DCF) estimate.
The Rocket Lab Narrative: What Would Justify Today's Price?
Narratives for Rocket Lab sit between the DCF puzzle and what would need to happen in the real world for the story to justify a higher or lower price. They spell out which paths for growth, margins and earnings would support different outcomes, and each one anchors a fair value to a specific mix of potential catalysts and risks, so you can track which version of Rocket Lab's future seems to be unfolding.
Community views on Rocket Lab are split between a wide runway ahead and a valuation that already reflects much of that potential.
Bull case: 26% undervalued
"Rocket Lab USA seeks to vertically integrate itself throughout the $800 billion space 'backbone' in order to attract the customers operating within that $1 trillion top component of the 'space economy'..."
Discover why this Narrative puts Rocket Lab at 26% undervalued.
Bear case: 343% overvalued
"The entire valuation is 'priced for perfection,' which means any delay causes volatility..."
Explore why this Narrative puts Rocket Lab at 343% overvalued.
One more Rocket Lab check that sits outside the cash flow story
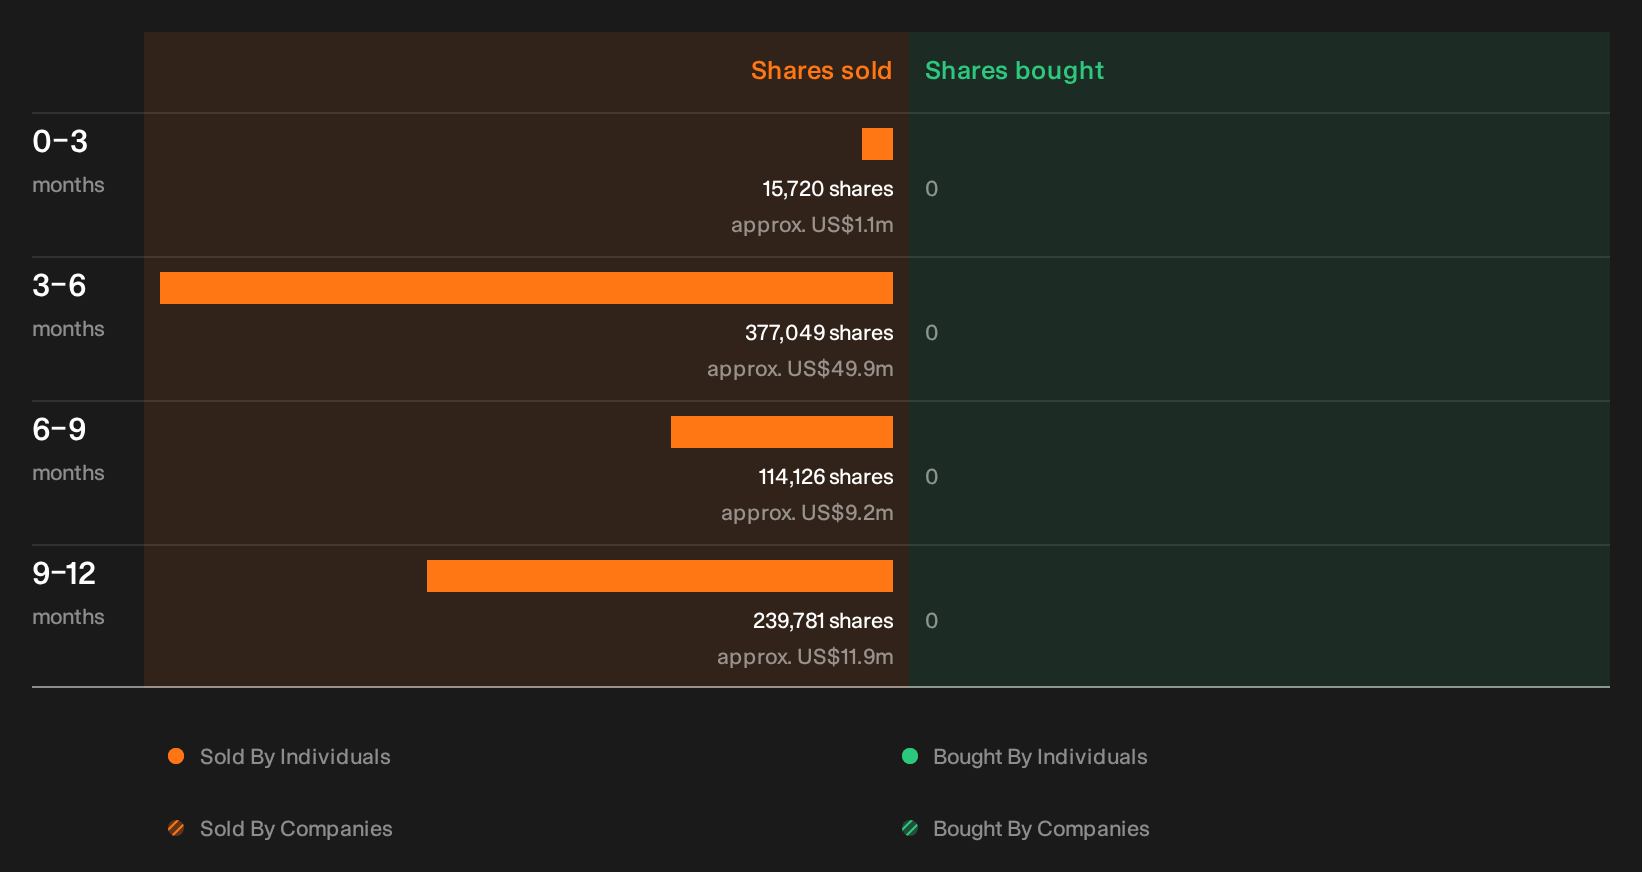
Price, contracts and cash projections only tell part of the story for Rocket Lab, because recent insider trades add another layer that investors often watch closely. The specific sellers, size of transactions and possible read throughs sit inside one more check. See the recent insider selling flagged for Rocket Lab.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com