


PSP Swiss Property (SWX:PSPN) has drawn fresh attention after recent share performance, with the stock down about 3% over the past month and modestly lower over the past 3 months.
At around CHF142.10, PSP Swiss Property’s share price has slipped over the past month and quarter, while the year-to-date share price return is only slightly lower. However, the 1-year and 5-year total shareholder returns of 7.98% and 44.07% point to a steadier longer-term payoff, suggesting that recent weakness reflects a softening in near-term momentum rather than a clear break in the broader shareholder return story.
Scan beyond PSP Swiss Property and compare its recent pullback with a curated group of income and quality-focused real estate peers using our 170 dividend fortresses.
PSP Swiss Property has delivered solid long-term returns, yet the recent slip toward CHF142.10 puts the focus on something different. Are investors still paying a fair price for that quality profile today?
Most Popular Narrative: 9% Overvalued
Against a last close of CHF142.10, the most followed narrative anchors PSP Swiss Property’s fair value at CHF130, implying a valuation premium that leans on bearish assumptions for earnings power and rental income.
The recent valuation gains of CHF 112 million and broadly based value appreciation in central Zurich and Geneva concentrate a large share of balance sheet strength in premium locations. These locations could face slower rental growth if demand normalises in core CBD markets, which in turn may cap future revaluation driven earnings and equity returns.
See why 0 investors see PSP Swiss Property as 9% overvalued.
Result: Fair Value of CHF130 (OVERVALUED)
Still, that bearish fair value view can be challenged if PSP Swiss Property sustains healthy letting progress and vacancy near 3.5%, or if Moody’s upgrade meaningfully improves funding costs.
Find out about the key risks to this PSP Swiss Property narrative.
Another View: PSP Swiss Property Through The P/E Lens
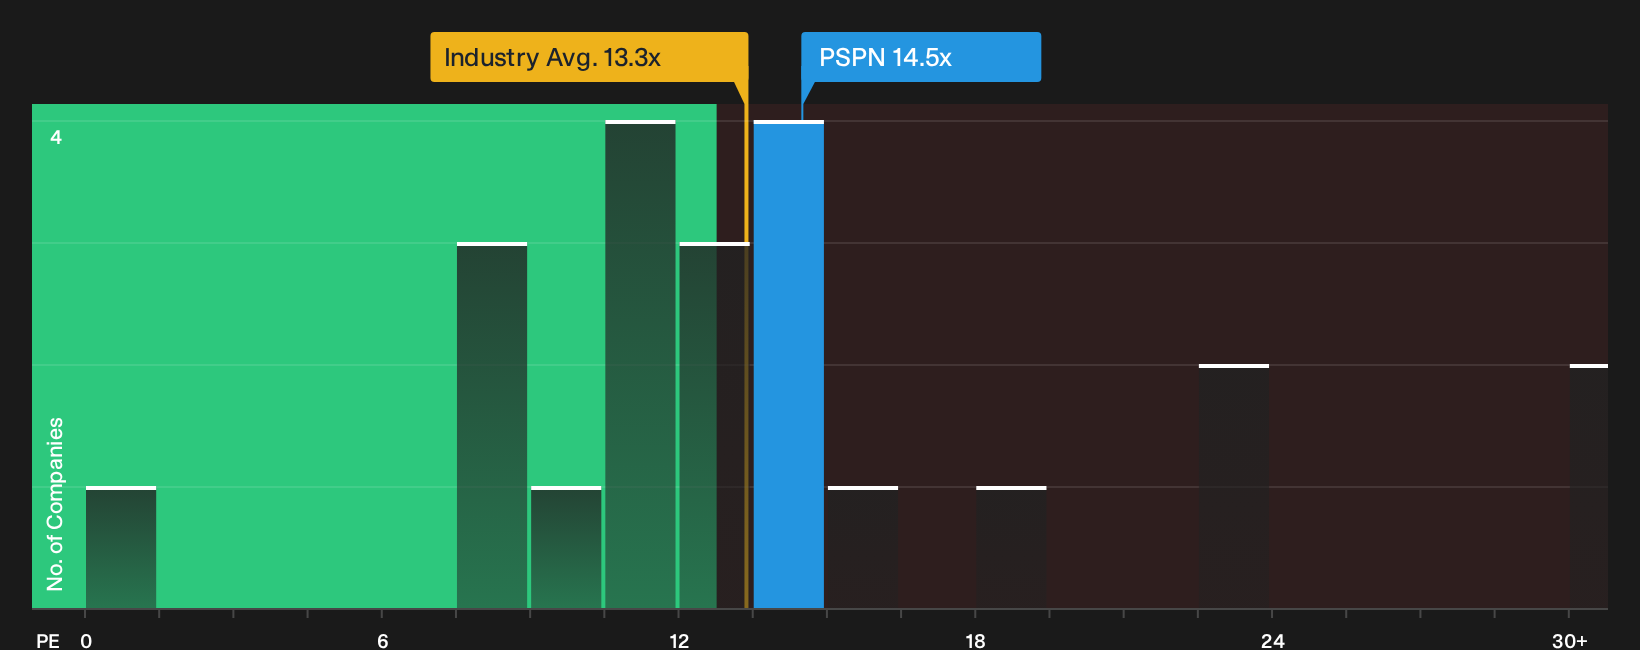
A different lens tells a softer story. On a P/E of 14.5x, PSP Swiss Property trades below the Swiss market at 20x and just under the peer average of 15.4x, while still sitting above the Swiss real estate industry on 13.3x.
That mix signals investors are paying a small premium to the sector but not a huge one to the broader market, even though the fair ratio sits higher at 16.3x. If valuation drifts toward that fair ratio, the current multiple could be viewed either as a margin of safety or as a warning that expectations are already full enough.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on PSP Swiss Property so far. Use this as a starting point, move quickly, and pressure test both sides of the story with our 2 key rewards and 3 important warning signs
Looking for more PSP Swiss Property style ideas?
If PSP Swiss Property has your attention, do not stop at a single ticker. Use the tools at your disposal and widen your watchlist with fresh, well-structured opportunities.
- Target reliable income streams by reviewing the 170 dividend fortresses that combine higher yields with balance sheets built to withstand tougher conditions.
- Hunt for mispriced quality by scanning the 184 high quality undervalued stocks where strong fundamentals meet valuations that still look restrained.
- Sharpen your downside protection by focusing on the 227 resilient stocks with low risk scores that score well on resilience while many investors remain distracted elsewhere.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com