


Columbia Sportswear (COLM) just locked in a 10 year partnership with GXO Logistics to run its main European distribution hub in Cambrai, France, in a move centered on supply chain efficiency.
For context, Columbia Sportswear’s share price has softened in the short term, with the stock down 11.13% over the past 90 days. However, the 1 year total shareholder return of 8.55% signals that longer term holders have still seen a positive overall outcome as the market reassesses supply chain moves like the GXO deal and adjusts expectations around both growth potential and operational risk.
Scan other apparel and footwear players that could be gearing up for similar supply chain shifts with our curated list of list of solid balance sheet and fundamentals (25 results).
Bulls see Columbia Sportswear using the GXO partnership and recent share pullback to set up a cleaner, leaner base. Bears point to soft recent returns and flat earnings. Which story does the valuation actually support next?
Most Popular Narrative: 19% Undervalued
Columbia Sportswear last closed at $56.53, while the most followed narrative pegs fair value closer to $69.83. This frames the current share price as a discount that relies heavily on execution around mix, margins and cash deployment.
The ACCELERATE work on brand elevation and youth targeting, supported by higher unaided awareness and increased new customer acquisition in premium footwear and elevated products, can deepen pricing power and mix, which is important for gross margin and operating margin progression.
See why 2 investors see Columbia Sportswear as 19% undervalued.
Result: Fair Value of $69.83 (UNDERVALUED)
Still, this Columbia Sportswear narrative can crack if U.S. sales remain weak or if tariffs and freight costs continue to squeeze already thin profit margins.
Find out about the key risks to this Columbia Sportswear narrative.
Another View: Columbia Sportswear Through The P/E Lens
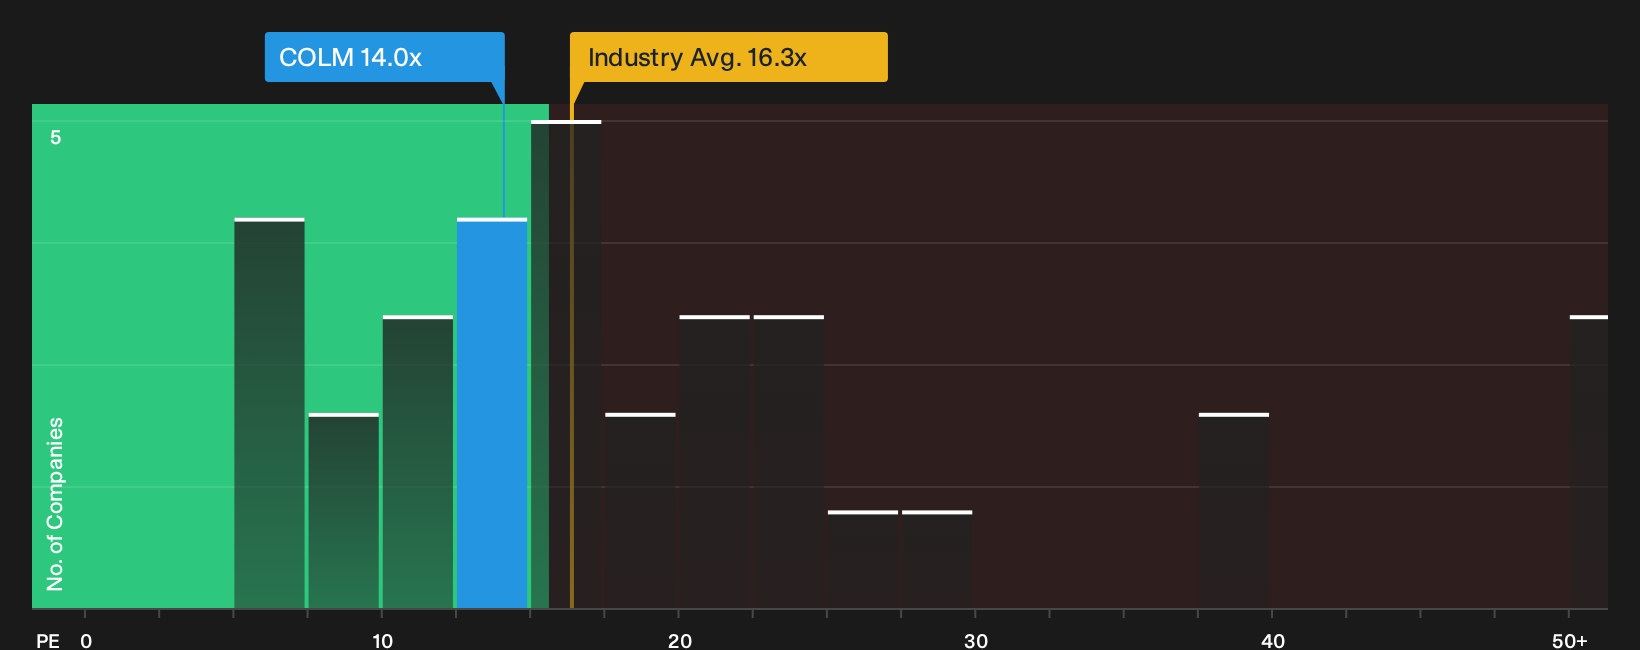
Columbia Sportswear screens differently when you swap the story narrative for simple P/E math. The stock trades around 14x earnings, which is lower than both the US Luxury industry average at 16.3x and peer levels near 27.1x, yet higher than the estimated fair ratio of 12.5x. That mix hints at some valuation support, but also leaves a question. Does paying above the fair ratio while sitting below peers really offer the kind of margin of safety you want?
For a deeper look at how this earnings multiple compares sector wide, and how the fair ratio might shift over time, check the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Columbia Sportswear story can create noise, so move quickly, review the numbers yourself, and carefully weigh both the 1 key reward and 2 important warning signs.
Looking For More Investment Ideas Beyond Columbia Sportswear?
If Columbia Sportswear has you thinking harder about price, quality, and risk, do not stop here. Broader idea hunting can sharpen your next move.
- Target financial resilience first by scanning companies with strong balance sheets and steady fundamentals using this focused list of solid balance sheet and fundamentals (25 results).
- Hunt for quality at a discount by reviewing a curated set of potentially mispriced opportunities through the 28 high quality undervalued stocks.
- Build your income stream with businesses offering higher yields and robust cash support by running through this targeted 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com