


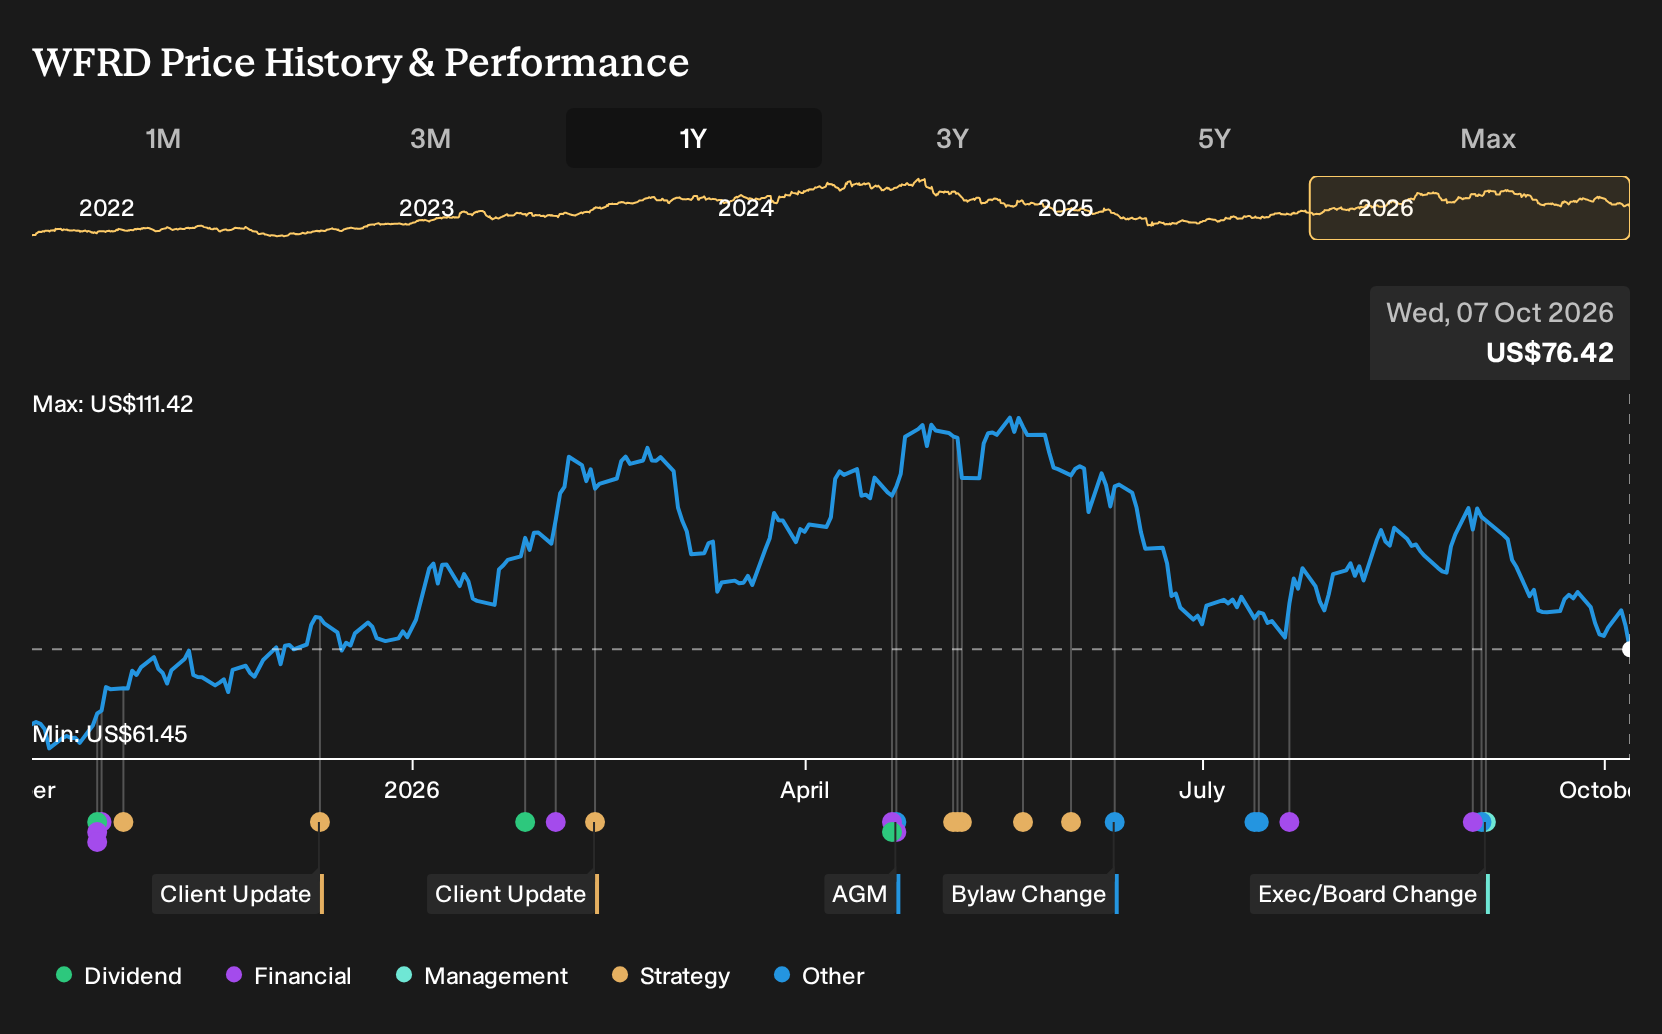
- Weatherford International recently saw its shares decline alongside a wider pullback in energy stocks as rising long term Treasury yields and moves to tap emergency fuel reserves pressured the sector.
- The market reaction comes against a backdrop of Weatherford International facing multi year revenue declines, softer customer ordering patterns and a relatively low gross margin that highlight ongoing business pressure.
- We will now explore how Weatherford International's sector driven selloff, tied to higher long term yields, may reshape its broader investment narrative.
Scan beyond Weatherford International's pullback and line up potential alternatives in the same space with the hand picked list of solid balance sheet and fundamentals (25 results).
Weatherford International Investment Narrative Recap
For a shareholder in Weatherford International, the core belief is that international and offshore spending, plus higher margin technology led services, can offset multi year revenue pressure and softer ordering. The immediate swing factor is execution in the Middle East and other key regions. The recent drop on higher long term yields appears more sentiment driven than business specific, so it does not materially change that near term focus.
The biggest risk right now is that ongoing disruptions in Iran and the wider Middle East, along with the roll off of the large Saudi LSTK contract, weigh on revenue longer than expected. Further guidance cuts on 2026 revenue or EBITDA would reinforce those concerns and could affect confidence in Weatherford International’s mix shift and free cash flow profile.
With no fresh company specific announcements tied directly to this move in long term yields, the earlier decision not to renew the Saudi LSTK integrated contract remains the most relevant development. That choice concentrates Weatherford International more in technology heavy services, which tend to carry different economics but require consistent project flow to be meaningful.
This shift is closely linked to today’s catalysts and risks. Performance depends on higher margin offerings such as completions, artificial lift and managed pressure drilling filling the Saudi revenue gap and supporting EBITDA margins. Execution missteps, or a slower than expected ramp in new work across the Middle East or deepwater markets, would increase the importance of tight cost control and free cash flow conversion for investors watching the stock after this pullback.
Weatherford International Consensus Assumptions and Valuation Setup
Analysts currently frame Weatherford International around a steady revenue build and a push toward higher profitability rather than a rapid expansion story. Their models point to revenue increasing by 4.8% each year over the next three years, with profit margins moving from 7.7% today to 11.0% over the same period. That shift in profitability underpins a move in earnings from US$366.0 million today to a forecast US$604.9 million by 2029, which is an earnings increase of about US$239.0 million.
Weatherford International's narrative projects US$5.5b revenue and US$604.9 million earnings by 2029. This setup assumes 4.8% yearly revenue growth and an earnings increase of about US$239.0 million from US$366.0 million.
On these forecasts, the analyst group as a whole is working off a future P/E of 17.4x applied to the 2029 earnings estimate, compared with a current multiple of 15.4x. That assumed valuation is still below the 22.6x P/E cited for the wider US energy services industry. Analysts also build in a small 0.06% yearly decline in the share count over the next three years, which modestly lifts earnings per share in their spreadsheets without changing the overall earnings pool in a dramatic way.
The price targets hanging over Weatherford International today are tied directly to this earnings path. The consensus target sits at US$117.08, with a bullish case of US$151.0 and a bearish marker of US$93.0. With the stock recently trading at US$78.44, that central target is 33.0% above the current price, which illustrates how much confidence is embedded in the expected revenue growth, margin lift and cash generation profile that analysts have laid out.
For an investor weighing the recent pullback, the key question is not whether these exact numbers will play out, but whether the broad contour of the forecast feels reasonable. The scenario assumes Weatherford International can move more work into higher margin services, defend pricing enough for margins to rise from 7.7% to 11.0%, and manage regional disruption without prolonged hits to activity. If those building blocks are viewed as credible, then the current valuation framework and the analyst range of outcomes can serve as a reference point for how sentiment may evolve from here.
Uncover why Weatherford International's fair value indicates a 53% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One bullish twist on Weatherford International focuses on the offshore contract pipeline starting from Q4 2026. Before this pullback on higher yields, the most optimistic analysts were pencilling in revenue of about US$5.6b and earnings near US$623.2 million by 2029. Those estimates may shift, so treat them as moving targets and compare several viewpoints.
Explore 5 other Weatherford International fair value estimates, including one that suggests as much as 199% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Weatherford International research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Weatherford International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Weatherford International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Weatherford International?
If the recent move in Weatherford International has you rethinking sector risk and upside, expanding your watchlist can give you better context and fresh options. The Simply Wall St Screener lets you quickly filter for different qualities so you can compare Weatherford International against other businesses that match your preferred profile.
- If capital preservation matters most to you, start with companies that score well on resilience and financial risk, then scan the 31 resilient stocks with low risk scores that fit those criteria.
- If you prefer opportunities that the broader market may be overlooking, broaden your search with the 20 high quality undiscovered gems and see which underfollowed stocks still show solid fundamentals.
- If you are focused on portfolio income, use the tool to filter for higher yielding payers and then review the 7 dividend fortresses that combine payouts with durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com