


Floor & Decor Holdings (FND) has been busy on the ground, opening a new Fredericksburg, VA warehouse store and design center while relocating its Clearwater, FL site without service disruption.
These store moves land at a tougher moment for Floor & Decor Holdings shares, with the stock down 27.24% on a year to date share price basis and the 1-year total shareholder return declining 35.01%. Despite that longer slide and a 17.56% drop in the 90-day share price return, the recent expansion news arrives as investors reassess whether the current US$45.82 quote already reflects those concerns or signals shifting views on future risk and opportunity.
Scan how Floor & Decor Holdings compares with other retailers investors are watching by jumping into our curated list of list of solid balance sheet and fundamentals (25 results).
Floor & Decor Holdings is growing its store footprint while the share price has fallen hard this year. Does that combination now tilt the risk reward toward buyers, or suggest caution until expectations reset further?
Most Popular Narrative: 21% Undervalued
Floor & Decor Holdings is framed as undervalued in the most widely followed thesis, with a fair value of $58.36 against the recent $45.82 close, so the focus shifts to whether its operating model can earn that gap.
The evolution toward a more capital efficient footprint, with average new store costs declining from roughly US$11.7 million in 2023 to about US$10.2 million for the 2025 class and an expected US$7.5 to $8.0 million in 2026, together with infill locations in denser markets, creates room for higher returns on invested capital and more free cash flow that can support earnings growth.
See why 13 investors see Floor & Decor Holdings as 21% undervalued.
Result: Fair Value of $58.36 (UNDERVALUED)
Still, the narrative can crack if comparable sales remain under pressure while new stores keep opening, or if laminate and vinyl weakness continues to weigh on category profitability.
Find out about the key risks to this Floor & Decor Holdings narrative.
Another View On Floor & Decor Holdings Valuation
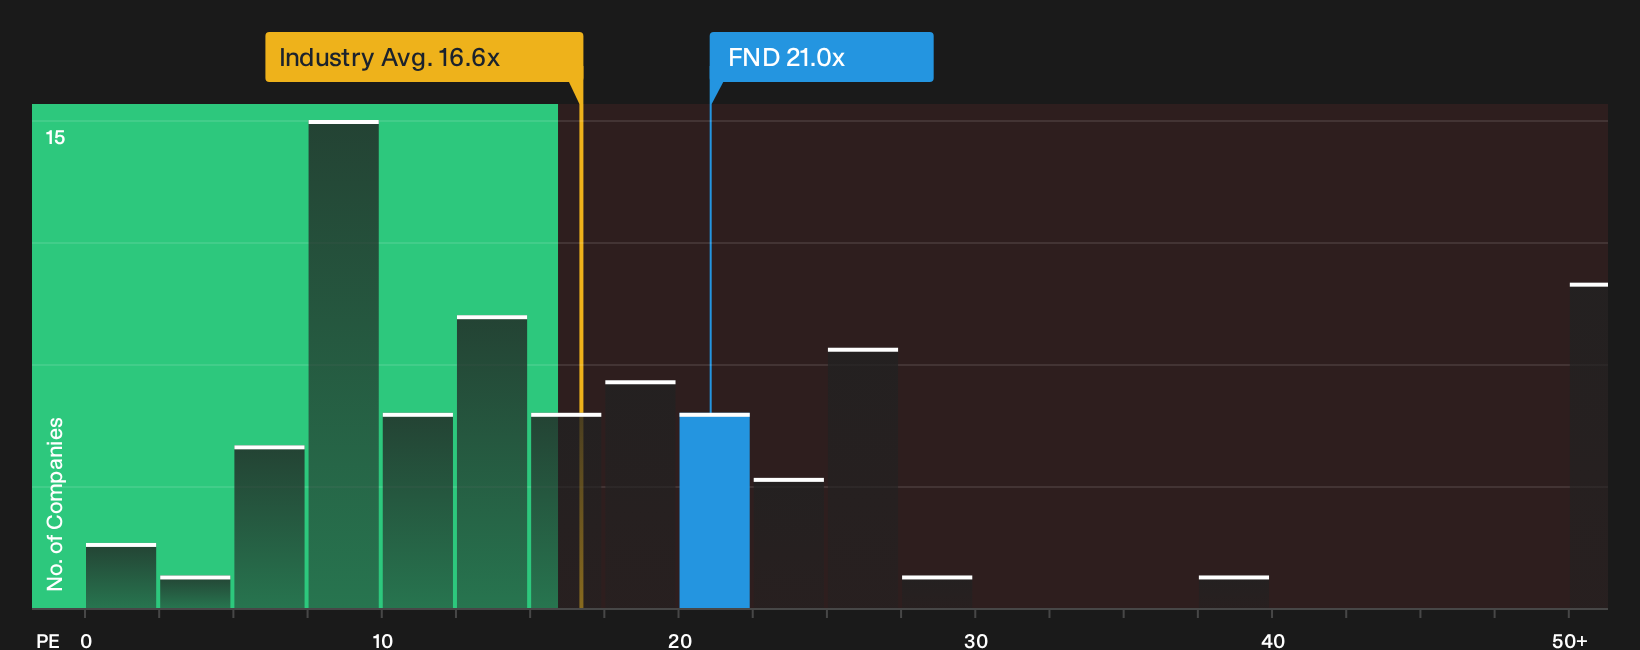
The story shifts when the P/E yardstick comes out. Floor & Decor Holdings trades around 21x earnings, which is higher than the fair ratio of 12.8x, the US Specialty Retail average of 16.6x, and a peer group closer to 10.6x. That gap points to valuation risk if expectations cool further.
Investors who lean more on current multiples than long range narratives may want to see how this premium stacks up in a full breakdown before deciding whether it still feels justified or already too stretched: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Concerned that sentiment in this Floor & Decor Holdings story feels one sided? Act quickly, review the underlying risk data yourself, and weigh that against your own expectations by starting with 1 important warning sign.
Looking for more investment ideas beyond Floor & Decor Holdings?
If you stop with Floor & Decor Holdings, you risk missing other opportunities that might suit your goals even better, so widen the search with targeted screeners.
- Target powerful income potential by scanning for companies with robust payouts and yields through the 7 dividend fortresses.
- Hunt for mispriced opportunities by focusing on businesses with strong fundamentals that still look cheap using the 29 high quality undervalued stocks.
- Prioritize capital preservation first and search for shares with steadier profiles and fewer red flags via the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com