


Prudential Financial has delivered a solid multi year gain, yet the recent pullback and fresh reinsurance activity now put the focus squarely on whether its current share price is adequately supported by its earnings power. For anyone tracking insurance stocks today, the question is less about momentum and more about what the recent price implies you are paying for Prudential Financial's profit stream.
- Over the past 3 years the stock has returned about 37.1%, which raises the issue of whether that climb has already fully reflected the insurer's earnings profile.
- The new US$5b reinsurance agreement on Japanese whole life policies may support more flexible capital usage and could influence how investors think about the durability and growth path of Prudential Financial's earnings base.
- The analysts covering Prudential Financial have run their own numbers. See what analysts think Prudential Financial's shares could be worth.
The stock's next move may depend on whether Prudential Financial's current price can be squared with what its earnings justify today.
If you want a broader comparison point while you weigh Prudential Financial's earnings power, start a watchlist using a focused screen of 29 high quality undervalued stocks.
Is Prudential Financial Still Cheap on Earnings?
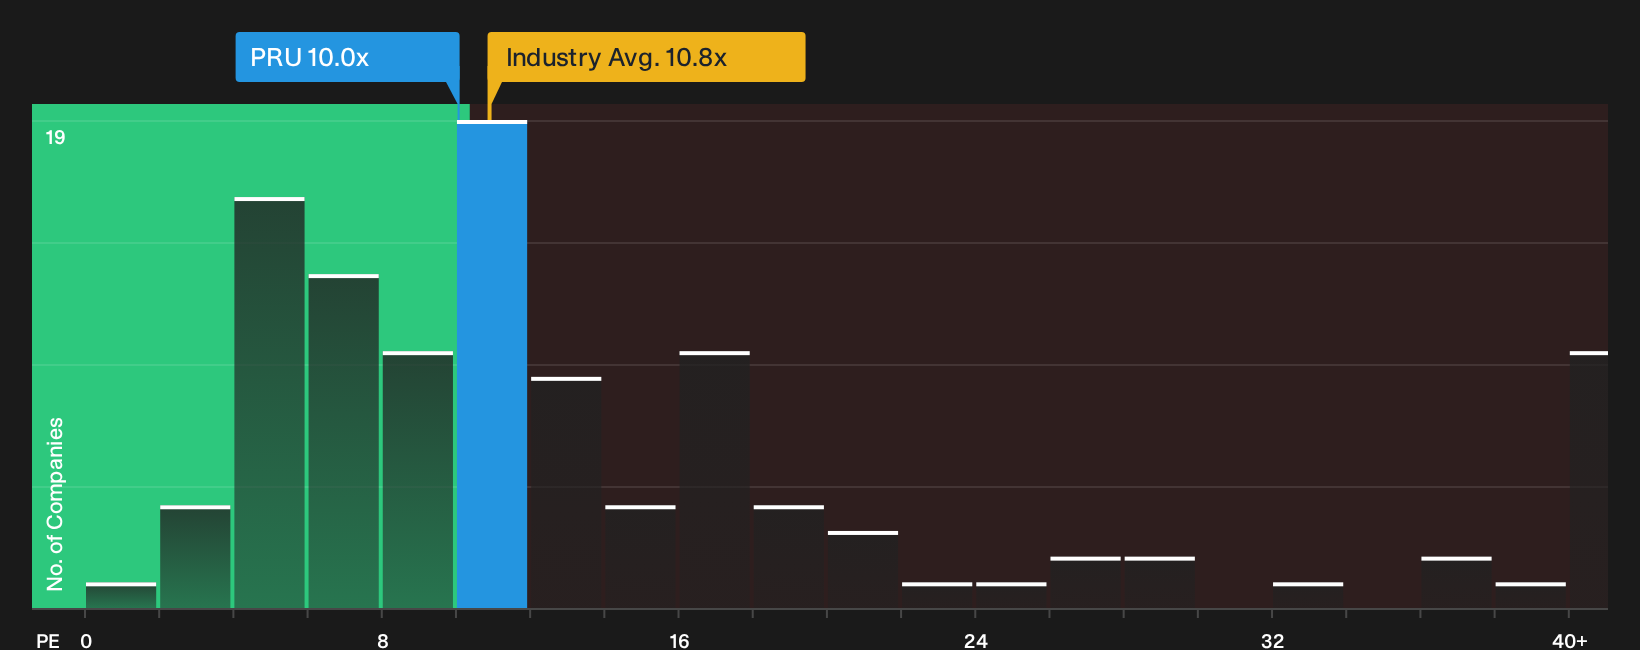
P/E tends to matter most for Prudential Financial because earnings remain the core anchor for how investors value an insurer. The stock trades on a trailing P/E of about 10.0x, which is slightly below the wider insurance group at roughly 10.8x and well under the peer average near 16.3x. That gap suggests investors are not paying a premium for Prudential Financial's earnings, even with its scale and diversified footprint.
The fair P/E that falls out of the model, which blends expectations for profitability, growth profile, risk and size, sits above where the shares change hands today. Because the new US$5b reinsurance deal is framed as a way to free up capital, the current discount on P/E raises the question of whether the market is giving full credit for that extra flexibility. For anyone weighing whether this gap reflects caution or opportunity, the next step is to compare the current multiple with the modelled fair level in more detail. Explore the numbers behind Prudential Financial's P/E valuation.
The Prudential Financial Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Prudential Financial pick up where the P/E puzzle leaves off. They lay out the future growth, margin and earnings paths that would need to hold for the stock to be worth meaningfully more or less than today’s price on the Community page. Where a single valuation ratio or model gives you one number, these narratives spell out the underlying future that number relies on so you can watch how Prudential Financial's reality lines up over time.
The Prudential Financial community splits between those who see reasonable upside from capital redeployment and those who think high expectations already crowd the story.
Bull case: roughly fairly valued
"Prudential Financial is reallocating well north of US$3b of capital by exiting multiple emerging markets and concentrating on the U.S., Japan and select European operations..."
Discover why this Narrative puts Prudential Financial at roughly fairly valued.
Bear case: 22% overvalued
"Planned exits from 6 to 7 emerging markets could release well north of US$3b of capital. However, if sale processes are slow or buyers demand discounts, Prudential Financial may see prolonged execution risk..."
Explore why this Narrative puts Prudential Financial at 22% overvalued.
One more angle on Prudential Financial that is easy to miss
Everything so far has focused on what Prudential Financial looks like today. Yet there is an entire set of professional projections that sketch where analysts think the business could be a few years from now. Explore where analysts expect Prudential Financial to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com