


Incyte (INCY) moved back into focus for many investors after U.S. regulators cleared Atebrioz for fibrodysplasia ossificans progressiva, and partners reported expedited approval of NIKTIMVO in Brazil for chronic graft versus host disease.
Recent approvals have landed against a mixed price backdrop for Incyte, with the 7-day share price return down 6.52% and the 30-day share price return down 10.50%. At the same time, the year to date share price return is 11.85% and the 1-year total shareholder return is 32.86%, pointing to longer term momentum that contrasts with the latest pullback.
Scan beyond Incyte and see how other biopharma names with similar news catalysts are setting up in our hand picked 35 healthcare AI stocks list.
Incyte now trades about 14% below the average analyst price target after a sharp pullback, even as recent approvals reshape its profile. Is that discount cushioning risk, or signaling justified market caution?
Most Popular Narrative: 12% Undervalued
Incyte last closed at $113.44, while the most followed valuation narrative pegs fair value at $128.48. That gap is based on detailed assumptions about how the post Jakafi portfolio and heavier spending interact over the next few years.
The upcoming launches and label expansions of therapies like Opzelura, povorcitinib and Niktimvo in indications such as atopic dermatitis, vitiligo, hidradenitis suppurativa and GVHD remain a key driver for Incyte. Updated 2026 guidance points to higher total net sales of US$5.13 to 5.26b and Opzelura net sales of US$1.05 to 1.10b, which helps frame expectations for future revenue and earnings.
See why 57 investors see Incyte as 12% undervalued.
Result: Fair Value of $128.48 (UNDERVALUED)
Still, the Incyte story can change quickly if key late stage trials disappoint or if heavier R&D and deal costs weigh more heavily on margins.
Find out about the key risks to this Incyte narrative.
Another View: Cash Flows Point A Different Way For Incyte
While the leading Incyte narrative leans on an earnings-based fair value of $128.48, the Simply Wall St DCF model presents a more cautious picture. On that approach, estimated future cash flows support a value of $93.58, meaning the recent $113.44 price screens as overvalued rather than discounted.
Two methods, two answers. It leaves a simple question for investors: which set of assumptions feels more realistic for a research-heavy biopharma like Incyte, earnings-based multiples or a stricter cash flow test?
Look into how the SWS DCF model arrives at its fair value.
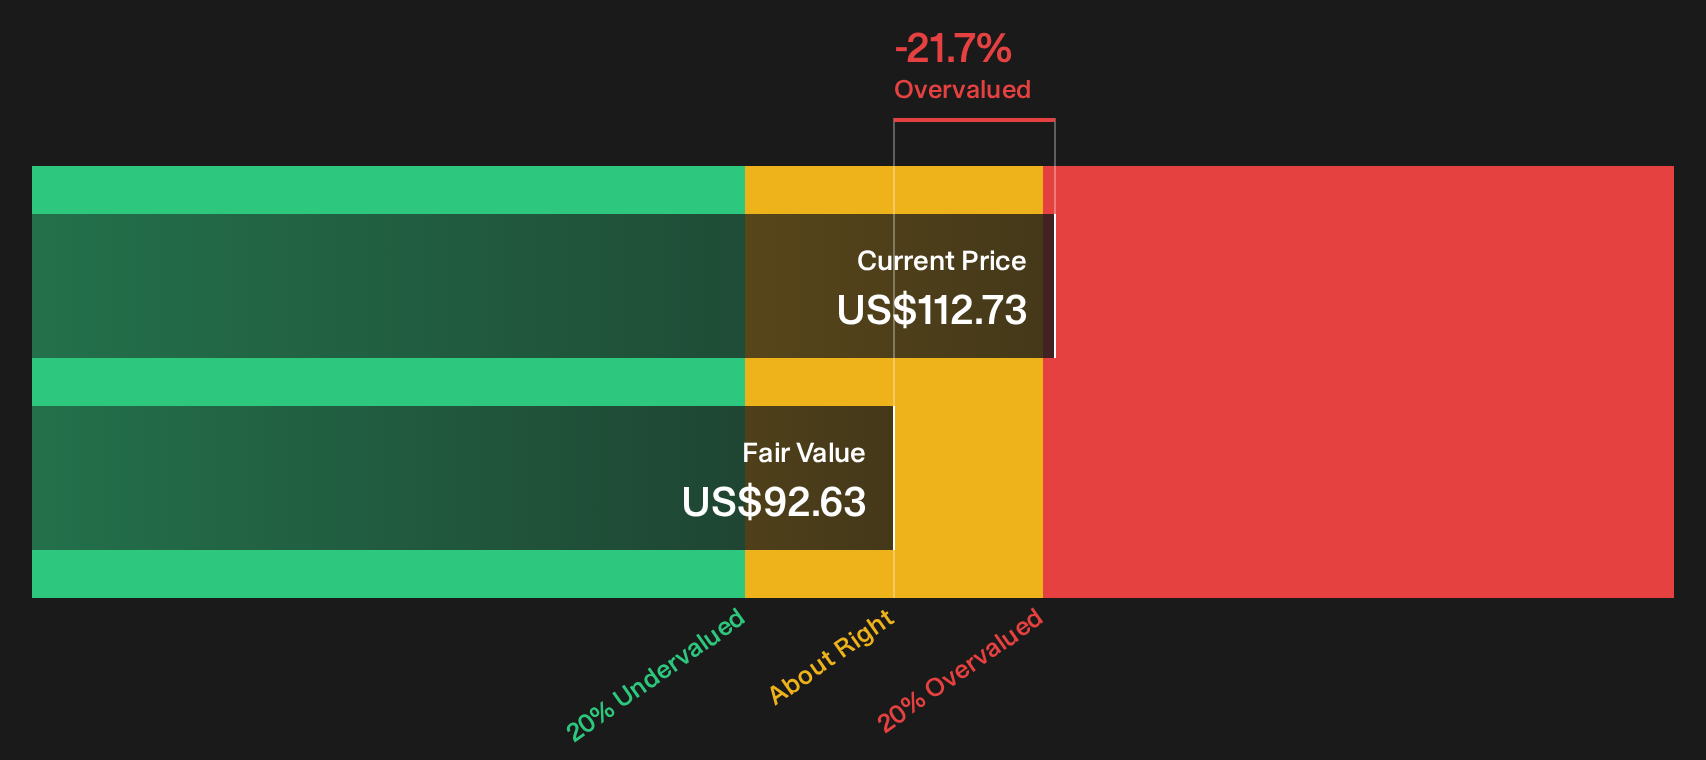
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Incyte for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Incyte so far, right, with fair value, cash flows, risks and rewards all pulling in different directions. Act while the information is fresh and pressure test the thesis yourself by weighing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Incyte?
If the Incyte setup has you thinking more broadly about opportunities, use the Simply Wall St screener to spot stocks that better match your risk and return preferences.
- Target potential mispricing early by scanning our 20 high quality undiscovered gems that pair solid fundamentals with limited market attention.
- Prioritise durability and sleep better at night with a focused 31 resilient stocks with low risk scores built around resilient balance sheets and steadier risk scores.
- Zero in on financial strength first by reviewing a curated list of solid balance sheet and fundamentals (25 results) and avoid missing sturdier alternatives while attention clusters around headline stories.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com