


Kajima (TSE:1812) drew investor focus after its recent share performance, with the stock down 4% over the past month and 17% over the past 3 months, despite positive annual revenue and net income growth.
Short term momentum for Kajima looks weak, with the share price down 3.9% over the past month and 17.1% over the past quarter. However, the 1 year total shareholder return of 6.7% and the very large 5 year total shareholder return near 3x suggest longer term holders have still been rewarded.
Scan for other construction and capital-goods stocks with similar long term return profiles and financial resilience by filtering for list of solid balance sheet and fundamentals (23 results) alongside Kajima in your research list.
The recent slide in Kajima shares comes against a backdrop of growing revenue and net income, which raises a simple tension. Are investors reassessing the business, or has sentiment just swung too far and distorted valuation?
Price to earnings of 12.2x for Kajima: Is it justified?
The valuation gap on Kajima jumps out quickly. The shares last closed at ¥4,822, while our model flags the stock as good value on a P/E basis.
The preferred gauge here is the P/E ratio. For Kajima, that figure sits at 12.2x, which links what investors are currently willing to pay to each unit of earnings the business produces.
High quality earnings, profit growth of 34.7% over the past year and improving net profit margins from 4.6% to 5.9% suggest the market could be pricing Kajima cautiously. The SWS fair P/E ratio sits at 19.4x, which is materially higher than the current 12.2x level and points to a valuation that could move closer to that fair ratio if these fundamentals persist.
Compared with peers, the picture changes. Kajima trades on a 12.2x P/E, which is more expensive than both the JP Construction industry average of 10.6x and the peer group average of 11.3x, so the market is already assigning a premium relative to sector and peer benchmarks.
Explore the SWS fair ratio for Kajima.
Result: Price-to-earnings of 12.2x (ABOUT RIGHT)
Still, Kajima faces clear risks if construction demand softens or overseas subsidiaries struggle to convert their large revenue base into consistent earnings contributions.
Find out about the key risks to this Kajima narrative.
Another view on Kajima’s value
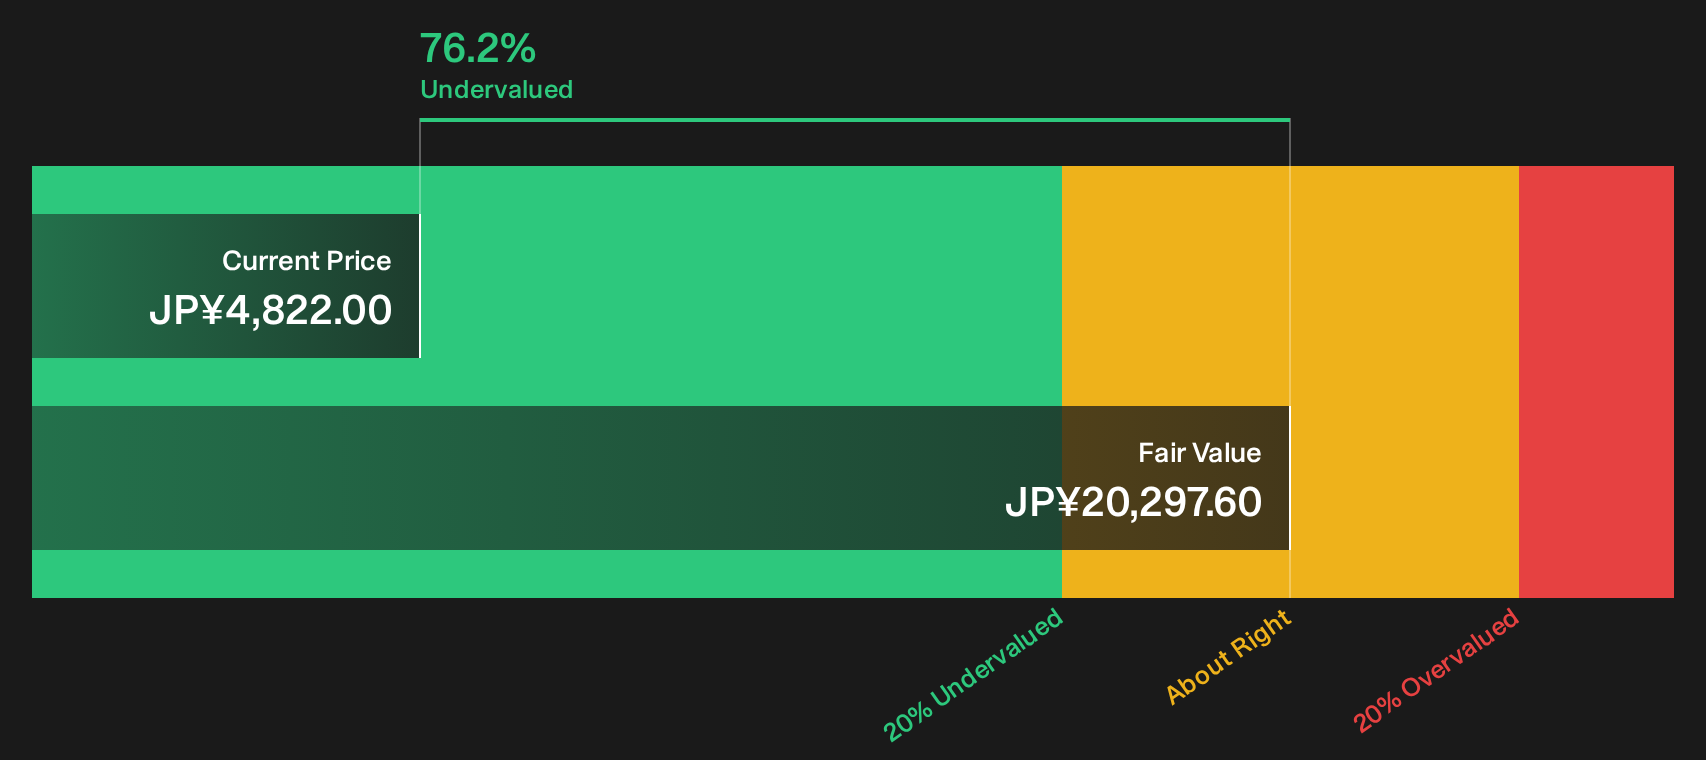
The story changes when switching from the P/E comparison to the SWS DCF model. On that lens, Kajima at ¥4,822 trades well below an estimated future cash flow value of ¥20,297.6, which screens as heavily undervalued. So which signal should investors take more seriously?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kajima for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Kajima can feel confusing, so consider the numbers while they are fresh in mind and weigh the trade off between its strengths and weak spots by checking the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Kajima?
If Kajima has your attention, do not stop there. Broaden your watchlist with a few targeted stock ideas built from clear, transparent fundamentals.
- Hunt for mispriced quality by scanning the 15 high quality undervalued stocks that combine solid fundamentals with attractive valuations.
- Strengthen your income stream by reviewing the 22 dividend fortresses that focus on higher yielding payouts.
- Protect your downside by filtering for the 22 resilient stocks with low risk scores that pair financial resilience with lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com