


Even when a business is losing money, it's possible for shareholders to make money if they buy a good business at the right price. For example, although Amazon.com made losses for many years after listing, if you had bought and held the shares since 1999, you would have made a fortune. Having said that, unprofitable companies are risky because they could potentially burn through all their cash and become distressed.
So, the natural question for Le Saunda Holdings (HKG:738) shareholders is whether they should be concerned by its rate of cash burn. In this article, we define cash burn as its annual (negative) free cash flow, which is the amount of money a company spends each year to fund its growth. Let's start with an examination of the business' cash, relative to its cash burn.
When Might Le Saunda Holdings Run Out Of Money?
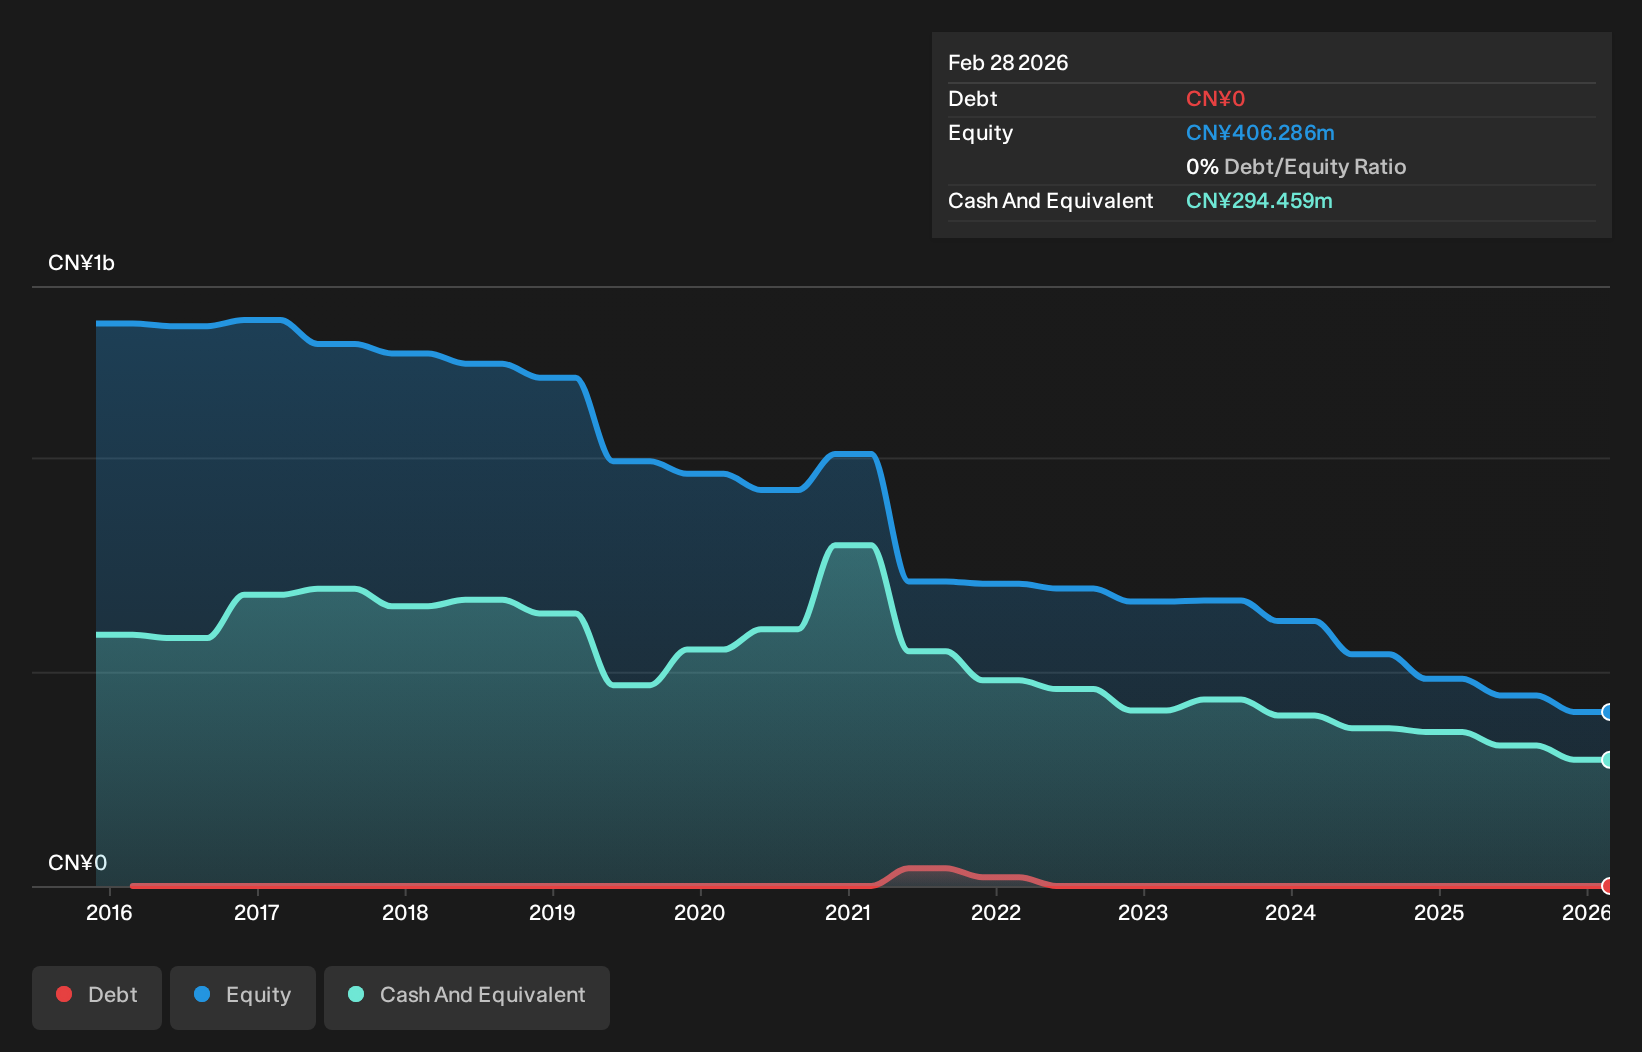
You can calculate a company's cash runway by dividing the amount of cash it has by the rate at which it is spending that cash. When Le Saunda Holdings last reported its February 2026 balance sheet in June 2026, it had zero debt and cash worth CN¥294m. Looking at the last year, the company burnt through CN¥40m. Therefore, from February 2026 it had 7.4 years of cash runway. While this is only one measure of its cash burn situation, it certainly gives us the impression that holders have nothing to worry about. Depicted below, you can see how its cash holdings have changed over time.
Check out our latest analysis for Le Saunda Holdings
How Well Is Le Saunda Holdings Growing?
One thing for shareholders to keep front in mind is that Le Saunda Holdings increased its cash burn by 2,720% in the last twelve months. While that's concerning on it's own, the fact that operating revenue was actually down 39% over the same period makes us positively tremulous. Considering these two factors together makes us nervous about the direction the company seems to be heading. In reality, this article only makes a short study of the company's growth data. This graph of historic earnings and revenue shows how Le Saunda Holdings is building its business over time.
How Easily Can Le Saunda Holdings Raise Cash?
While Le Saunda Holdings seems to be in a fairly good position, it's still worth considering how easily it could raise more cash, even just to fuel faster growth. Companies can raise capital through either debt or equity. Commonly, a business will sell new shares in itself to raise cash and drive growth. By looking at a company's cash burn relative to its market capitalisation, we gain insight on how much shareholders would be diluted if the company needed to raise enough cash to cover another year's cash burn.
Le Saunda Holdings' cash burn of CN¥40m is about 23% of its CN¥172m market capitalisation. That's not insignificant, and if the company had to sell enough shares to fund another year's growth at the current share price, you'd likely witness fairly costly dilution.
How Risky Is Le Saunda Holdings' Cash Burn Situation?
Even though its increasing cash burn makes us a little nervous, we are compelled to mention that we thought Le Saunda Holdings' cash runway was relatively promising. We don't think its cash burn is particularly problematic, but after considering the range of factors in this article, we do think shareholders should be monitoring how it changes over time. Taking a deeper dive, we've spotted 2 warning signs for Le Saunda Holdings you should be aware of, and 1 of them is potentially serious.
Of course, you might find a fantastic investment by looking elsewhere. So take a peek at this free list of interesting companies, and this list of stocks growth stocks (according to analyst forecasts)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.