


Philip Morris International (PM) has just given income focused investors fresh data to chew on. The group lifted its dividend by 8.8%, as smoke free products reached 42% of recent sales.
Philip Morris International’s share price has gathered momentum, with a 5.6% 30 day share price return contributing to a 20.2% year to date gain. Dividend reinvestment lifts the 1 year total shareholder return to 28.5% and the 5 year figure to 148.8%, indicating that investors have been rewarding its smoke free transition and sustained payouts.
Spot 7 dividend fortresses that, like Philip Morris International, pair meaningful yields with business models generating the cash flow needed to keep those payouts on solid footing.Philip Morris International now trades near a fresh high, yet analyst fair value estimates still span a wide band below and above the current US$192.69 price. Where in that spread does a reasonable valuation really land?
Most Popular Narrative: 7% Undervalued
Philip Morris International’s most followed valuation storyline points to a fair value of $208.13, modestly above the recent $192.69 close. This puts the spotlight firmly on whether its high margin smoke free mix can carry that gap.
The accelerating global adoption of smoke free alternatives, driven by increasing health awareness and regulatory moves away from combustibles, is still supporting strong growth in IQOS, ZYN, and VEEV. Smoke free products are now delivering double digit revenue and gross profit expansion at around a 70% gross margin, which can continue to support higher net revenue and operating margin mix over time.
See why 95 investors see Philip Morris International as 7% undervalued.
Result: Fair Value of $208.13 (UNDERVALUED)
Still, the Philip Morris International story can crack if cigarette volume declines outpace smoke free uptake, or if higher U.S. ZYN and IQOS spending squeezes margins.
Find out about the key risks to this Philip Morris International narrative.
Another View On Philip Morris International’s Valuation
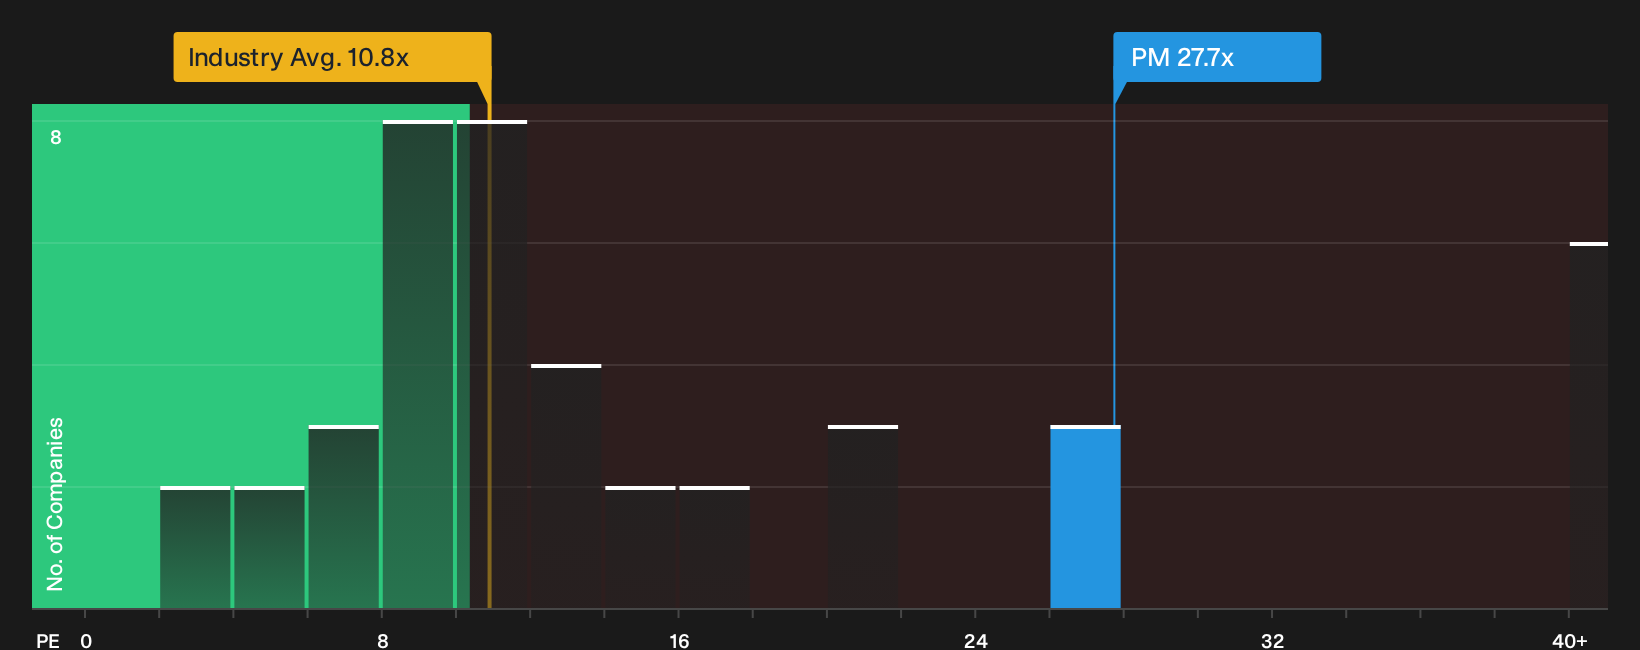
The analyst narrative sees Philip Morris International as about 7% undervalued at a fair value of $208.13. A simple P/E check tells a different story. PM trades on 27.7x earnings compared with 10.8x for the global tobacco group and 20.6x for peers, while its fair ratio is 25.9x. That premium can signal quality, or it can just mean less room for error if sentiment cools.
To see how this richer multiple stacks up against the underlying earnings profile, and what that gap could mean for future returns, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Philip Morris International story so far. Use the full data set, weigh both sides quickly, and then review the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Philip Morris International?
If Philip Morris International has sharpened your appetite for income and long term compounding, do not stop your research here. Broader opportunity often hides just outside the obvious.
Use the Simply Wall St Screener to quickly surface fresh ideas that match your style, from higher yield candidates to sturdier balance sheets and quietly compounding outliers.
- Target stronger income streams by scanning a curated set of higher yielding payers through the 7 dividend fortresses.
- Hunt for mispriced businesses with solid fundamentals using the 29 high quality undervalued stocks before other investors catch on.
- Secure more resilient anchors for your portfolio by filtering for robust finances via the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com