


Conference spotlight and earnings setup for Kinder Morgan stock
Kinder Morgan (KMI) is back in focus as investors weigh its track record of topping earnings estimates alongside fresh visibility from the Wolfe Research Utilities, Midstream & Clean Energy Conference in New York.
The share price has eased 1.1% over the last day to US$31.82, although a 5.5% 7 day share price return and 14.8% year to date gain suggest momentum has been building ahead of Kinder Morgan’s conference appearance and upcoming earnings. That short term move sits against a 17.6% 1 year total shareholder return and very strong 3 and 5 year total shareholder returns, which keeps recent volatility in the context of a longer run of value creation.
Scan Kinder Morgan alongside other hand picked infrastructure and energy plays that match its profile with the 43 power grid technology and infrastructure stocks
Bulls highlight Kinder Morgan’s recent earnings beat streak, rising EBITDA margins and solid free cash flow. Bears, on the other hand, focus on the recent run in the share price. The key question is which case the current valuation actually supports next.
Most Popular Narrative: 11% Undervalued
The most followed Kinder Morgan narrative currently points to a fair value of $35.90, which sits above the recent $31.82 close and frames the stock as modestly discounted rather than stretched into the conference and earnings window.
The current roughly $9.6b Board approved growth backlog, which is mainly tied to take or pay natural gas projects with an average in service date in the first half of 2028, is expected by management to translate into about $1.7b of incremental EBITDA over time, which could lift Kinder Morgan's future cash generation as these assets move from construction to operation.
See why 72 investors see Kinder Morgan as 11% undervalued.
Result: Fair Value of $35.90 (UNDERVALUED)
Still, the Kinder Morgan thesis leans heavily on converting its roughly US$10b opportunity set and managing leverage near 3.6x. As a result, project delays or softer returns could quickly challenge that undervalued narrative.
Find out about the key risks to this Kinder Morgan narrative.
Another View: Kinder Morgan Through The P/E Lens
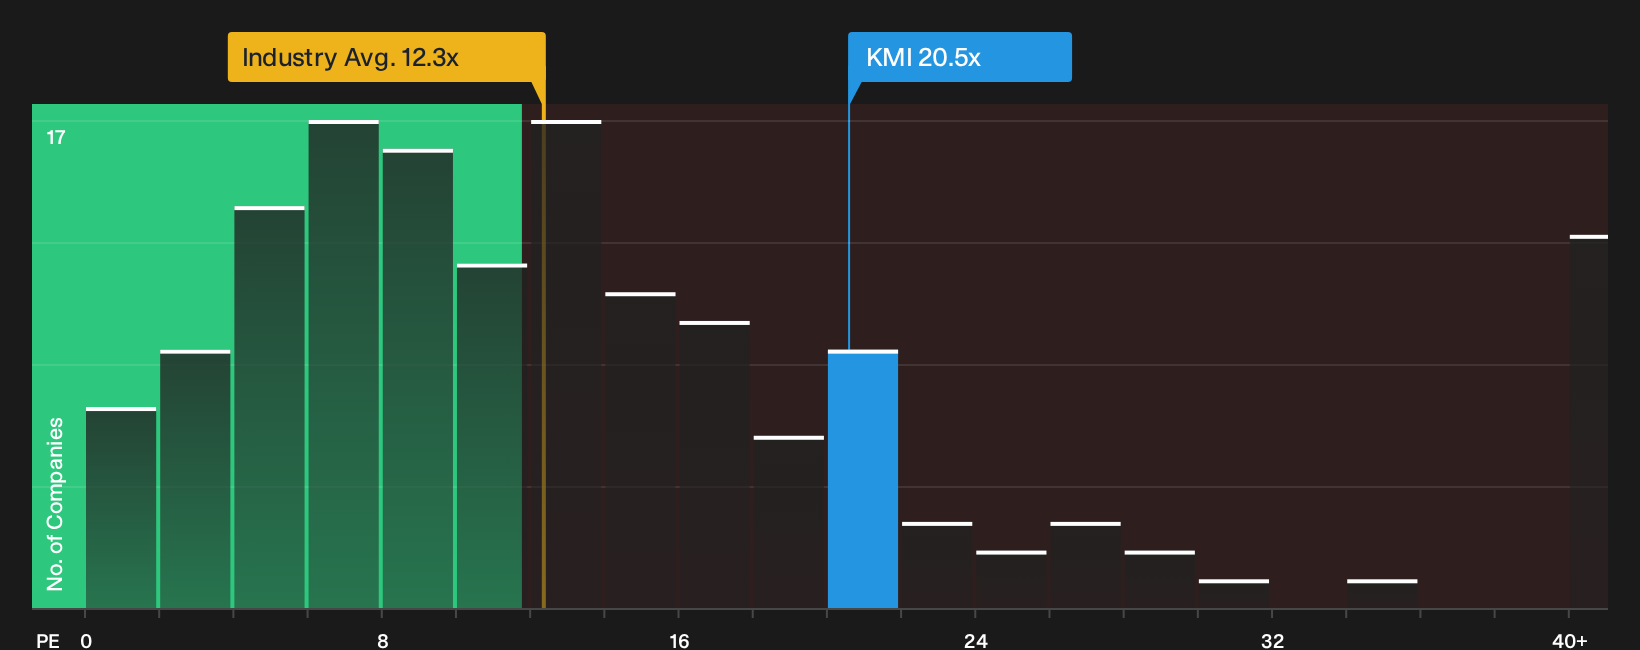
The first take frames Kinder Morgan as trading below a fair value of $35.90. Yet on a simple P/E check, the stock looks full rather than cheap. The current 20.5x multiple sits a touch above a 20.1x fair ratio and well ahead of the US Oil and Gas industry at 12.3x, as well as a 16.5x peer average. That gap can mean investors are already paying up for Kinder Morgan’s fee based model, which leaves less margin for error if growth or project execution disappoints.
For readers who want to see how this earnings based view compares with a full forward cash flow framework, it is worth lining it up against the SWS DCF model next, then asking which set of assumptions feels more realistic for Kinder Morgan’s next few years. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Kinder Morgan story so far. Move quickly, examine both the bullish and cautious perspectives, and then weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Kinder Morgan?
If Kinder Morgan has sharpened your appetite for opportunities, do not stop here. Fresh ideas often come from comparing it with very different types of stocks.
Spot potential outliers early by scanning a curated pool of 20 high quality undiscovered gems that pair strong fundamentals with less crowded ownership.
Rebalance toward resilience by reviewing a focused 31 resilient stocks with low risk scores designed to highlight businesses with sturdier financial profiles and lower measured risk scores.
Strengthen your income stream by checking a targeted 7 dividend fortresses built around higher yielding companies that still aim to keep payouts supported by fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com