


Targa Resources (TRGP) continues to attract attention after its recent share price move, with the stock closing at US$283.96. Recent returns, including a gain over the past year, now frame the valuation debate.
Recent trading has been choppy, with a 5.05% 7 day share price return offset by a 2.10% decline over 30 days. Yet Targa Resources still carries strong momentum when you step back to its 52.04% year to date share price return and very large 5 year total shareholder return of 481.88%.
Scan beyond Targa Resources and see how other pipeline and energy infrastructure players are moving with our curated list of 43 power grid technology and infrastructure stocks.
After a 52.04% year to date run, Targa Resources still trades about 15% below the average analyst target and at a much bigger modeled intrinsic discount. Is that a margin of safety or a warning signal?
Most Popular Narrative: 13% Undervalued
Targa Resources screens as undervalued against a narrative fair value of $325.14 compared with the latest $283.96 close. This puts the focus squarely on whether its long dated Permian and export projects can deliver the cash flows that model implies.
An expanding set of long dated growth projects, including the Speedway NGL system with initial 500,000 barrels per day of capacity, multiple Permian gas plants scheduled through early 2028, a 20 year processing and downstream volume agreement with a large producer and a 230 megawatt behind the meter power deal to support Permian processing, collectively increases Targa’s potential share of basin volumes and can support higher revenue and adjusted EBITDA over time.
See why 18 investors see Targa Resources as 13% undervalued.
Result: Fair Value of $325.14 (UNDERVALUED)
Still, the Targa Resources story could be tested if Permian infrastructure proves overbuilt and fees compress, or if heavy project spending delays the expected free cash flow lift.
Find out about the key risks to this Targa Resources narrative.
Another View: What Targa Resources’ P/E Is Signaling
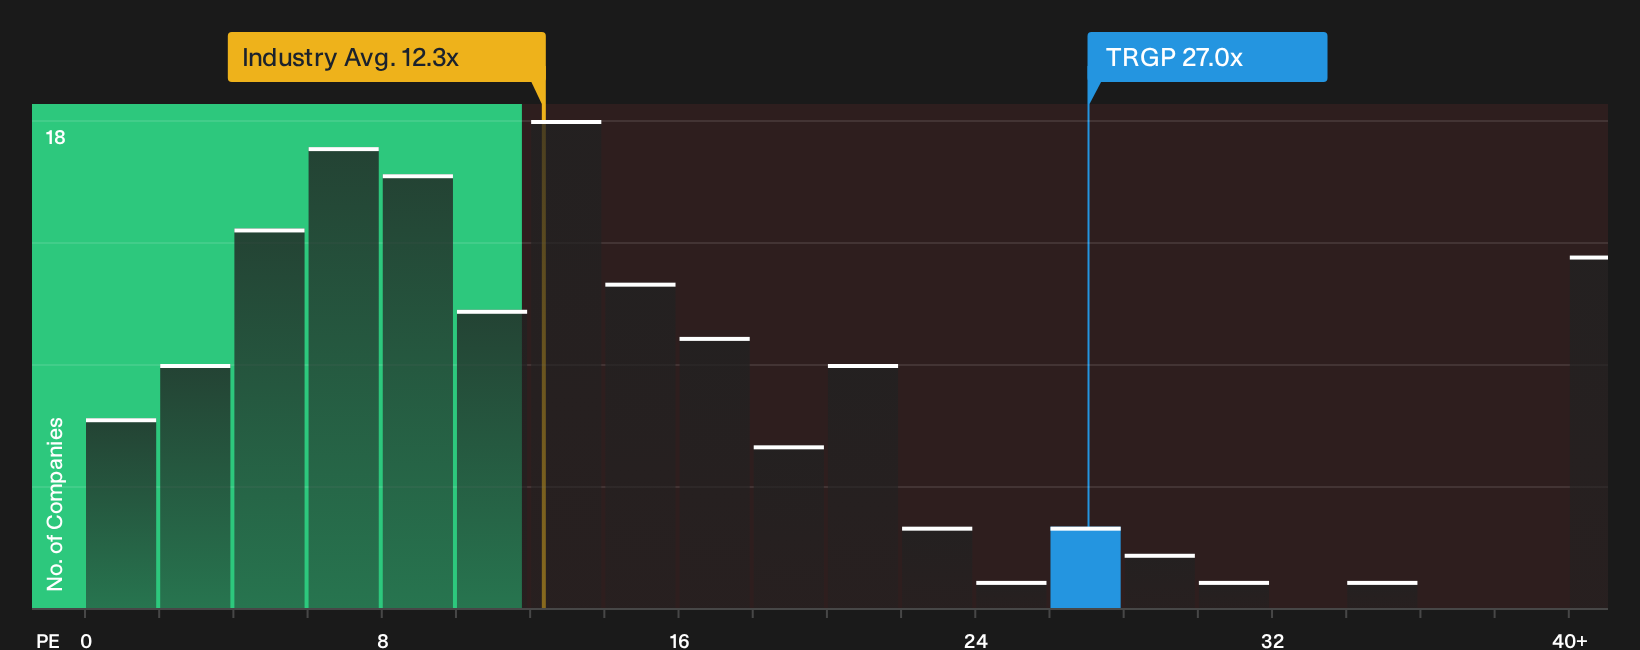
Targa Resources looks far less cheap when you switch from fair value models to simple earnings multiples. The stock trades on a P/E of 27x, compared with 12.3x for the broader US Oil and Gas group and 16.6x for direct peers. The fair ratio sits lower again at 22.7x, which points to valuation risk if sentiment cools.
For a deeper look at what the numbers imply at different earnings levels, review the See what the numbers say about this price — find out in our valuation breakdown..
Visualize how Targa Resources lines up against its sector peers on this measure with
Next Steps
Mixed signals on Targa Resources so far. If you want to move from headline takes to your own framework, start by weighing the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Targa Resources?
If Targa Resources has sharpened your focus, do not stop here. Broader opportunities across markets can help you stress test your thinking and refine your watchlist.
- Target potential mispricing by scanning companies that combine quality fundamentals with discounted valuations through the 29 high quality undervalued stocks.
- Build a steadier income stream by reviewing a curated set of higher yielding payers using the 7 dividend fortresses.
- Reduce portfolio stress by focusing on financially resilient businesses through the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com