


Fortrea Holdings (FTRE) is back in focus after Barclays upgraded the stock, linking its call to resilient net new bookings, an expected margin recovery, and the company’s higher full year revenue guidance.
Recent trading tells a story of rebuilding confidence in Fortrea Holdings. The stock’s 30-day share price return of 16.16% and year to date share price return of 22.31% come after a 1-year total shareholder return of 102.96%, despite a weaker 3-year total shareholder return that declined 29.71%. Short term momentum has picked up around the Barclays upgrade and the appointment of a permanent Chief Accounting Officer, suggesting that investors are reacting to both operational signals and perceptions of improving execution risk.
Capitalize on the renewed interest around Fortrea Holdings and scan a curated 29 high quality undervalued stocks showing similar businesses with solid cash generation and balance sheets.Fortrea Holdings has already delivered a sharp rebound, yet the stock still trades at a sizeable intrinsic discount. Does that gap offer enough potential upside to justify the risks from here?
Most Popular Narrative: 10% Overvalued
Fortrea Holdings last closed at $20.56, almost exactly in line with the most followed fair value estimate of about $20.55, yet that framework still tags the shares as modestly overvalued when the discount rate of 9.46% and long term assumptions are taken together.
Fortrea's ongoing investments in AI-driven software (for example, the Accelerate platform's Risk Radar module) and digital capabilities are enabling operational efficiencies and differentiated offerings in a market moving toward more technology-enabled, decentralized clinical trials; this is expected to positively impact EBITDA margins and margin expansion.
See why 8 investors see Fortrea Holdings as 0% overvalued.
Result: Fair Value of $20.55 (OVERVALUED)
Still, Fortrea Holdings faces pressure from intense CRO pricing competition and high customer concentration, which could restrain margins and unsettle revenue visibility if large clients pull back.
Find out about the key risks to this Fortrea Holdings narrative.
Another View: Fortrea Holdings On Sales-Based Value
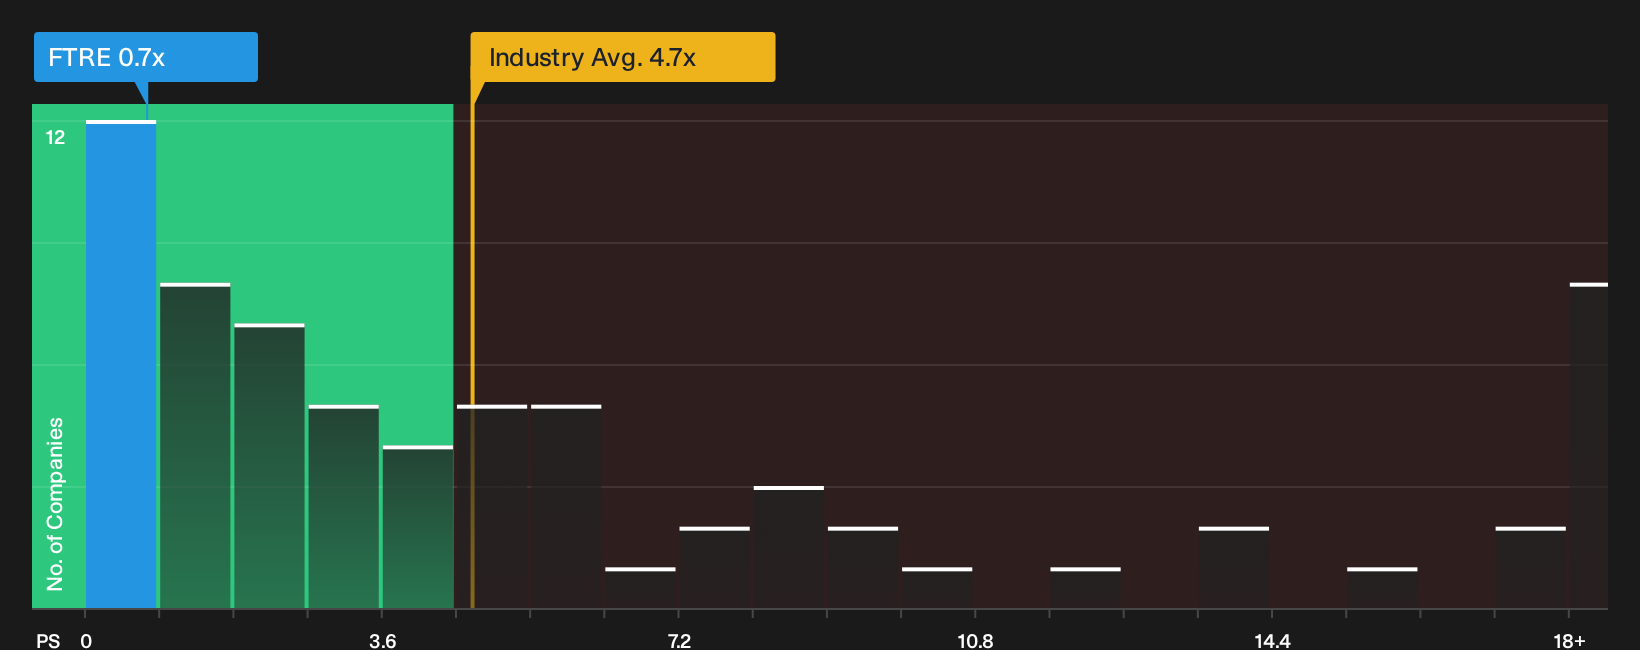
The first framework tags Fortrea Holdings as modestly overvalued on an earnings driven fair value of about $20.55. A very different picture comes through P/S. At roughly 0.7x revenue, the stock trades well below the US Life Sciences group at 4.7x and a fair ratio of 2.3x.
That gap suggests the market is applying a steep discount to Fortrea Holdings relative to both peers and the level the P/S multiple could move toward if sentiment and fundamentals line up. The key question is whether current execution and risk justify such a wide spread.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Fortrea Holdings so far, with both risks and bright spots in view. Consider acting promptly and test the thesis against your own expectations with the full breakdown in 3 key rewards and 1 important warning sign
Looking for more Fortrea Holdings style investment ideas?
Do not stop your research with Fortrea Holdings alone, because the best opportunities often sit just outside the stocks already on your radar.
- Hunt for mispriced quality by scanning a focused group of 29 high quality undervalued stocks that combine sturdy cash flows with disciplined capital allocation.
- Target durability first and shortlist companies from a 31 resilient stocks with low risk scores that screens for resilient balance sheets and lower risk profiles.
- Get ahead of the crowd by tracking a curated pool of 20 high quality undiscovered gems with strong fundamentals that have attracted less market attention so far.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com